2Mês·

FDA approval, CEO insider purchases, and a $7 billion market opportunity: The highly speculative biotech shot for the moon—for the bold! 🚀

Hey there, fellow investors! 🚀


Today, we’d like to send a very special shout-out to our second-favorite member of the group: @Multibagger – our self-proclaimed self-made stock junkie and “get-rich-quick” specialist! 😉


Dear Chris, I promised you earlier this week that you’d get your money’s worth, too. While we usually focus on solid cash-flow giants, today we’re serving up exactly what you specialize in:

A real high-stakes gamble where things get really heated, where massive opportunities await—but where it’s far from all sunshine and roses!


Today we’re diving deep into one of the most important and emotionally charged topics of our time: cancer research and the development of next-generation precision medicine. My AI partner and I have pored over the latest data from a biotech pioneer whose research aims to take the fight against leukemia to a whole new level.


We’re not talking about a cozy dividend cash cow here, but a hard-hitting biotech satellite in the oncology sector that’s currently taking the market by storm with its first FDA-approved cancer drug.


Grab a fresh cup of coffee, sit back, and buckle up. Curtain up for Kura Oncology! 💥

$KURA (+0,11%)

attachment


1. What does the company do?


Kura Oncology Inc. is a U.S.-based commercial-stage biopharmaceutical company specializing in the development of precision cancer therapies. At the heart of the company is the drug KOMZIFTI™ (ziftomenib). It received full FDA approval in November 2025 for adult patients with a specific form of acute myeloid leukemia (relapsed/refractory NPM1-mutated AML). With this, Kura has made the leap from a pure research company to a commercial pharmaceutical player.


2. Geographic Presence & Pipeline Portfolio


Kura is currently rolling out KOMZIFTI primarily in the U.S. market but is expanding globally. Through a strategic partnership with the Japanese conglomerate Kyowa Kirin , marketing outside the U.S. (including Asia and Japan) is being advanced. In addition to KOMZIFTI for leukemia treatment, Kura has Darlifarnib (KO-2806) , a second candidate currently being tested in clinical trials for renal cell carcinoma (RCC) and pancreatic cancer.


3. Key Figures, Data & Facts (as of August 2026)


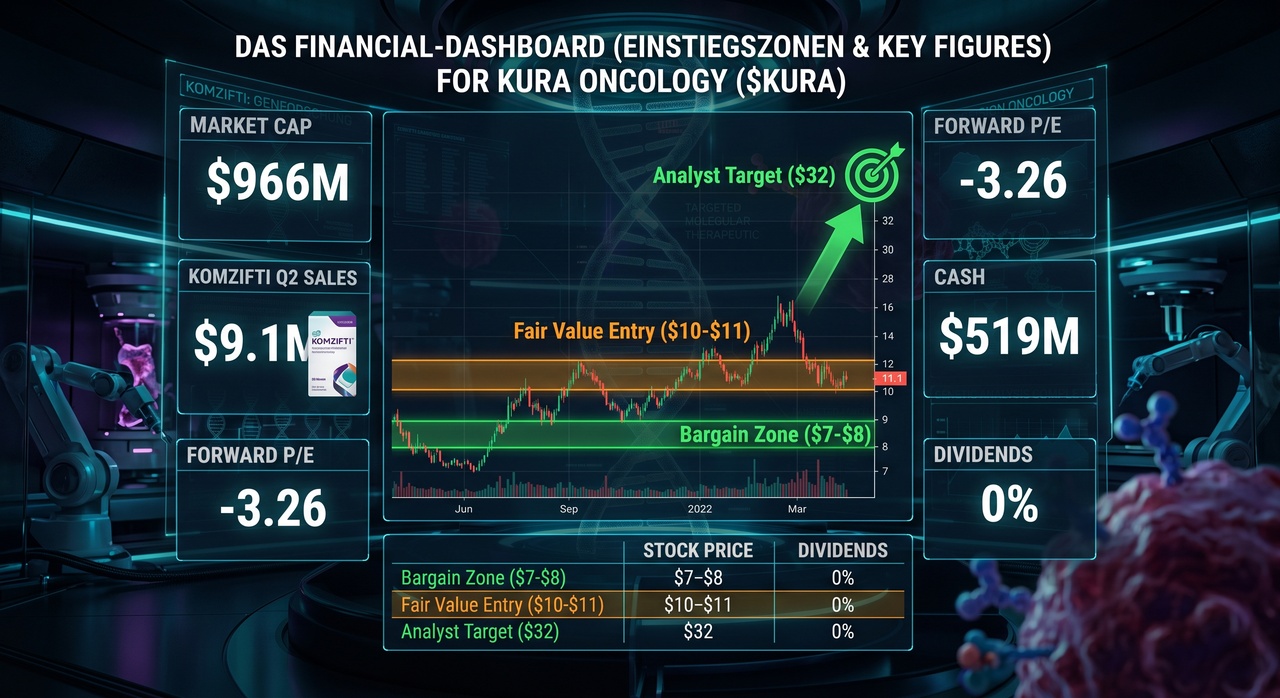
  • Current share price: ~10.03 EUR or 10.90 USD.
  • Market capitalization: ~966.1 million USD (~890 million EUR) – A classic small- to mid-cap company.
  • P/E Ratio (Forward 2026): -3.26x (highly unprofitable).
  • Net income Q2 2026: -68.3 million USD.
  • Product revenue Q2 2026: $9.1 million with KOMZIFTI in the second full quarter of sales (+35% new patient starts QoQ).
  • Cash reserves: $519 million in cash reserves + $180 million in expected milestone payments from Kyowa Kirin.
  • Dividend yield: 0.0%.


attachment


4. Check against our established formulas


  • Core Quality Formula: Historical revenue growth stands at -7.3%, and the EBIT margin is deep in negative territory (-411.9%) due to high R&D expenses. Score: Failed.


  • Cash Flow Quality Formula: The FCF yield is -11.3%. The company is currently burning through massive amounts of cash on marketing and clinical trials.


  • Dividend Filter: 0.0% yield. For our Income-Core strategy, the stock completely fails to meet our criteria.


  • Exclusion Rule (Red Card):
    Stop signal for the conservative portion! Kura violates all criteria of our Core portfolio (no profit, negative cash flow, story > numbers). However: For our barbell strategy as a highly speculative addition (satellite), Kura is purely a play on the future.


5. Chart Analysis of the Last Few Months


  • Price trend: On a year-to-date basis, the stock is up +48.0% .


  • Moving averages: The stock is currently trading at around +12.5% above the 50-day moving average and +21.1% above the 200-day moving average.


  • Technical Score: The technical indicators and moving averages on InvestingPro signal a clear "Strong Buy". Momentum is absolutely intact.


6. Special Entry Zones (“Bargain Hunter’s List”)


  • Bargain Zone (Absolute Bargain): €6.50 – €7.50 ($7.00 – $8.00). This was the range prior to the most recent breakout.


  • Fair-Value Entry: €9.50 – €10.50 (~$10.00–$11.00). Current level for initial speculative positions.


  • Price Target / Take-Profit: Analyst consensus at €27.37 ($32.00); top forecasts reach as high as €65.00 ($76.00).


7. Risk Deep Dive 1: Unprofitability & KOMET-017 Risk


Kura is burning through a massive amount of cash.

In the second quarter of 2026, the loss amounted to $68.3 million.

The entire long-term investment case stands or falls with the Phase 3 trial KOMET-017. If the data disappoints in 2028, the foundation of the growth story will collapse.
attachment

8. Risk Deep Dive 2: Competition & FDA Warning


  • Black Box Warning: KOMZIFTI carries a regulatory warning label for a potentially fatal “differentiation syndrome.” This could make some doctors cautious about prescribing it.


  • Competition: With Syndax Pharmaceuticals
    $SNDX (-0,06%) is a direct rival vying for market leadership in Menin inhibitors. Furthermore, heavyweights like Pfizer and Novartis are not sitting idly by in leukemia research.


9. Future Outlook & Growth Drivers


The potential is enormous:

With KOMZIFTI in first-line therapy (frontline AML), Kura is targeting a total addressable market (TAM) of $7 billion . Management expects the drug to generate peak annual sales of up to $3 billion annually . Should the KOMET-017 study yield positive results in 2028, Kura will transform from a small-cap company into a billion-dollar corporation.


10. Competition & Alternative Candidates


  • Syndax Pharmaceuticals ($SNDX): The direct peer in the field of Menin inhibitors.


  • Relay Therapeutics $RLAY
    / Tango Therapeutics $TNGX
    : Biotech peers with similar valuations in the precision oncology sector.


11. Liquidity & Balance Sheet Analysis


Biotech companies depend on their runway (how long their cash will last).

Kura is in an excellent position here:

With $519 million in cash and an additional $180 million from Kyowa Kirin , the company is fully funded through the pivotal KOMET-017 data readout in 2028! There is no risk in the short term of no nasty capital increase or dilution.


12. Analyst Opinions & Fair Value


  • Consensus: Bullish! 14 analysts recommend buying, 1 recommends holding, 0 recommend selling.


  • Average price target:
    $32.00 (~€27.37). This corresponds to a massive upside potential of +157.8% from current levels!

attachment


13. Upcoming Catalysts


  • H2 2026: Clinical combination data for KOMZIFTI + FLT3 inhibitors.


  • H1 2027: Start of the platform study for darlifarnib in pancreatic cancer.


  • 2028: The Mega Catalyst – Top-line results from the Phase 3 KOMET-017 study.


14. Sentiment & Insider Activity


In recent weeks, there have been two extremely positive signals:


  • The CEO of Kura has been buying back the company’s own shares on a large scale, which is a massive vote of confidence from top management!


  • The Q2 results significantly exceeded analysts’ expectations for EPS (–$0.77 vs. –$0.88 expected) and revenue.


15. Long-Term Viability & My Personal Conclusion


Dear Community, let’s not kid ourselves:

Kura Oncology $KURA (+0,11%)
is not a crisis-proof dividend anchor, but a high-stakes, highly volatile biotech bet!


But for those who have room in their strategy for risk capital, this is an extremely exciting setup:

An FDA-approved drug, a cash pile that’s well-stocked through 2028, CEO insider purchases, and an analyst target of over +150%.

For me personally, this is a fascinating satellite stock on my watchlist!


Best regards from Denmark


RaketenToni


@Keineui

@Aktienhauptmeister

@Multibagger

@Tenbagger2024

@Get_Rich_or_Die_Tryin

@Stocktective

@Simpson

@WarrenamBuffet

@SAUgut777

@TradingHase

@PikaPika0105

@Derspekulant1

@NichtRelevant

@Klein-Anleger

@Dividendenopi

and, of course, everyone else :)

23
21 Comentários

imagem de perfil
I have room for venture capital, but I don't have the cash for solid investments. But unfortunately, my venture capital is also limited. So I’ll have to decide whether to go with your potential tenbagger or the potential 100-bagger I discovered this morning: $GENB. They’re working on revolutionizing the entire drug development process. 😉
•
3
•
imagem de perfil
@Multibagger I'll quickly run these through the analysis for you
•
1
•
imagem de perfil
@Raketentoni In terms of the numbers, it doesn't look a bit better. Even bigger opportunities, even more risk. If this type of platform catches on, it will revolutionize the entire drug development process. If not, the company will go bankrupt. But the 25-page stock report I read this morning really got me hooked, and the research was solid.
••
imagem de perfil
@Multibagger Hey Chris! 🚀

Of course, your investor’s heart starts racing the moment you hear the terms “Generative Biology” and “100-bagger”! 😉

I took a close look at your new find, **Generate Biomedicines ($GENB)**, analyzed the weekly charts, and put the key metrics through their paces.

Here’s the no-holds-barred comparison between your **$GENB** and our **$KURA**:

---

### 1. AI Dream vs. FDA Approval (The Fundamental Difference)

* **Generate Biomedicines ($GENB):** The story sounds incredibly appealing—AI and machine learning for biological drug development. **BUT:** The company is in an ultra-early stage. The EBIT margin stands at a disastrous **-991.2%**, and revenue for the last quarter was a meager €5.47 million.

* *The catch:* According to the analyst consensus, the market doesn’t expect the first positive earnings per share (€0.77) until **2032**! So you’re essentially buying into a pure research hope for the next 6 years.

* **Kura Oncology ($KURA):**
Kura is no longer just a pipe dream—it’s already a **commercial biotech player**.
Its cancer drug KOMZIFTI has already received full **FDA approval** and is generating real revenue ($9.1 million in product revenue in Q2 2026 alone, +35% new patient starts).

---

### 2. Fair Value & Chart Check (Weekly Basis)

* **Chart $GENB:**
Technically, the weekly chart doesn’t look bad at all. The price stands at €13.85 (approx. $16.23), the RSI is in a healthy range at 58.04, and the MACD is positively signaling a buy.

* *However:*
The price is touching the upper Bollinger Band ($17.16) and is already well **above InvestingPro’s fair value** (€11.52 / -16.8% downside risk). So, in the short term, the market has already driven this story up quite a bit.

* **Chart & Valuation for $KURA:**
Kura is up +48% year-to-date and has a **100% buy rating** from 14 analysts (0 sell ratings). The average price target is **$32.00 (+157.8% upside potential)**.

---

### 3. Runway & Financial Health

* **$GENB:**
FCF yield of -11.7% and a weak quality rating (2/5). The risk of dilution from future capital increases is extremely high given the lean period extending through 2032.

* **$KURA:** Has **$519 million in cash**
on the books, plus $180 million from the Japan partnership. That fully **funds** research and the KOMET-017 study **through 2028**, without the need for shareholders to inject fresh capital! In addition, there were recent insider purchases by the CEO.

---

### 🔥 My honest take for you, Chris:

If you want to put your hard-earned risk capital into a **pure sci-fi bet** that might go through the roof in 6 to 8 years (or get massively diluted along the way), then go with **$GENB**.

But if you’re looking for a **real, validated high-risk/high-reward candidate** that:

1. Already sells an FDA-approved cancer drug,


2. Is fully funded through 2028,


3. Is being bought up by the CEO himself, and


4. Can tap into a $7 billion market,

...then **Kura Oncology ($KURA)** has by far the better risk-return profile for your portfolio!

Make a wise decision, my friend! 🚀
•
1
•
imagem de perfil
It's your decision, but I understand where you're coming from. Here's the response from my new project:

I generally find Generate Biomedicines exciting, but you should know what you’re getting into here. The company isn’t a profitable pharmaceutical firm, but rather a clinical biotech stock whose valuation is based primarily on its pipeline and AI-powered platform.

Its lead candidate, GB-0895, is already in two Phase 3 trials for severe asthma and may only need to be administered twice a year. In addition, there’s a COPD program, initial oncology projects, and collaborations with Amgen and Novartis. The approximately $457 million in cash and cash equivalents provides the company with solid financing for the time being.

However, there is a significant downside: In the last quarter, collaboration revenue totaled only $6.3 million, while the loss amounted to $67.3 million. In the first half of the year, $138 million was spent on operations. The available cash is expected to last until the first half of 2028; further capital raising is very likely after that.

In addition, the crucial Phase 3 results are still several years away, and there is already strong competition in the asthma market. Furthermore, the potential billions from the Amgen and Novartis contracts are performance-based milestones, not guaranteed revenue.

My advice, therefore, would be: don’t buy solely because of the term “AI biotech” or high analyst price targets. Generate is an interesting speculative addition to a portfolio, but not a safe core holding. In the short term, I would also wait for the IPO lock-up period to expire on August 26 and for the COPD data to be released on September 8.
•
1
•
imagem de perfil
For now, the drug(s) are important for demonstrating that the platform—which develops drugs by synthesizing the necessary molecules—works. And of course, there will be dilutions, but not in the next 1.5 years; the capital raised from the IPO will be sufficient until then. My plan, therefore, would be to build up my position over the next 5 years through a small savings plan. This limits the risk and allows you to automatically take advantage of price dips to buy more shares at lower prices.
•
1
•
imagem de perfil
@Raketentoni I ended up going for both right away. So far: $GENB +19.5% $KURA +14.2% It's going well! 😂😎
•
1
•
imagem de perfil
@Multibagger I'm also invested in $KURA; my new agent recommended it last night with a buy signal—so I bought in during the pre-market—and it's already up 10% today :) Yeah, things are going well.
•
1
•
imagem de perfil
Do you know why $KURA experienced such a slump in 2020? Was that also a failed study?
•
1
•
imagem de perfil
@Multibagger
Hey Chris! 🚀

Good question—you’ve shown an extremely keen eye for the historical chart! But we need to clearly distinguish between two different events here, because you’re probably mixing up the year and the cause a bit in your mind.

**1. The Crash in Spring 2020 (The COVID-19 Shock)**

The brutal crash in spring 2020 had absolutely nothing to do with a failed study. That was the classic, global COVID-19 market crash that dragged the entire sector down with it.
Kura’s stock fell 54.1% between January 2, 2020, and its low point on March 18, 2020 (from $14.04 to $6.45). However, since there was no company-specific issue, the stock price recovered rapidly and had already returned to its pre-crisis level by April 28, 2020.

**2. The Real Trial Shock (November 2021)**

If you’re thinking of a massive drop caused by a clinical trial, you’re most likely referring to **November 2021**.

At that time, the U.S. Food and Drug Administration (FDA) imposed a “partial clinical hold” on the Phase-1b trial (KOMET-001) of Kura’s most important drug, KO-539—now known as KOMZIFTI or ziftomenib.
The tragic reason for this hold: A patient in the trial had died from a fatal adverse event (Grade 5), known as “differentiation syndrome.”

Following this announcement, the stock price has since plummeted by about 40%. Incidentally, this very event is the reason why the drug now carries the FDA’s dangerous “black box” warning, which I mentioned earlier in the overview (point 8).

*Kura’s salvation:*
The FDA lifted the trial suspension in January 2022 after Kura, in close collaboration with the authorities, was able to present improved safety protocols and countermeasures for this syndrome.

So as you can see:
With biotech stocks, a single unforeseen patient report in clinical trials is enough to send the stock price plummeting without mercy. That’s exactly the kind of volatility that requires nerves of steel and your best venture capital! 😉

Best regards from Denmark

Your RaketenToni
•
1
•
imagem de perfil
@Raketentoni What first caught my attention was that the high from December 20—at €34—following the FDA’s hold led almost exactly to today’s price level. That means the stock is worth exactly as much today as it was back then after the FDA’s hold. I find this a very intriguing situation—and surprising—because back then, the price was €34 based on hopes for a drug that was put on hold, and now that drug is available, with others in the pipeline, yet the stock is back at the same low level as before.
•
1
•
imagem de perfil
@Multibagger I've added you to the waiting list :)
•
1
•
imagem de perfil
@Raketentoni Your " $KURA "? I'm already one step ahead on that front. It's made its way into my organic pie at Trading 212, and the first slices have already gone into it.
•
1
•
imagem de perfil
@Multibagger I’m still holding off on Kura Oncology because, although KOMZIFTI has been approved and is off to a solid start with quarterly revenue of $9.1 million, it has only been on the market for two full quarters.
The company continues to burn through a lot of cash, while the real driver of revenue growth depends on successful Phase 3 trials and expansion into earlier lines of treatment. I therefore want to wait and see if prescriptions and product revenue grow steadily over several quarters and if the high cash burn rate decreases.
The company is interesting, but I think its commercial development is still too early for me to get involved right now.
So, for now, I’m holding :)
•
1
•
imagem de perfil
Oh Toni, this comes at just the right time 👀 I'd love to put my new prompt through its paces 😂
I'm curious to hear your opinion/assessment—how do you rate the prompt? 😬

🔬 FULL SCOUT ANALYSIS: KURA ONCOLOGY, INC. ($KURA)

🧬 DNA-CHECK: $KURA
· SECTOR: BIOTECH-OVERRIDE
DNA RATING: K: 4/4 · E: 1.5/3 ✅

🏆 FUNNEL LOGIC (Talent Pyramid) 🏆 FUNNEL CLASSIFICATION: $KURA

STAGE 1 — RAW TALENT: Met. Commercial validation with KOMZIFTI (Q2/26: $9.1M in revenue, +57% QoQ) has begun.

LEVEL 2 — ESTABLISHED PRO: On the way there. Kura is currently demonstrating initial commercial traction but must still secure broad adoption in the frontline AML market (KOMET-017) in Phase 3.

CLASSIFICATION: On the way to Level 2. (Smooth transition from biotech developer to profitable oncology specialist).

—————————————————

🚀 FUTURE MOAT CHECK: $KURA

① TECHNOLOGICAL LEAD: Ziftomenib is a highly specific, orally available Menin inhibitor. It combines excellent bioavailability with no significant QTc prolongation (a structural advantage over Syndax’s Revumenib).

② EARLY-ADOPTER QUALITY: Over 93% payer coverage in the U.S. within 2 quarters of launch; 115 new patient starts in Q2/26.

③ SCALABILITY LOGIC: The U.S. sales structure can be scaled globally through the Kyowa-Kirin partnership without incurring massive in-house sales costs.

④ COMPETITIVE WINDOW: ~2-year lead together with Syndax. First-mover advantage is significant, as combination therapies in the AML field will define the standard of care for years to come.

MOAT SCORE: 3/4 → 🟡 SOLID FOUNDATIONS (strong precursor to candidate status).

————————————————
👔 FOUNDER & MANAGEMENT SCORE
• Founder-led: CEO Troy Wilson has led the company for the long term, but is not the founder → +0
• Track record: Wilson has built and scaled Avidity Bioscience, Wellspring Biosciences, and Ambrx → +1
• Capital Allocation: Excellent $330M global deal without massive shareholder dilution → +1
• Insider Purchases: CEO Wilson purchased ~$1.1M worth of shares on the open market on August 17, 2026 → +1
• Guidance transparency: Consistent execution of the launch roadmap → +1

FOUNDER SCORE: 4/5 → ✅ STRONG SIGNAL

—————————————————
💰 VALUATION & TAM SANITY CHECK • Market Cap: ~$812 million (at ~$9.50–$10.00 per share)
• Enterprise Value (EV): ~$300 million (adjusted for cash & holdings)

• TOP-DOWN TAM: $2.5–3.0 billion (NPM1-mutated and KMT2A-rearranged AML) [Grand View / Market Research 2025/26]

• BOTTOM-UP TAM: ~$1.8 billion (~20,000 addressable AML patients per year in the U.S./EU × ~$90k–$120k annual treatment cost)

• MANAGEMENT-TAM: $3.0+ billion (including expansion to solid tumors with darlifarnib)

• Cross-check: Bottom-up vs. top-down figures are in line (<2x deviation).

• Current market share: <1% (commercial launch underway).

• TAM quality: Already profitable today ($9.1M in Q2 product revenue).

——————————————————-

🎯 ASYMMETRY CHECK
1. Expectation Gap: The market prices Kura as a pure niche player in third-line AML (market cap ~$812M, close to cash on hand). Expansion into first-line treatment (Frontline KOMET-017) quintuples the addressable market.

2. Optionality: 3/5 (Darlifarnib in solid tumors, KO-7246 cardiometabolic).

3. Risk/Opportunity: • Downside: ~-30% to -40% (strong cushion provided by ~$519M in cash / ~$5.70 in cash per share). • Upside: +300% to +600% upon approval for front-line AML.

ASYMMETRY SCORE: 🟢 clearly asymmetric

——————————————————

🎲 OUTCOME PROBABILITIES ($KURA)
STEP 1 — BASE RATE: Commercial-phase biotech with a cash buffer. Low historical bankruptcy floor due to balance sheet strength.

STEP 2 — ADJUSTMENT:
• + Cash runway >36 months
• + Commercial validation ($9.1M revenue)
• + CEO insider purchase in August 2026
• - Single point of failure (SPOF) development risk regarding Frontline-AML trial data (KOMET-017)

STEP 3 — OUTCOME DISTRIBUTION:
🔴 TOTAL LOSS (Bankruptcy/Delisting, ~0–0.3x) 10%
🟠 DISAPPOINTMENT (Phase 3 fails, 0.3–1x) 20%
⚪ MARKET RETURN (Niche player without Frontline, 1–2x) 30%
🟢 MULTIBAGGER (2–10x, Frontline AML success) 30%
💎 TENBAGGER+ (≥10x, established oncology platform) 10%

—————————————————
🔍 TAM REALITY CHECK FOR TENBAGGER SCENARIO
Question: Market cap at 10x = ~$8.1 billion. Implied bottom-up TAM share = 8.1B / multiplier ~ $1.5B revenue = ~80% market share.

VERDICT: Borderline to unrealistic WITHOUT pipeline expansion (Darlifarnib/solid tumors). The tenbagger scenario absolutely requires the success of the solid tumor pipeline.

⚠ RISK FACTORS
• Dilution risk: Very low over the next 24–36 months (cash run-of-cash until 2028+).
• Competitive risk: Syndax (Revumenib) is a direct competitor in the meningioma segment.
• Story Risk: Low. Real numbers are available ($9.1M Q2 product revenue).
• Liquidity Check: Average daily volume ~$3M–$5M. Sufficient liquidity.

🕵 FRAUD/PROMOTION RED FLAGS CHECK 0 red flags identified. Financial statements audited by top accounting firms; reputable institutions on board (BlackRock, Vanguard).

STATUS: 🟢 CLEAN
—————————————————-

😈 HYPE BIAS CHECK & ☠ KILLER THESIS

1. Why might I be wrong? Menin inhibitors could exhibit unexpected toxicities in frontline combinations, or Syndax could secure the lion’s share of the market.

2. Contradictory data point: Ziftomenib has not yet disclosed detailed MRD negativity rates for its approved indication.

3. Reference class: Of 10 biotech companies with Phase 3 combination trials in their first year of commercial launch, ~3–4 achieve a sustainable breakthrough to become billion-dollar oncology companies.

☠ KILLER THESIS: “In the Phase 3 KOMET-017 study, ziftomenib demonstrates superiority over standard therapy in frontline AML without prohibitive toxicity.” Probability of failure: Low to medium.

—————————————————-
🔥 CATALYST SCORE & ⏳ RUNWAY GUARDRAIL
☑ Phase 1b/2 data updates for darlifarnib (2H 2026)
☑ QoQ revenue growth for KOMZIFTI (Q3 & Q4 2026)

CATALYST-SCORE: 2/5 (🟡 One or two triggers present; main catalyst—KOMET-017 Phase 3—still some way off)

⏳ RUNWAY VS. CATALYST CHECK: Cash runway: ~40+ months vs. time to main catalyst: ~24 months. Buffer: >16 months → ✅ Guardrail passed.

⚖ NULL HYPOTHESIS & BENCHMARK COMPARISON Null hypothesis passed: Kura has a financially sound commercial phase with a superior toxicity profile in the area of Menin inhibition.

——————————————————
🏁 SCOUT VERDICT

RATING: STRONG WATCH
SIZING RECOMMENDATION: 0.5% – 1.5% (watch position)

DIP-BUYING LIMIT: $8.20 / €7.50 (Close to net cash value per share)

SCOUT SCORE: 8/10
· Key drivers: KOMZIFTI is off to a strong commercial start, while its enterprise value is extremely well-protected on the downside by its massive cash position ($519M+).

UPGRADE TRIGGER: → KOMZIFTI quarterly revenue rises to >$12M in Q3/2026 → Initial Phase 1b/2 combination data for darlifarnib in solid tumors show response rates >30%

DOWNGRADE TRIGGERS: → KOMZIFTI revenue stagnates below $10M for two consecutive quarters → Abrupt termination of the KOMET-017 Phase 3 trial due to signs of toxicity

OBSERVATION HORIZON: Through Q4 2026 earnings (March 2027)

———————————————————

📊 PREDICTION TRACKING: $KURA
• Expected revenue growth (12M): +100%+ (KOMZIFTI scaling from ~$35M p.a. run rate to ~$80M+)
• Expected cash runway status in 12M: >30 months secured
• Expected market share development: Establishment as the standard menin inhibitor in relapsed/refractory NPM1-AML. Milestone: Q3 2026 earnings (November 2026).
•
1
•
imagem de perfil
@Aktienhauptmeister The prompt needs to be a little more structured.
I actually preferred the old version in terms of writing style. This one's too technical for me :)
It's supposed to be funny, at least here.
Are you on Discord? If so, send me a message.
•
2
•
imagem de perfil
@Raketentoni This is actually the first complete analysis using the new prompt 😂 So far, my focus has been more on the technical and fundamental aspects. I just threw everything together at first, didn’t really think much of it, and this is what came out 😂 Now I’m starting to make the first additions and adjustments.
•
2
•
imagem de perfil
$KURA Top Recommendation! THANK YOU!
•
1
•
imagem de perfil
@G_Capital I'd love to
•
1
•
imagem de perfil
I've invested a small amount in my "Health Pie" through Trading 212. I'm very curious to see how it turns out (also in the interest of the patients involved).
•
1
•
imagem de perfil
@Novius Welcome aboard
•
1
•
Participar na conversa