1Semana·

France's Debt Trap: How Paris Is Putting Pressure on the Euro—and How Gold and Bitcoin Could Benefit

The Maastricht Treaty requires eurozone countries to maintain an annual budget deficit below 3 percent and public debt below 60 percent of GDP. At the height of the euro crisis in 2012, France and Germany were still on par at around 90 percent. Since then, Germany has moved closer to meeting the Maastricht criteria, with its debt now at about 64 percent, while France’s debt has risen to about 117 percent—and this during a period of historically low interest rates. That is why rising long-term interest rates are so problematic for Paris: if existing debt is refinanced at higher rates, the interest burden will skyrocket.


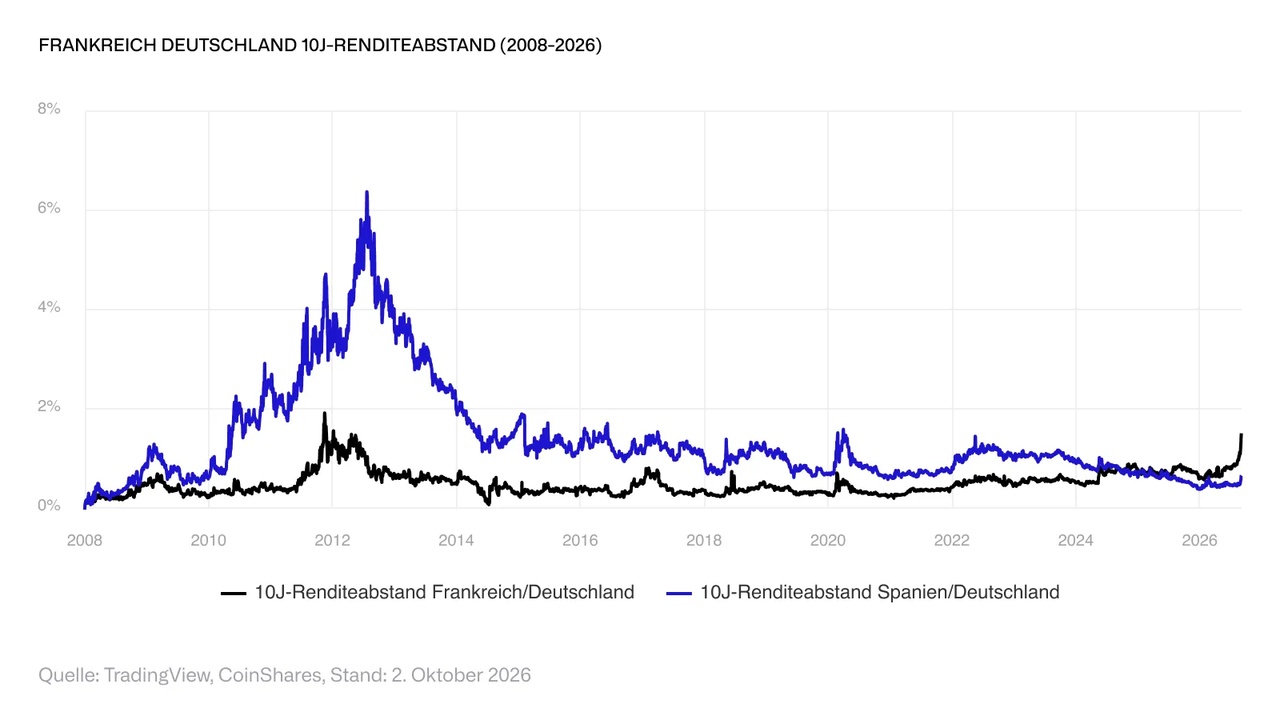
Politicians are underestimating the problem: Some candidates are bringing up the possibility of a debt haircut, as was done in Greece before the bailout package and the IMF intervention. The yield spread between French and German government bonds is already widening significantly, while former crisis-hit countries like Spain are not under pressure to the same extent. This is a warning sign for the eurozone; after all, France is one of its largest economies. We can expect downward pressure on the euro’s value and, consequently, additional inflation. This could affect non-government stores of value such as $GOLD and $BTC (+0,93%) could benefit from this.


You can invest in Bitcoin through the following platform: $BITC (+0,58%)
attachment
4
2 Comentários

imagem de perfil
And how do you think the U.S., with its rising national debt, fits into this picture? What impact does this have on gold, inflation in Europe, and the euro?
••
imagem de perfil
This highlights the underlying structural weakness of the eurozone. It stems in particular from the lack of a common fiscal policy and the widespread disregard for the Maastricht criteria, which have so far proven largely nonbinding. This suggests that another euro crisis could be only a matter of time. The trend in CDS spreads on French government bonds indicates that it could occur sooner rather than later.

The U.S. faces some similar challenges but benefits from having established the U.S. dollar as the world’s reserve currency. While this status is gradually eroding—which, consequently, supports demand for non-government stores of value such as gold and Bitcoin— China’s recent gold purchases are a clear example of this trend.

Should the euro come under pressure again—and setting aside Japan, where the situation is arguably even more difficult—neither the U.S. dollar nor the yen would necessarily be a compelling alternative. This could further increase demand for gold and Bitcoin as alternative stores of value.
•
1
•
Participar na conversa