

Following PepsiCo $PEP (+1,97%) versus McDonald’s $MCD (+0,19%) and Nu $NU (-1,99%) versus SoFi $SOFI (-3,08%) , today we’re taking a look at two companies without whose technology a lot of data in data centers would be stuck in a traffic jam for quite a while.
Today we have our first requested comparison of @Tenbagger-Capital
Lumentum $LITE (-3,84%) and Applied Optoelectronics $AAOI (-8,22%) both supply optical components for faster connections. Both are benefiting from the expansion of AI.
Nevertheless, they differ significantly in how much of that is already trickling down to shareholders today.
If you have a request for a comparison, feel free to write it in the comments—just one condition: both companies should be from the same sector and, ideally, be competitors :)
Quick note: As of October 16, 2026. Common price basis (U.S. close on October 15): Lumentum $869.54, AAOI $83.73. General comparison independent of any personal portfolio strategy. All scenarios are based on my own assumptions; these are not guaranteed price targets.
How the Companies Came to Be
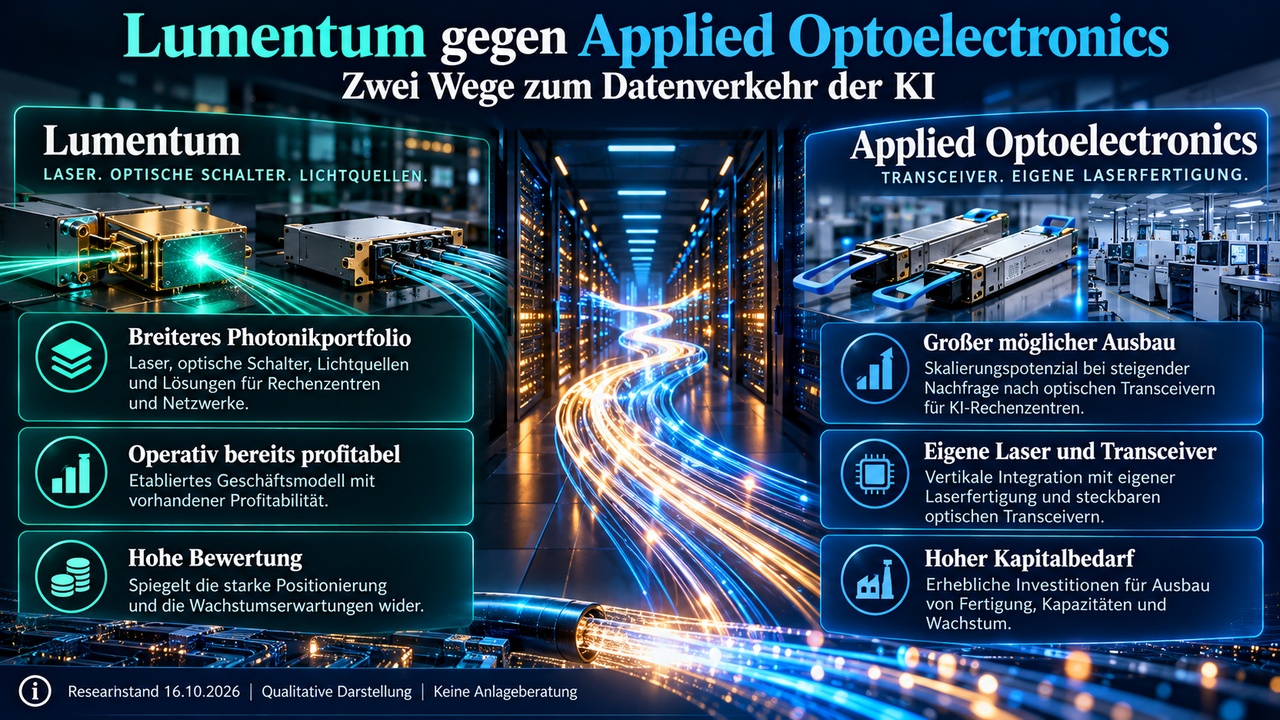
Lumentum was formed in 2015 through a spin-off from JDS Uniphase. Over the years, other specialists joined the company, including Oclaro, NeoPhotonics, and Cloud Light. Today, its product portfolio includes laser chips, optical components, modules, and optical switches. This gives the company multiple opportunities to profit from the expansion of data communications.
AAOI was founded in Houston as early as 1997 and has been listed on the Nasdaq since 2013. The company produces optical transmitter and receiver modules and manufactures its own lasers. It also supplies cable network operators through its CATV business. In the last quarter, approximately 42 percent of revenue came from this segment. AAOI is therefore more than just an AI play, even though the market is currently paying particular attention to high-speed data center modules.
What I Like Better About Lumentum
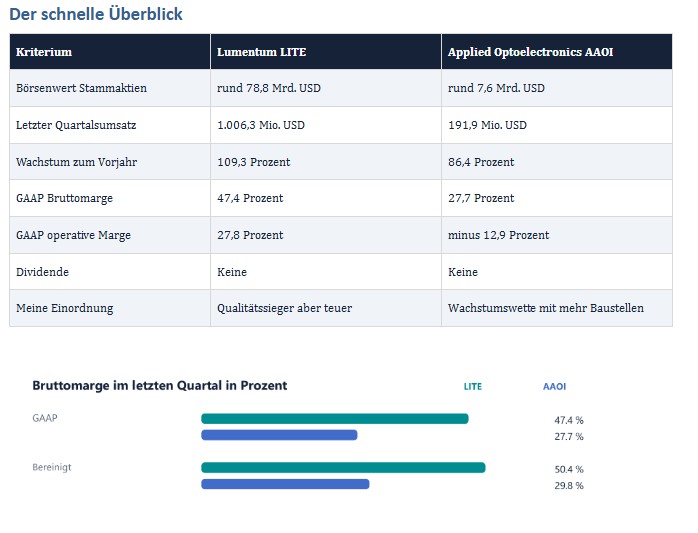
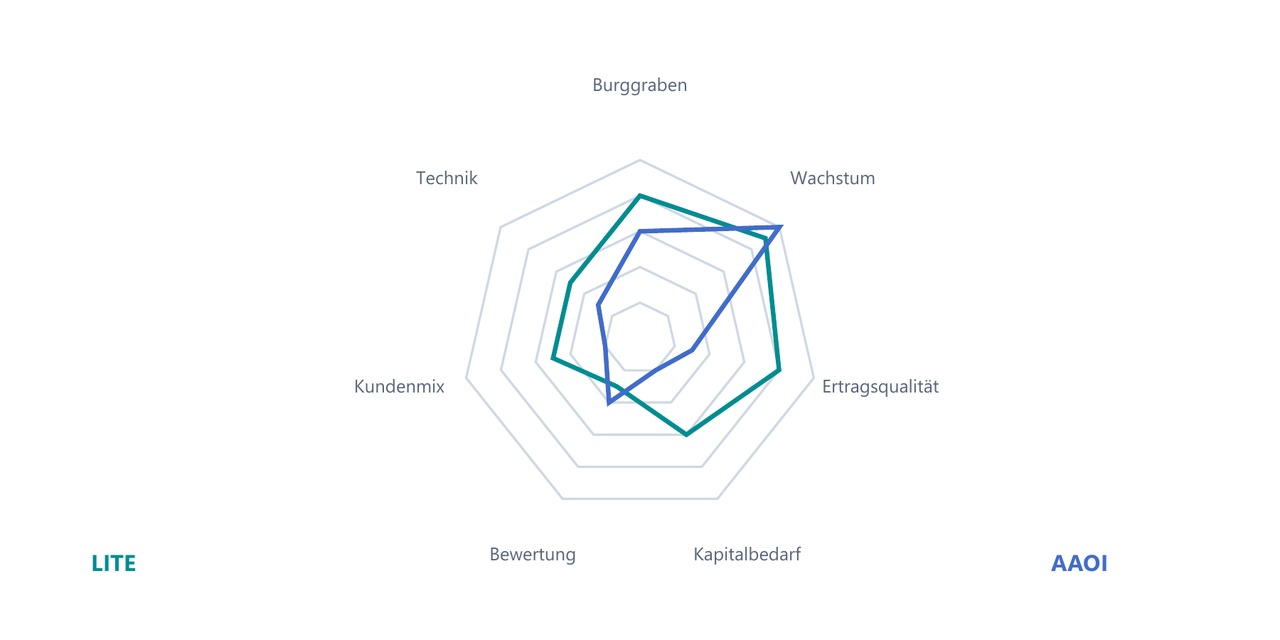
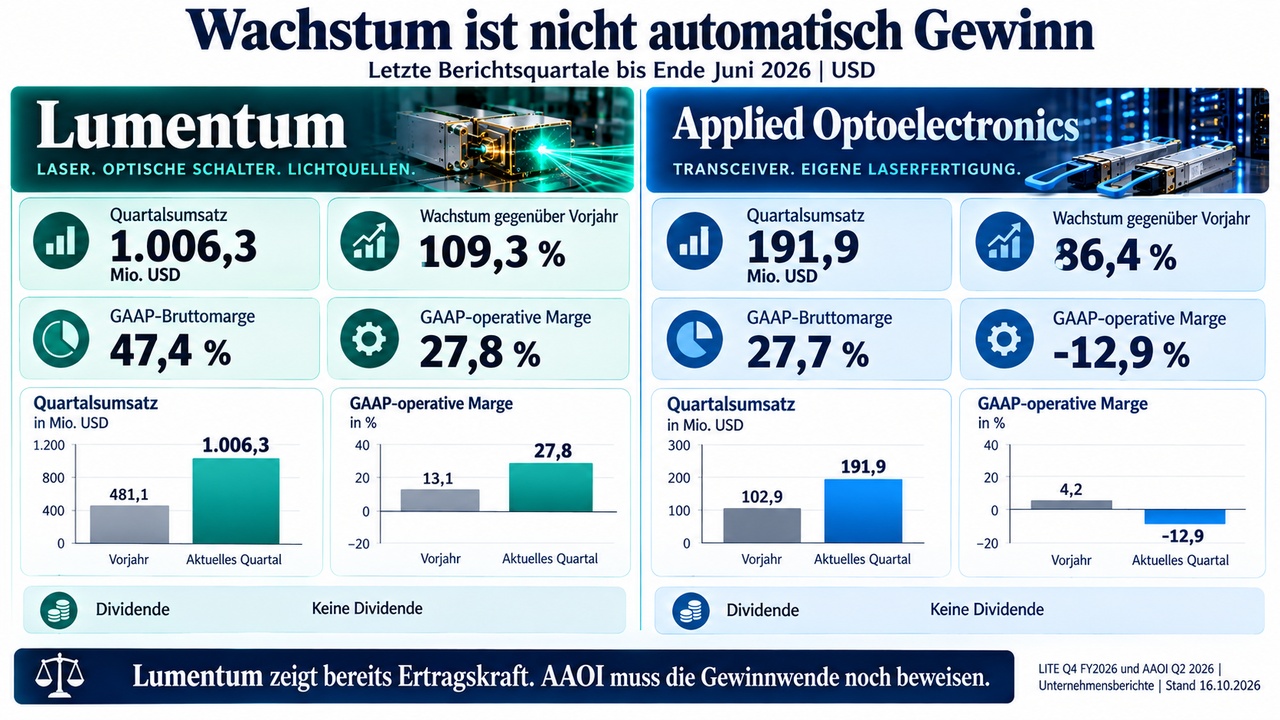
Lumentum has already demonstrated that high demand translates into strong operating profits. With quarterly revenue exceeding $1 billion, the GAAP operating margin stood at 27.8 percent. AAOI is also growing strongly but is still posting operating losses.
For me, that’s the most important difference: With Lumentum, I don’t have to pin my hopes as much on a turnaround in profitability that has yet to materialize.
Added to this is the broader technical portfolio. If the design of a data center changes, Lumentum can remain involved through specialized lasers, external light sources, or optical switches, for example.
AAOI also has an advantage with its own laser production. However, its financial success currently depends more heavily on ramping up new transceiver capacity quickly and with reasonable margins.
Lumentum’s massive reported annual loss warrants an explanation.
It was primarily caused by a non-cash charge resulting from the conversion of convertible bonds. This was not a billion-dollar outflow from day-to-day operations.
The transaction is nonetheless relevant to shareholders because it alters the capital structure and dilutes equity. Simply dismissing it as a “one-time item—no big deal” would be too convenient for me.
What’s particularly exciting about AAOI
is that AAOI is starting from a significantly smaller base.
If the expansion for 800G and 1.6T modules succeeds, the company can grow at a higher rate than its larger competitor. In-house lasers can further improve costs and delivery capabilities.
In a best-case scenario, this would provide significant revenue and margin leverage. That’s where AAOI could very well come out on top in this head-to-head competition.
I wouldn’t, therefore, label AAOI as a bad company.
The question is how much of the future capacity will be used profitably and how many additional shares will be issued by then. After all, capacity listed on a presentation slide doesn’t pay the bills.
Especially with an expansion like this, one must distinguish between revenue growth and earnings per share growth.
Where Lumentum still doesn’t convince me
The company is good, but the market has known that for a long time. A market capitalization of nearly $79 billion contrasts with about $300 million in free cash flow from the last fiscal year.
Of course, this cash flow is expected to grow significantly. Nevertheless, the gap shows just how much of the future is already being priced in today. Even a good company can disappoint on the stock market if it delivers only “very good” results rather than “sensational” ones.
Added to this are new factories, bottlenecks, and a growing share of large customers.
The largest disclosed end customer most recently accounted for 26.6 percent of annual revenue, compared to 15.4 percent in the previous year. Long-term capacity utilization forecasts are positive. However, they are no substitute for addressing the question of how binding orders actually are and what prices will ultimately be achieved.
What makes me significantly more cautious about AAOI
The expansion is initially a cash drain. In the first half of the year, operating cash outflow totaled around $74 million.
Together with plant and equipment, advance payments for equipment, and land purchases—according to this broad definition of investment—approximately $707 million was spent. Part of this is intended to generate revenue later on. For now, however, it represents a real financing need.
The capital increase completed on October 5 raised a net total of approximately $588 million and improves the company’s financial flexibility. At the same time, about 5.7 million new shares were issued.
Both of the following are true: The financing situation has improved, and the existing shareholders’ stake has decreased. Whether another capital raise will be necessary depends primarily on the actual expansion costs and future cash inflows.
A completed program is no guarantee that another one will never follow.
The customer base is particularly important to me.
Three customers accounted for a combined 92 percent of revenue. In addition, approximately 67 percent of receivables were attributable to Digicomm, a distributor in the cable network business. This isn’t automatically a payment issue, but it is a significant concentration. A distributor can serve many end customers and still remain a single major payer for the manufacturer.
AI helps both, but the technology may change
Both companies benefit from the fact that data centers need to process more data. The risk isn’t so much that AI will replace the laser. What’s more intriguing is whether new architectures will shift the value chain.
As optical connections move closer to the chips, the requirements for traditional pluggable modules will change.
At Lumentum, , I like that lasers and external light sources can still be used even in new architectures.
AAOI also has opportunities through its laser manufacturing, but it must first translate this into lucrative products on a larger scale. Lumentum’s recent demonstration with Astera Labs and Corning is interesting. However, a demonstration does not yet equate to mass-production business with a steady profit contribution.
I wouldn’t factor in an allegedly certain tailwind from an immediate ban on Chinese transceivers for any stock. There are political initiatives and reports about potential FCC rules.
However, the reviewed official Senate bill pertains to specific procurements and includes long transition periods. I do not view this as a guaranteed source of additional revenue.
What I expect for the coming years
For Lumentum, in my base case scenario, I expect continued strong growth and a healthy operating margin, but also high capital expenditures and increased competition down the road.
The company has the potential to grow significantly larger. I simply don’t expect today’s scarcity-driven prices and exceptional growth rates to last forever.
With AAOI, I see the potential for a bigger leap, but also a wider range of possible outcomes. In the best-case scenario, new capacity comes online smoothly, 1.6T gains traction, and higher revenue translates into higher earnings per share. In the worst-case scenario, new facilities come online too late, capacity utilization lags behind, or additional capital requirements dilute returns for existing shareholders. Here, the path to profit is at least as important as the potential target.
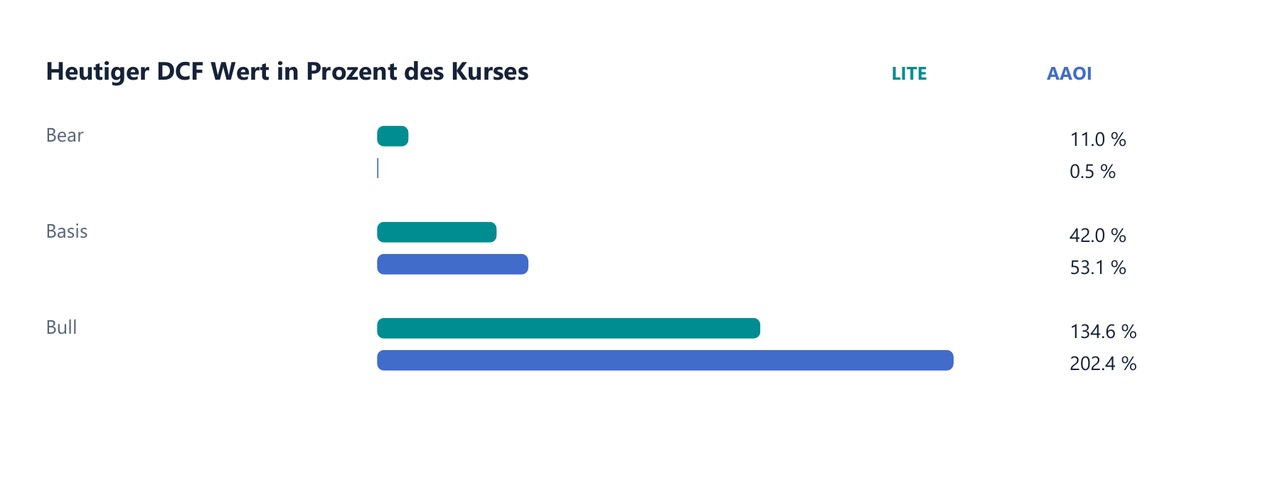
My conservative cash flow model currently yields, in the base case, around $365 for Lumentum and $44 for AAOI.
For both companies, this is below the current market price.
That doesn’t mean the market has to fall to those levels tomorrow. It means that a great deal of growth is already priced in, and my conservative scenario does not offer a clear margin of safety.
The range is wide: In the bear case, my model puts Lumentum at about $96.
The extreme AAOI stress case comes in at less than one dollar, because expansion costs, combined with too-low future margins, would virtually erode the entire shareholder value.
This is not a prediction of insolvency. In the bull case, the figures come to approximately $1,170 and $169, respectively.
This scenario assumes exceptionally successful expansion and high future margins. Such possibilities are appealing, but I wouldn’t present them as the standard outcome.
A potential entry point does not constitute an obligation to buy
On the chart, Lumentum is relatively stronger. The price is still above the long-term daily moving average but has broken below the shorter-term trend line.
AAOI is trading below both the 50-day and 200-day moving averages.
For both, I don’t see a confirmed bottom at the moment. A red chart doesn’t turn green just because the stock was more expensive last week.
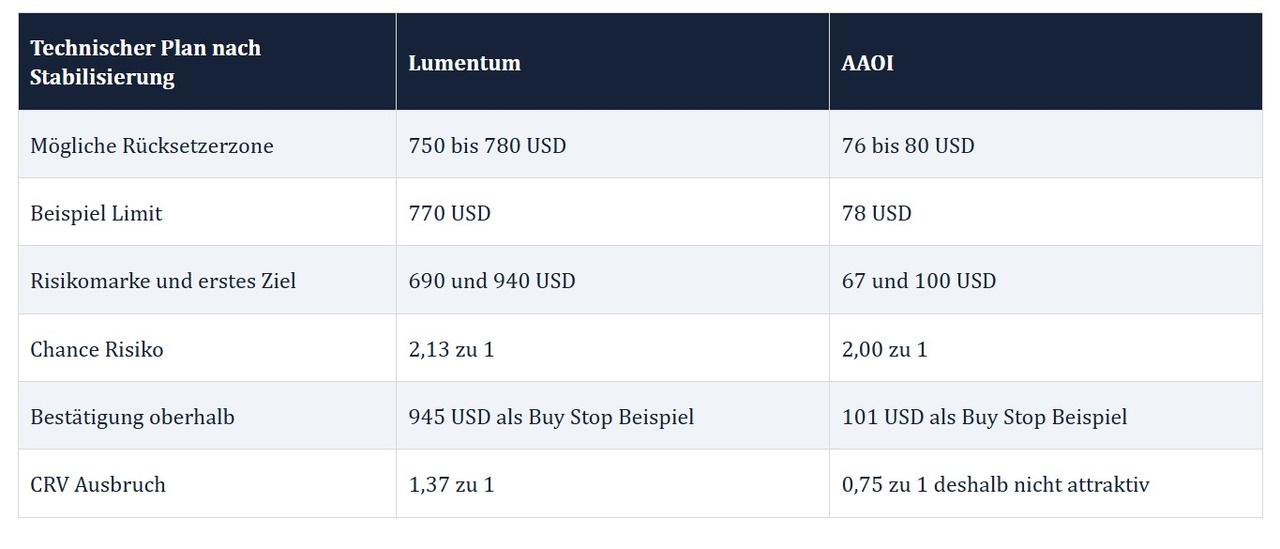
These levels are trading plans in case of stabilization; they are not a call to place blind orders immediately. In a pullback trade, I would assess the first target zones to determine whether to reduce my position or let the recovery continue. For a long-term investment, I would additionally require a reasonable valuation and stronger operational evidence.
A technical stop may be executed significantly worse in the event of a price gap.
A normal buy stop does not wait for a confirmed closing price.
Anyone who wants this confirmation will have to reassess the situation afterward. Limit orders and breakout orders are alternative approaches; an entry OCO order is only an option if the broker supports this order type. The upcoming earnings report on November 5, in particular, could lead to significant price swings.
My conclusion on this showdown
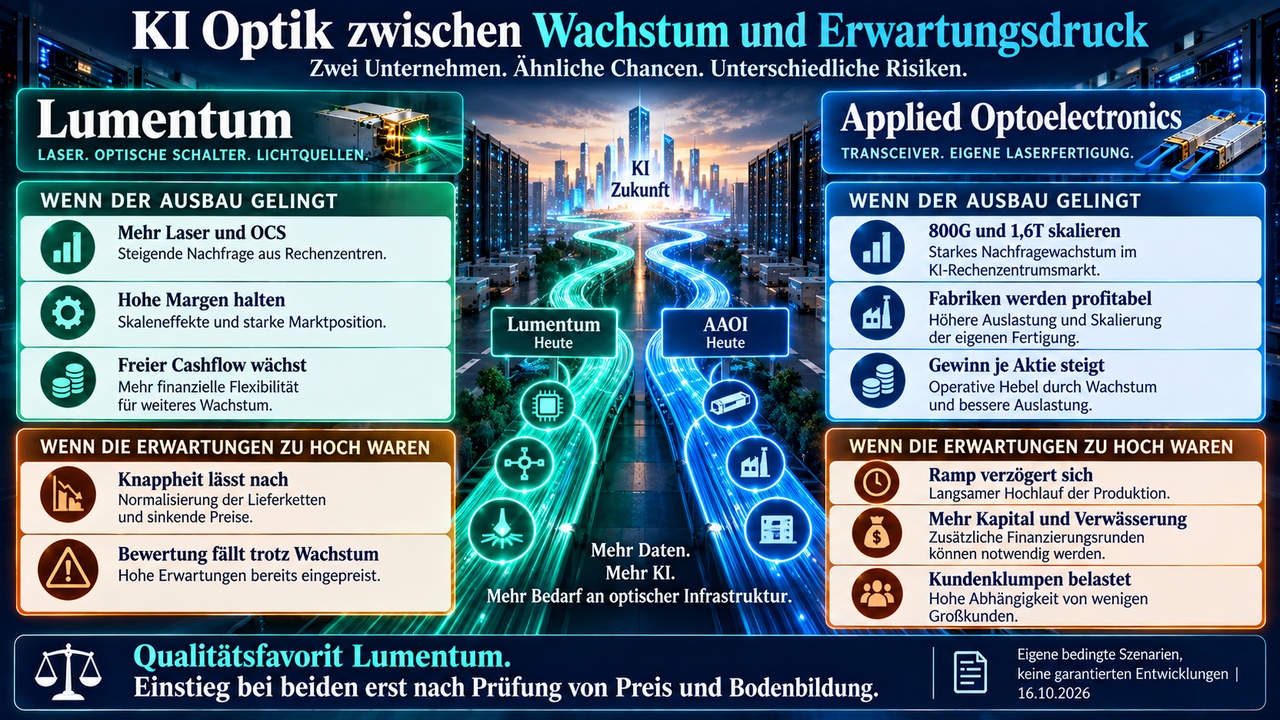
If I were to choose, independently of any portfolio strategy, I’d have to choose one of the two companies , it would be Lumentum.
Its operational profitability, broader product portfolio, and stronger cash flow base convince me more.
If AAOI successfully expands, it could offer greater upside potential.
However, this requires putting up with significantly more uncertainty regarding margins, financing, and customer dependence.
For an entry today, my verdict on both is: wait a little longer.
Lumentum remains my preferred stock to watch.
With AAOI, before making a long-term purchase, I’d first like to see not only new factories and new shares being added, but also a sustainable increase in free cash flow per share.
The AI boom is interesting enough on its own. I don’t need to chase every valuation associated with it.
The strongest counterargument to my caution is a prolonged shortage leading to much higher future profits.
In that case, the market could be right, and my conservative estimate might be too low. That’s exactly why I’m looking forward to both companies’ next earnings reports on November 5. Solid new evidence would change my assessment; another high analyst target alone wouldn’t be enough.
What do you think: would you rather go with Lumentum’s already proven earnings power or the bigger catch-up bet on AAOI?
Feel free to share your arguments in the comments, along with two other stocks for an upcoming showdown.
Ideally, they should be from the same sector and have comparable business models.
Constructive counterarguments are expressly welcome.
Greetings from Denmark
Raketentoni
Sources:
S1 Lumentum Q4 and FY2026 Earnings Report, August 11
S2 Lumentum FY2026 Annual Report, including Form 10-K
S3 AAOI Q2 2026 Results and GAAP-to-Non-GAAP Reconciliation
S4 AAOI Form 10-Q as of June 30, 2026
S5 AAOI 2025 Annual Report (Form 10-K)
S6 AAOI Completion of Capital Increase, October 5
S7 NVIDIA Strategic Partnership with Lumentum, March 2
S8 Lumentum, Astera Labs, and Corning OCP Demonstration, October 12
S9 U.S. Senate Bill S 5548 Introduced, September 24
S10 Lumentum Stock Price and Valuation Data
S11 AAOI Stock Price and Valuation Data
S15 Lumentum Investor Relations Calendar
S16 AAOI Investor Relations Calendar
S17 AAOI Company History
and, of course, all the others :)


