Hello everyone, yesterday's company presentation seems to have inspired you with its triple-digit profit growth. There were even a few comments from users I didn't know. That made me happy, as did the many👍 of course.
Thank you, my dears.
So in the morning I thought about what would be an exciting company for the dear community. And suddenly I remembered the exciting post from dear @Anderle came to mind again.
And so I had already found a company with triple-digit profit growth. My dear @Anderle thanks for the inspiration.
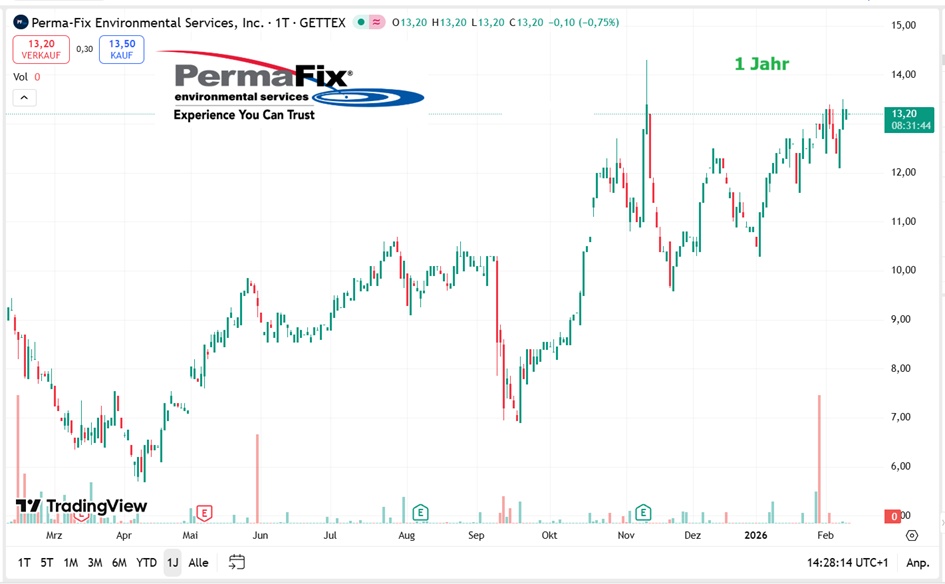
I would like to start right at the beginning. The company is a little volatile due to its low market capitalization, as can be seen from the chart.
Therefore, it may not be the right choice for every investor. Due to the specialization in a very sensitive area, I see a moat here and therefore potential.
What is your opinion here?
I look forward to many comments
Perma-Fix links management remuneration for 2026 to performance targets
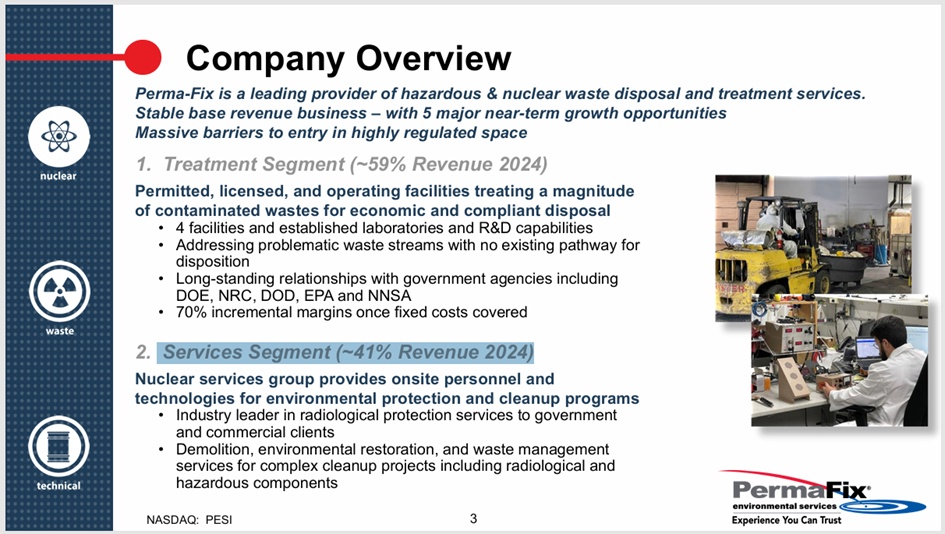
Perma-Fix Environmental Services, Inc. is a nuclear services company, which provides nuclear and mixed waste management services. The company operates in two segments: Treatment and Services. The Treatment segment includes the treatment, processing and disposal of nuclear, low-level radioactive, mixed, hazardous and non-hazardous waste, as well as research and development (R&D) activities to identify, develop and implement innovative waste processing techniques for problematic waste streams. The Services segment includes technical services, nuclear services and the company's own calibration and maintenance laboratory, which takes care of the maintenance, calibration and procurement of instruments for health physics, industrial hygiene (IH) and customized nuclear, environmental and occupational safety (NEOSH) instruments. The company's technical services provide professional radiological measurements and site surveys of large government and commercial facilities using advanced methods, technologies and techniques.
Number of employees: 299
Perma-Fix share: capacity tripled
Perma-Fix Environmental Services has been able to process three times more liquid mixed waste since the beginning of the year. The expanded permit strengthens its position for Hanford Site contracts and improves the market environment.
08.02.2026, 15:08
Briefly summarized:
- Permit triples processing capacity at Richland
- Focus on waste streams from the state-owned Hanford Site
- Portfolio expanded to include macroencapsulation
- Annual results expected for mid-March 2026
Perma-Fix Environmental Services is on the verge of an operational turnaround. Since January 2026, a new permit at the Richland, Washington, site has enabled the processing of three times more liquid mixed waste than before. This raises the question of how efficiently the company can use the existing infrastructure for these significantly higher volumes.
Focus on Richland and Hanford
The key growth driver is currently the cooperation with the US Department of Energy. The processing of waste from the Hanford Site forms the backbone of capacity utilization at Richland. Perma-Fix can now handle much larger volumes of waste thanks to the significant expansion of official approvals.
The company is also expanding its portfolio to include macro-encapsulation. This step improves its competitive position in future tenders, as a wider range of waste types is covered. How quickly can this new potential be translated into real margin growth?
Industry trends as catalysts
The market environment is currently playing into the company's hands. The renaissance of nuclear energy and stricter environmental regulations are increasing the need for specialized remediation. In particular, the destruction of "perpetual chemicals" (PFAS) using new, incineration-free technologies is becoming increasingly important. Proprietary processes, which have a lower environmental impact and could therefore secure the contract for new service agreements, are seen as a potential price driver.
Long-term contracts, for example with the US Navy, ensure a calculable base load in the radiological services business. The dismantling of old nuclear facilities also offers a steady pipeline of projects.
The publication of the annual results in mid-March 2026 marks the next important date for investors. The financial report will provide information on the extent to which the backlog of orders has been reduced and what operational benefits the extended Richland license has already left behind in the figures.
Perma-Fix Aktie: Kapazität verdreifacht - Stock World
Distribution of turnover by business division 2024
Treatment USD 34.95 million
Services USD 24.16 million
Geographical distribution of sales 2024
United States USD 56.66 million
Germany 734,000
United Kingdom 553,000
Canada 513,000
Mexico 394,000
Slovenia 181,000
Italy 77,000
International growth
Italy - Joint Research Center (JRC) contract
- 50 million euro contract over 7 years joint venture with 50/50 split
- Contract progressing rapidly, first waste delivery at the end of 2026
Other international initiatives
- Supply of resins from Slovenia for testing for a long-term agreement
- Ongoing customer discussions in Germany to establish a joint venture to increase deliveries up to 300 tons per year
- Recent orders from Mexico and Canada included over USD 7 million in revenue, which is expected to continue in 2026 through ongoing procurements
Perma-Fix exceeds profit forecasts for Q3 2025 - share price rises sharply
Published on 10.11.2025, 16:43
I nvestor Presentation: December 2025
*PESI+New+Investor+Presentation+-+December+2025+-+FINAL.pdf
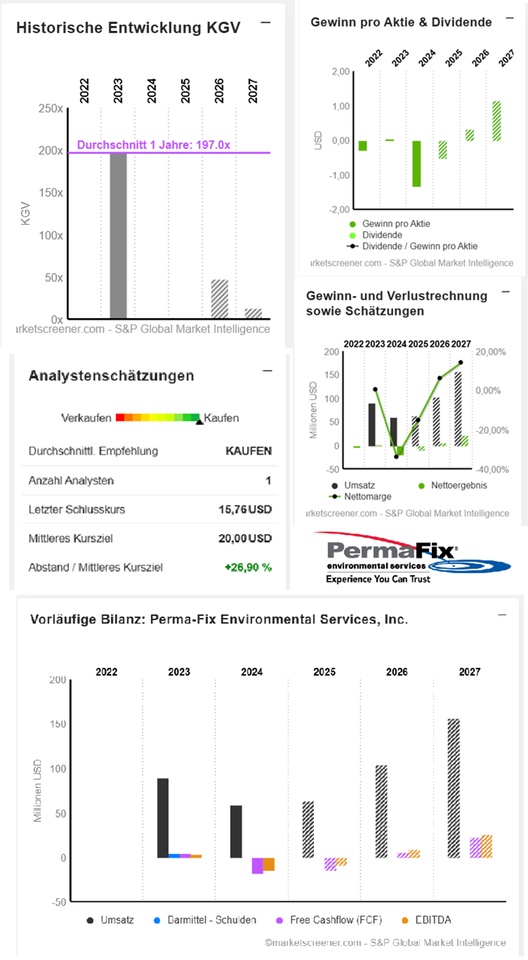
USD in millions
Estimates
Year Turnover Change
2024 59,12 -34,12 %
2025 63,7 7,75 %
2026 103,5 62,48 %
2027 156,9 51,59 %
Year EBIT Change
2024 -15,68 -2.174,34 %
2025 -10,3 34,32 %
2026 6 158,25 %
2027 21,8 263,33 %
Year Net result Change
2024 -19,98 -4.219,38 %
2025 -9,6 51,95 %
2026 6,4 166,67 %
2027 22,2 246,87 %
Year CAPEX Free cash flow change
2024 3,405 -17,55 -495,83 %
2025 4,6 -14 20,23 %
2026 4,5 4,9 135 %
2027 3,3 22,7 363,27 %
Year EBIT margin EBITDA margin
2024 -26,53 % -23,26 %
2025 -16,17 % -12,87 %
2026 5,8 % 9,08 %
2027 13,89 % 16,63 %
Year P/E ratio PEG earnings per share
2023 197x -2x 0.04
2024 -8.32X 0x -1.33
2025 -30.3x 0.5x -0.52
2026 47.8x -0x 0.33
2027 13.7x 0x 1.15
Market value 291.8
Number of shares (in thousands) 18,518
Date of publication 13.03.2025
My dears, I am thrilled by this almost tripling of the net result. Which is not only achieved by this very good increase in margins, but also by double-digit sales growth.
💰 3rd EV/EBITDA from 2026 suddenly becomes attractive
The picture changes from 2026:
- 2026: 11.2x EV/EBITDA
- 2027: 11.2x → 8-10x depending on estimate (starting from 26.1m EBITDA)
My dears, that would be cheap to fairly valued.
For a company in the nuclear waste sector, an EV/EBITDA of 10-12x would be would be absolutely fair to favorableif:
margins become sustainable
the order situation remains stable
government spending in the nuclear sector continues to rise
🧨 4th P/E ratio is unusable - until 2027
The P/E ratio series is a prime example of why you shouldn't look at the P/E ratio in turnaround cases. should not look at the P/E ratio:
- 2024: -8.32x
- 2025: -30.3x
- 2026: 47.8x
- 2027: 13.7x
Only in 2027 does the P/E ratio of 13.7x make any sense at all - and that would then be attractiveif the estimates come true.
🧭 6. overall assessment: The multiples look favorable - if the turnaround is real
Positive
- EV/Sales falls sharply → Valuation becomes more favorable
- Realistic, attractive EV/EBITDA multiples emerge from 2026/27 onwards
- The sector has a structural tailwind (nuclear, DOE projects, infrastructure)
🧩 6. overall picture: what does this mean for the share?
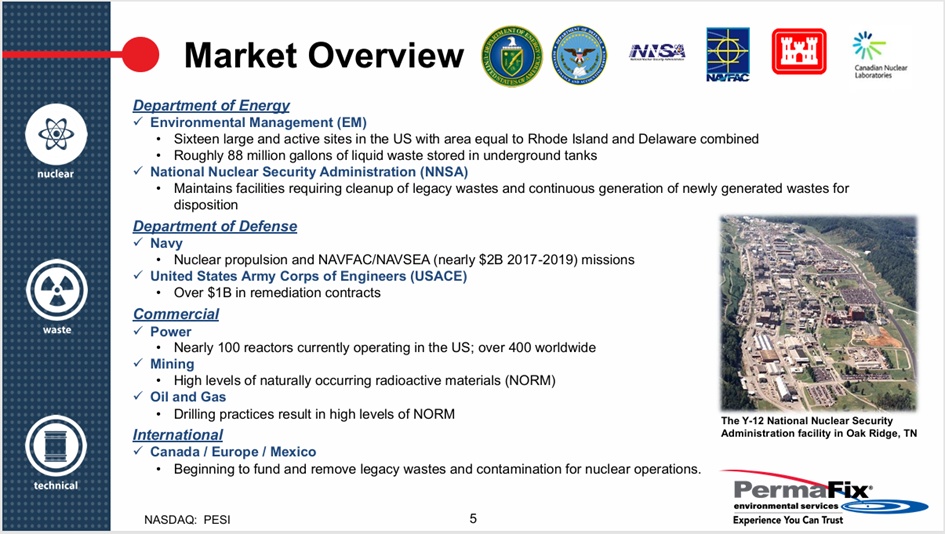
Perma-Fix is not a normal small capbut a DOE contractor with nuclear specialization.
The order situation is very strong because:
- Sales estimates are exploding
- margins will increase massively from 2026
- the business model is clearly DOE-driven
- the website confirms the full nuclear/radiology focus
🏛️ What is the DOE?
DOE stands for the U.S. Department of Energywhich is the US Department of Energy.
It is one of the most powerful and well-funded authorities in the USA, responsible for:
- nuclear energy
- nuclear weapons programs
- decommissioning of old nuclear facilities
- radioactive waste disposal
- Research & development in the energy sector
Especially the area of Nuclear Cleanup is gigantic: The DOE manages the world's largest nuclear legacy - remnants from the Manhattan Project, the Cold War and various research programs.
My dears, DOE only allows a few specialized companies. It's a moat for perma-fix
@Klein-Anleger
@Get_Rich_or_Die_Tryin
@Dividendenopi