Good morning, my dears,
Yesterday Juan was deep in history and brought us a 160-year-old company.
Even though Siemens Energy is not that old. I see parallels in the transformation, that fits well, after all, both companies work together.
Just as there were difficult years at Siemens Energy, and everyone should know the rest of the story.
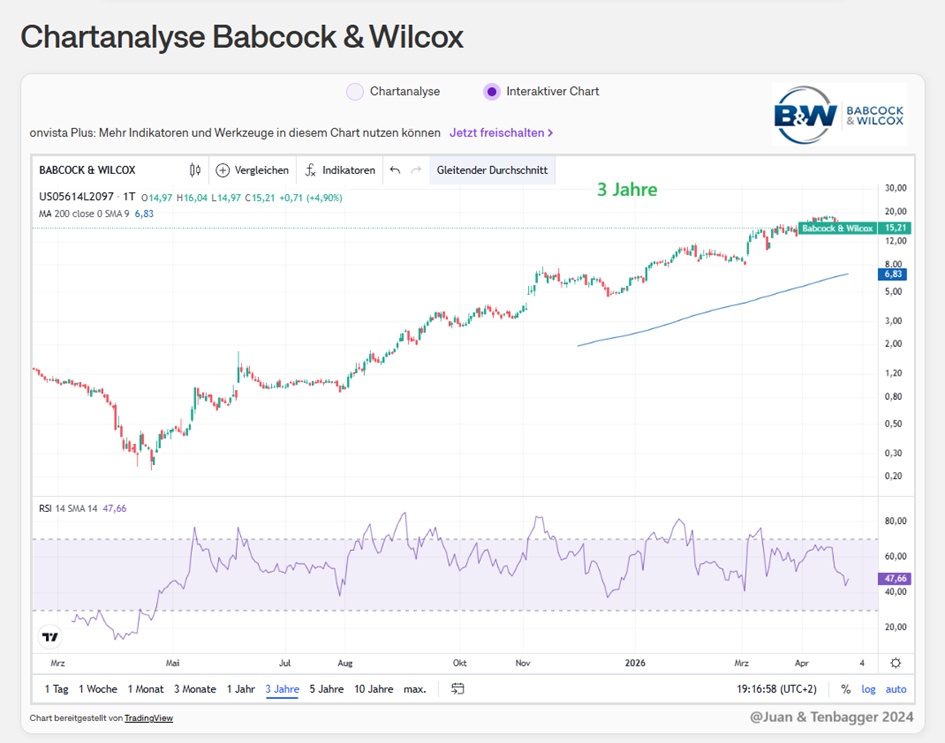
To Babcock & Wilcox $BW (-8,49%) I had already posted a report on Babcock & Wilcox last year. And somehow I'm annoyed that I didn't buy after that. Just as some people will be annoyed not to have bought or even sold Siemens Energy.
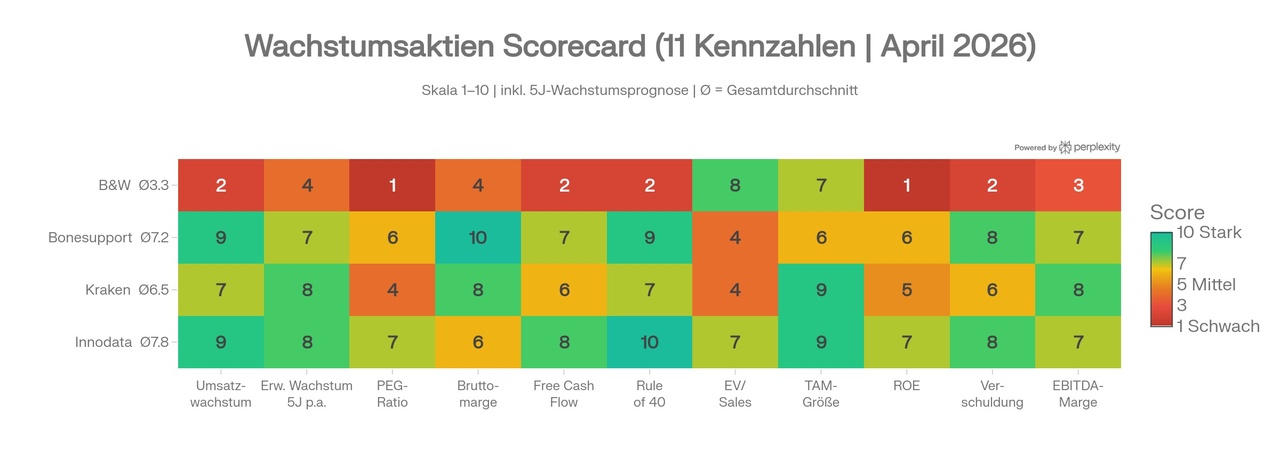
Despite the real run, I still don't see B&W as too expensive with a forward P/E ratio of 20.8 and a PEG of 0x. Of course, as investors this means that we should also firmly believe in triple-digit earnings growth.
We look forward to your assessment in the comments.
Babcock & Wilcox Enterprises, Inc. is a provider of renewable energy, environmental and thermal technologies to industrial, utility, municipal and other customers. The company operates in three segments: Babcock & Wilcox Renewable, Babcock & Wilcox Environmental, and Babcock & Wilcox Thermal. The Babcock & Wilcox Renewable segment offers technologies for environmentally friendly power and heat generation, including waste-to-energy, biomass-to-energy, and black liquor systems for the pulp and paper industry. The Babcock & Wilcox Environmental segment provides emission control and environmental technology solutions for utilities, waste-to-energy, biomass-to-energy, carbon black and industrial steam generation applications around the world. The Babcock & Wilcox Thermal segment provides steam generation equipment, spare parts, design, maintenance and on-site service for power generation, oil and gas and industrial plants.
Number of employees: 1,625
Babcock & Wilcox transforms from boiler manufacturer to AI profiteer
Babcock & Wilcox Enterprises Inc. (ISIN: US05614L2097) develops energy and environmental technologies, in particular steam generators, boiler systems and emission reduction solutions for power plants and industrial facilities. In addition to sales, the company also concludes long-term service, maintenance and technology contracts. The company was founded in 1867. The share has been tradable on the NYSE since 2015.
On 04.03.2026, the company presented its figures for Q4 2025. Turnover fell slightly by 0.5% to USD 161.0 million. However, the loss was massively reduced by around 92% to just USD -0.05 per share. This clearly beat analysts' expectations.
In addition to the good figures, the announcement of a new major order in the area of energy supply for AI data centers also caused euphoria. This is a USD 2.4 billion project that is expected to deliver up to 1.2 GW of new power generation capacity. In addition, the company is said to be in talks about further data center projects, which could transform it from a traditional energy and boiler manufacturer into an infrastructure supplier for AI data centers.
Conclusion: Babcock & Wilcox shows a significant operational improvement as the loss was sharply reduced despite stagnating sales. The new major contract in the field of energy supply for AI data centers could prove to be a strategic turning point and give the company access to a rapidly growing market. If the company succeeds in winning further data center projects, the investment story could develop dynamically.
Babcock-Wilcox-Enterprises-2025-Annual-Report.pdf
2025 B&W IR Overview
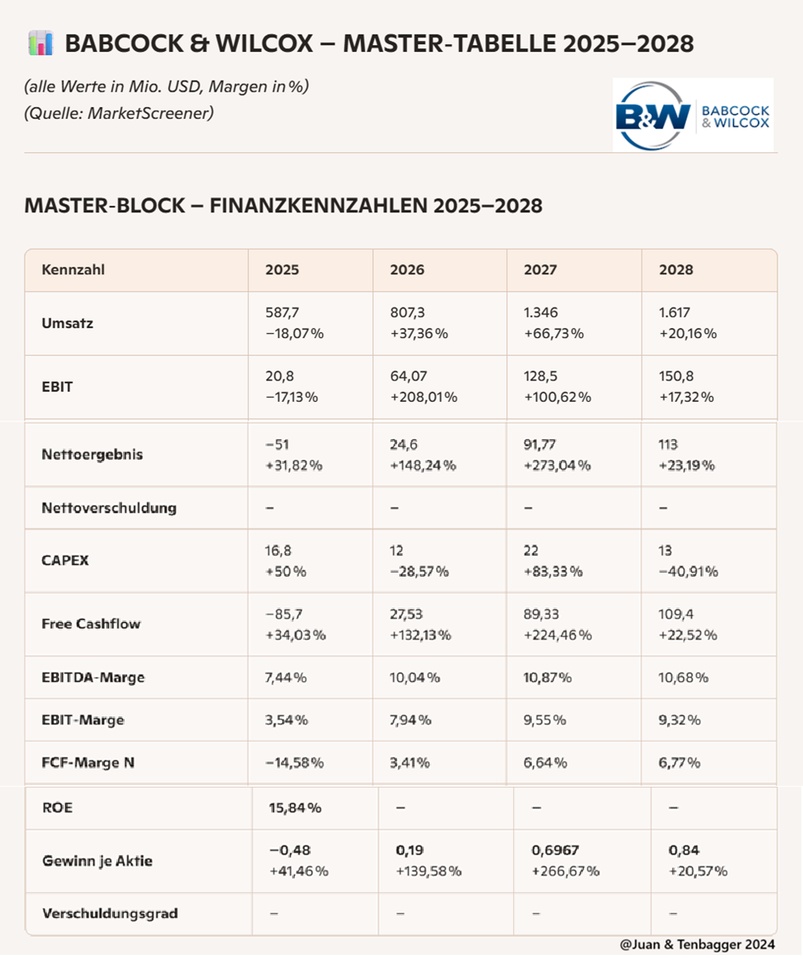
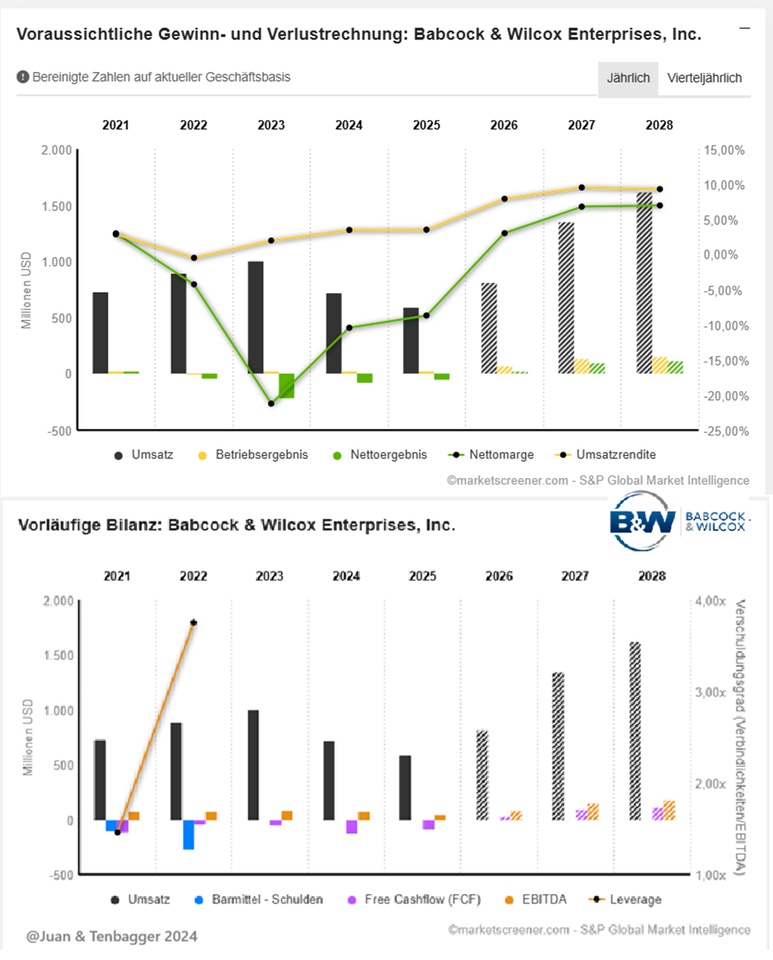
🧠 JUAN-FAZIT - Key financial figures Babcock & Wilcox (2025-2028)
(Source: MarketScreener - Tab 848408656)
1️⃣ Sales & growth - the turbo will not ignite until 2026
2025 is a shrinkage year (-18%), but from 2026 BW turns brutally into growth:
- 2026: +37 %
- 2027: +66 %
- 2028: +20 %
Juan-Take:
"This is a classic turnaround ramp-up. 2027 is a scaling year that you rarely see so cleanly."
2️⃣ EBIT & profitability - from mini-EBIT to real earning power
EBIT development:
- 2025: 20.8 million
- 2026: 64.1 million (+208 %)
- 2027: 128.5 million (+100 %)
- 2028: 150.8 million (+17 %)
EBIT margin increases from 3,5 % → 9,3 %.
Juan-Take: "BW is transforming from a low-margin player to a real revenue model. The 2027 margin is a statement."
3️⃣ Net result - the real proof of a turnaround
2025 still deep red (-51 million), but then:
- 2026: +24.6 million
- 2027: +91.8 million
- 2028: +113 million
Juan-Take: "The jump from -51 million to +113 million in three years is huge. This is not a cosmetic turnaround, this is substance."
4️⃣ Free cash flow - from problem case to cash generator
2025: -85.7 million 2026: +27.5 million 2027: +89.3 million 2028: +109.4 million
FCF margin turns from -14,6 % → +6,8 %.
Juan-Take: "The FCF turnaround is the strongest signal. No turnaround without cash flow - it fits here."
5️⃣ ROE & return on capital - only visible in 2025/2026
- 2025: 15,84 %
- 2026: 15,84 %
- 2027/2028: no estimates
Juan-Take: "ROE is solidly in double digits - but the data ends in 2026. Nevertheless: the direction is right."
6️⃣ EPS - the heaviest lever in the model
- 2025: -0,48
- 2026: 0,19
- 2027: 0,6967
- 2028: 0,84
Juan-Take: "EPS is exploding. It is precisely EPS curves like this that lead to re-ratings."
🎯 Overall conclusion (Juan style)
"BW is a high-beta turnaround that will really pick up speed from 2026. Sales, EBIT, FCF, EPS - everything turns upwards at the same time. 2027 is the key year: scaling + margins + cash flow. Not a quality compounder, but an extremely exciting rebound case with momentum."
🧠 JUAN-FAZIT - Valuation ratios Babcock & Wilcox (2025-2028)
(Data source: MarketScreener, Ref: turn0browsertab1)
1️⃣ P/E ratio - from chaos to normalization
The P/E ratio series shows the entire turnaround in a single glance:
- 2025: -13,2× (year of loss → distorted)
- 2026: 76,3× (profit small → P/E ratio explodes)
- 2027: 20,8× (normalizes)
- 2028: 17,3× (fairly valued)
Juan-Take: "The P/E ratio looks wild, but it tells the truth: 2025/26 are transition years. From 2027, BW will be back in a realistic valuation zone."
2️⃣ FCF yield - the most important indicator turns cleanly positive
- 2025: -12,2 %
- 2026: 1,4 %
- 2027: 4,54 %
- 2028: 5,56 %
Juan-Take: "The FCF yield is the real game changer. In 2027/28, BW shows real cash flow value again for the first time. This is the strongest bullish signal in the entire table."
3️⃣ PEG - volatile, but 2028 will be interesting
- 2025: 0,3×
- 2026: -1× (negative growth → unusable)
- 2027: 0× (EPS jump → PEG collapses)
- 2028: 0,8×
Juan-Take: "PEG below 1 means growth is more favorable than price. 2028 is the first year in which BW looks really attractive."
🎯 Overall assessment (Juan style)
"The valuation ratios show a classic turnaround: 2025/26 chaotic, 2027 stable, 2028 attractive. The FCF yield and the PEG 2028 are the real highlights. BW is not a value play - it is a re-rating candidate with momentum."
PRICE €13.22 (28.04.2026 at 9:25 a.m.)
$BW (-8,49%)