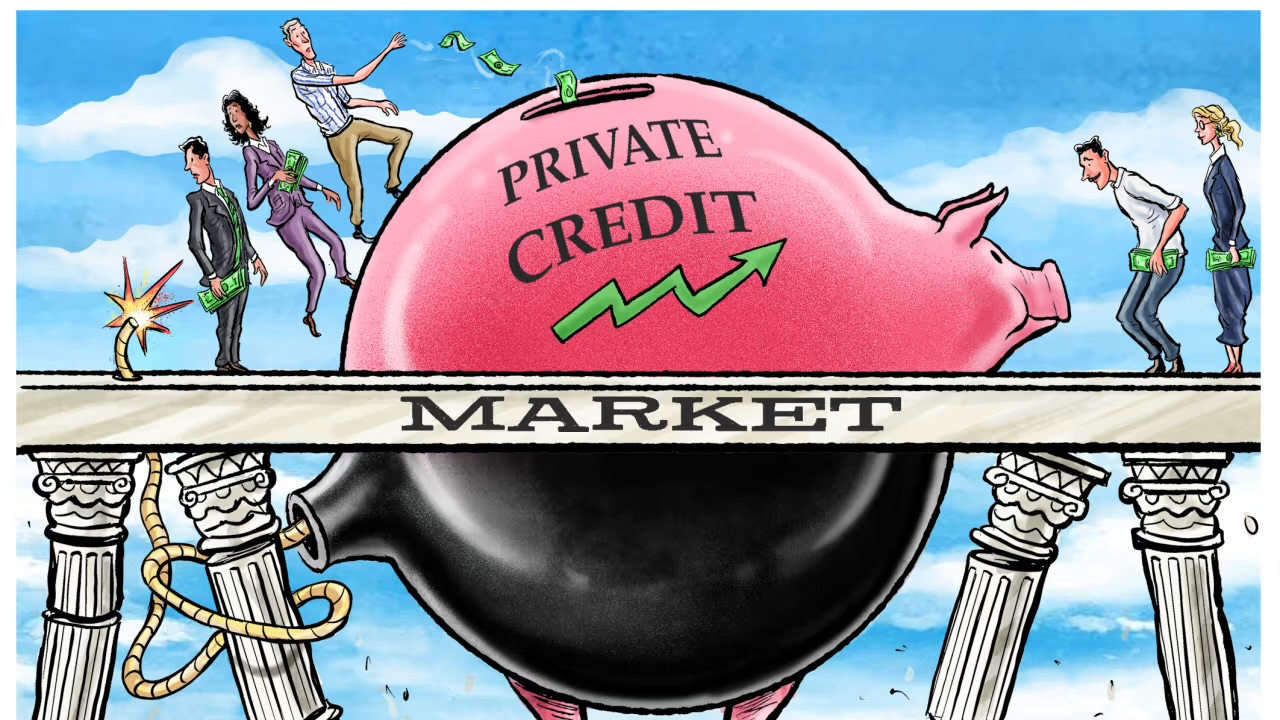
How big of an issue is the private credit “bubble” (if you can call it that)? That’s a question that seems almost impossible to answer right now. At least for me. And I’ll go out on a limb here and say it’s probably not much different for most other investors.
Judging by their ratings, analysts don’t seem to think it’s that big of a deal. Three major asset managers, heavily exposed to the private credit space, are now struggling to pay out investors who are increasingly worried about their capital, while also imposing restrictions on when they can actually cash out. And yet, the average 12-month price target across more than 60 analysts for Blackstone, Apollo and Ares sits at +48%.
So what is it? Are they just doubling down on previously wrong beliefs after these stocks dropped 30% YTD, or do they genuinely think the fears are overblown?
Let’s take a step back and look at the actual issue. Like with many parts of the market right now, it comes back to AI. Roughly 20% of private lending is tied to SaaS, and we’ve seen valuations in that sector compress aggressively over the past few months. Once investors start questioning the relevance of software, those previously “safe” repayments suddenly don’t look that safe anymore.
That’s the core of the fear.
But, and that’s a big but, I think the whole “AI kills software” narrative is massively overblown. Not true for all companies, but for many. At some point people will realise that you can’t just vibe-code cybersecurity or replace something like ServiceNow overnight.
And that probably explains the behaviour we’re seeing from these asset managers. They’re restricting outflows to protect capital and avoid being forced into bad selling decisions. It’s not pretty, but it’s also not a sign that everything underneath is suddenly worthless.
Which brings us to the key difference compared to 2007/08. The underlying loans actually have value. These are functioning companies with real products and real business models, not Long Island strippers buying their fifth house in Florida. Also, the fact that we are all talking about it suggests that, most likely, it’s not going to be a mind blowing crisis.
So the real question is whether this creates an opportunity.
I’d say yes, but with a caveat. I did buy into names that got dragged down in the selloff, but I stayed away from the most obvious, high risk exposure like Blackstone or Apollo that are directly tied to the situation. Mainly because, as I said, I can’t fully assess the extent of the situation. Instead, I focused on adjacent companies that sold off more or less indiscriminately.
That’s where I currently see the better risk-reward. I’ll go into those positions in more detail over the coming days.
$BX (-0,01%)
$KKR (+0,22%)
$APO (-0,15%)
$ARES (+0,07%)
$OWL
$OCSL (-0,24%)