

Our previous series on our investment strategy has now come to an end. Nevertheless, we’d like to continue offering you interesting and—hopefully—helpful content every Friday.
That’s why, going forward, we’ll occasionally compare two companies from a similar market or sector directly with one another.
In doing so, we’ll look at factors such as business models, valuations, dividends, opportunities, risks, and potential entry points.
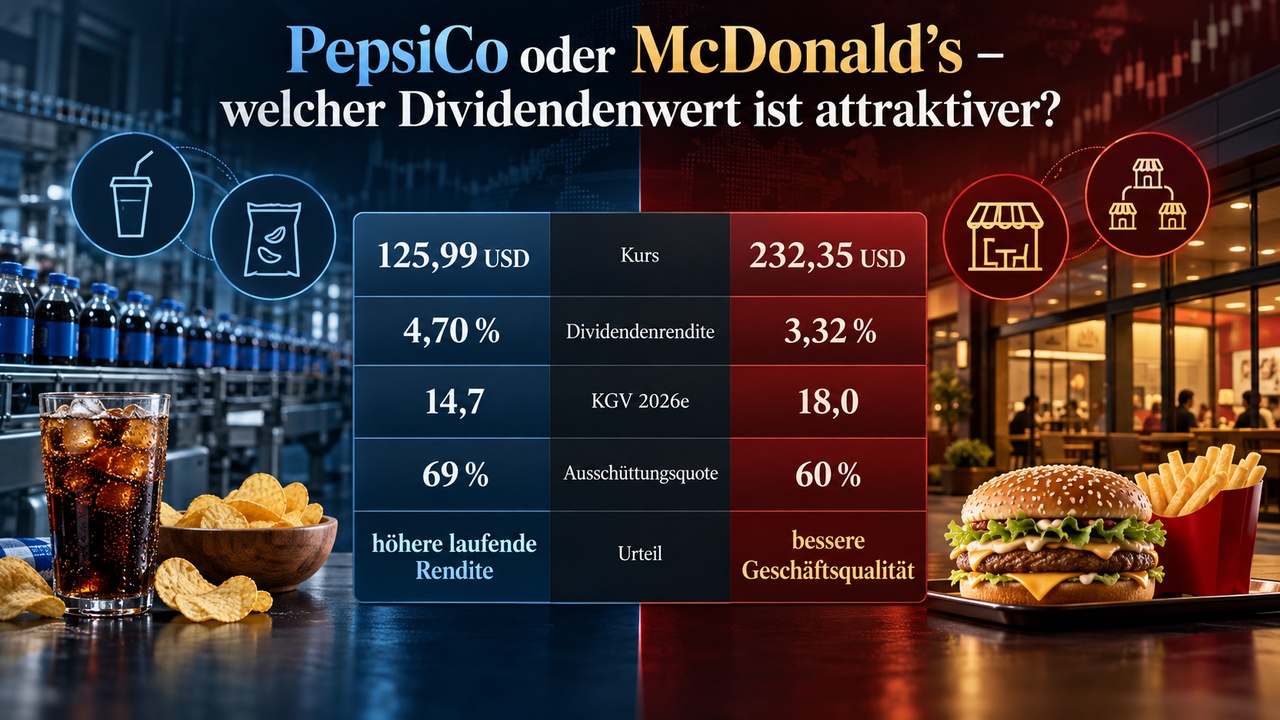
We’re kicking things off today with PepsiCo $PEP (+0,25%) and McDonald’s $MCD (+0,39%) —two well-known quality companies in the defensive consumer sector whose stocks have recently come under significant pressure. Which stock currently appears more attractive, what are their respective strengths and weaknesses, and given today’s dividend yields, is it already worth buying in?
I’m personally considering getting in here myself, but I’m not making any trading recommendations here :)
Business Models and Competitive Advantages
PepsiCo
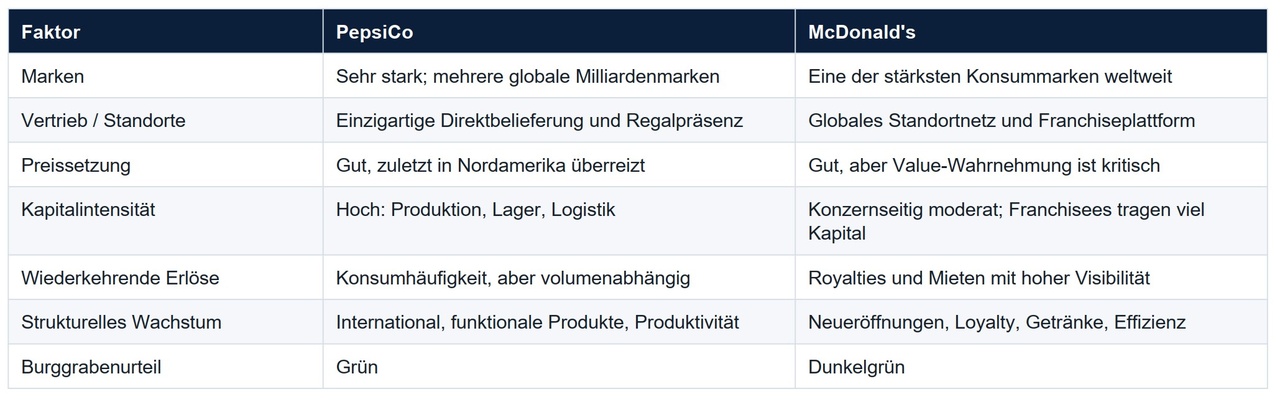
PepsiCo combines global beverages with salty snacks and other convenience products. Its strength lies not only in brands such as Pepsi, Gatorade, Lay’s, Doritos, and Cheetos, but also in production, logistics, direct delivery, and shelf presence. Retailers can hardly do without these products. PepsiCo spreads marketing and logistics costs across multiple categories and benefits from high repurchase frequency and global reach.
McDonald's
Economically speaking, McDonald’s is less a restaurant operator than a global franchisor and real estate partner. The company generates recurring fees and rent, while franchisees bear a large portion of the investment and operational risk. The brand, location network, purchasing power, digital platform, access to real estate, and standardized processes form a moat that is exceptionally difficult to replicate.
Why Have Both Stocks Fallen?
PepsiCo
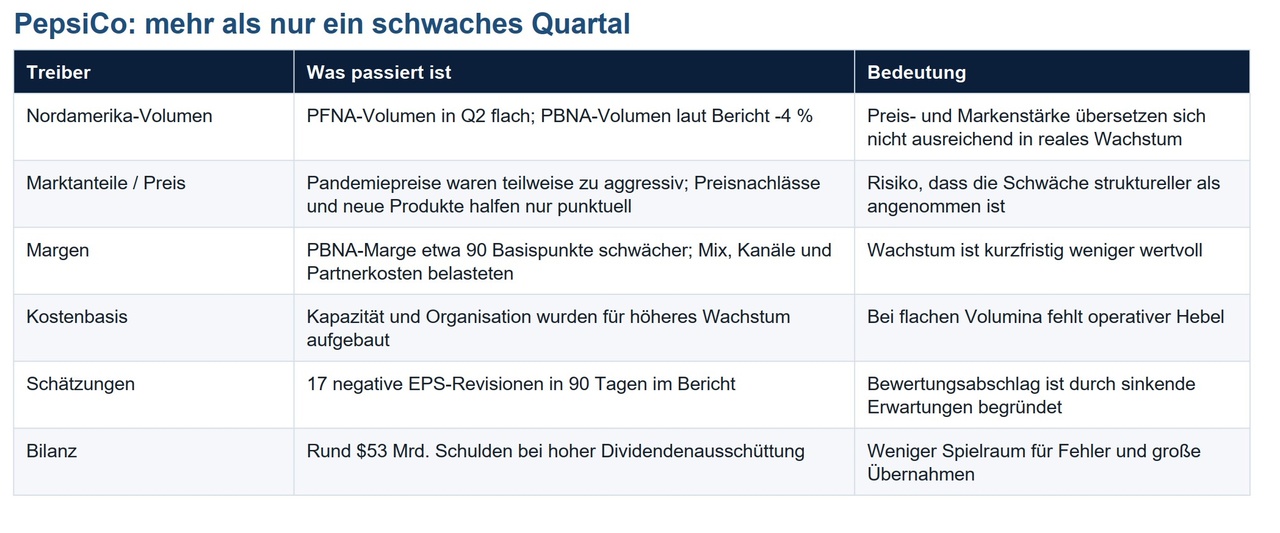
The decline is not merely a reaction to a single weak quarter. The core problem lies in North America. Volume stagnated in the snacks segment and declined in the beverages segment. Following the steep price increases during the pandemic, consumers have become more price-sensitive, while discounts and new products have so far only stabilized sales in isolated cases. At the same time, capacity and cost structures were built up to support stronger growth. With flat volumes, this results in a lack of operating leverage.
McDonald’s
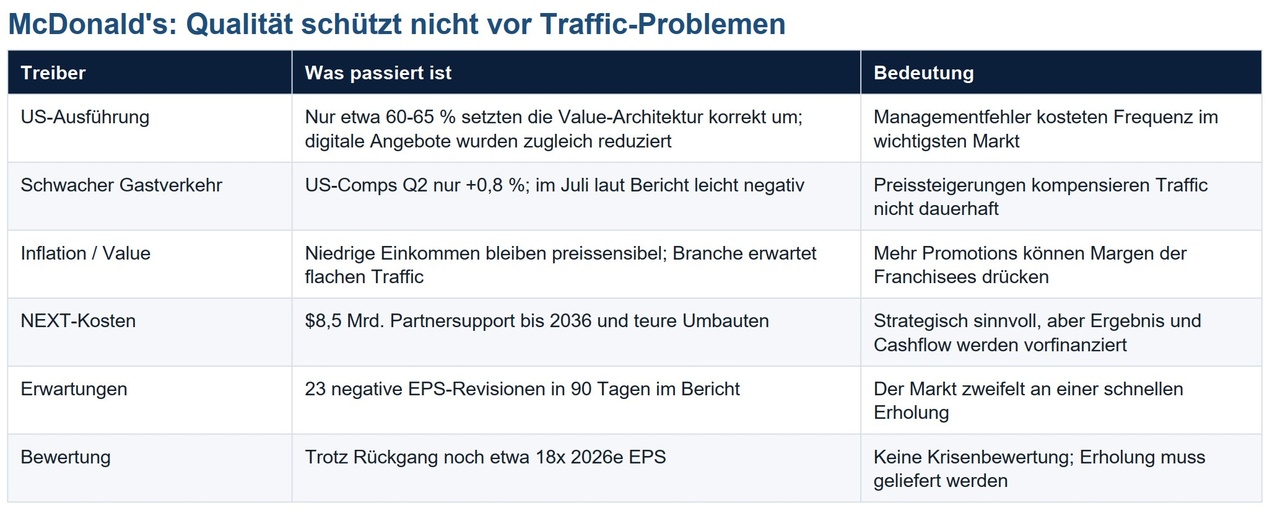
At McDonald’s, the weakness is more a combination of declining foot traffic, operational missteps, and significant investments in the future. In the U.S., the value architecture was not correctly implemented in all restaurants, while digital offerings were scaled back at the same time. Price-conscious customers reacted sensitively. Added to this is the long-term NEXT program, through which McDonald’s plans to support its franchisees with a total of $8.5 billion through 2036.
Important:
Neither PepsiCo nor McDonald’s is a loss-making company.
The stock price declines are primarily due to disappointed growth expectations, weak volume and traffic dynamics, and a lower valuation of future earnings.
PepsiCo Financial Quality and Dividend
PepsiCo Dividend Review
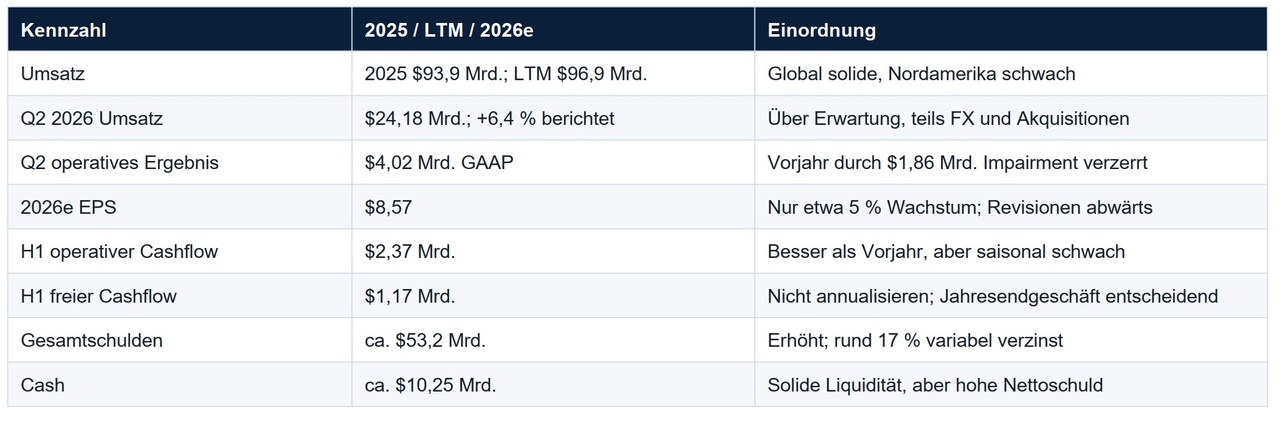
The dividend is fundamentally secure as long as the operating business stabilizes. PepsiCo plans to pay approximately $7.9 billion in dividends and conduct about $1.0 billion in share buybacks in 2026. However, without improved volume and cash flow trends, substantial future increases are unlikely.
Key Opportunities at PepsiCo
- The international business is performing more robustly than North America.
- Shared logistics and productivity programs can reduce costs.
- Siete, Poppi, and functional products are enhancing the portfolio.
- Pressure from activist investors could accelerate portfolio focus and capital allocation.
- A normalization of U.S. volumes would have strong earnings leverage given the low valuation.
McDonald’s Financial Quality and Dividend
McDonald’s Dividend Review
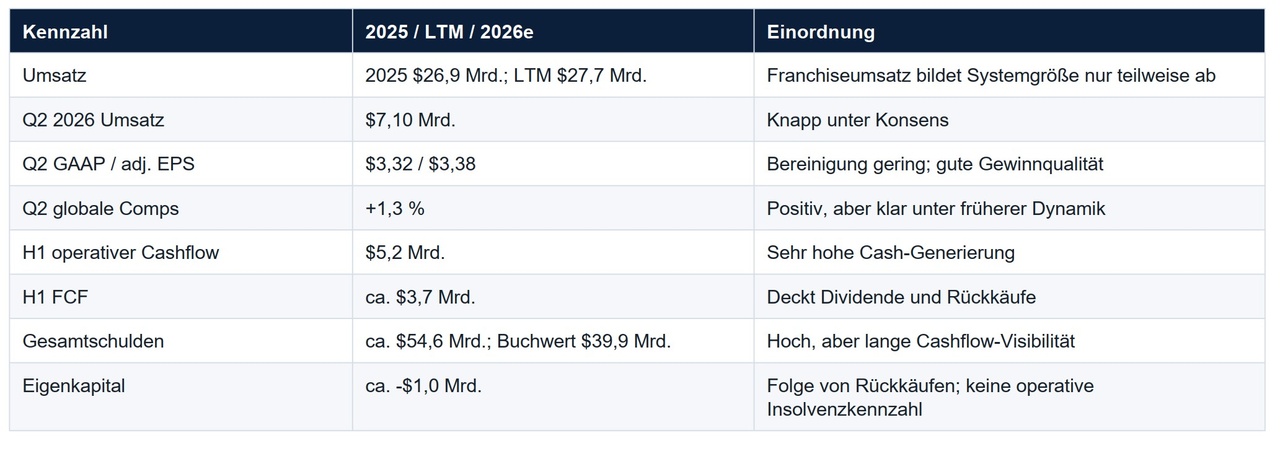
McDonald’s dividend is better secured despite the company’s high debt. The negative equity on the balance sheet is primarily the result of decades of dividends and share buybacks and does not reflect a loss-making business. Interest coverage, maturities, and the financial health of franchisees remain critical factors.
Key Opportunities at McDonald’s
- New restaurants could contribute about 2.5 percent to annual system growth starting in 2027.
- Loyalty programs and digital ordering increase repeat purchase rates and personalization.
- The beverage concept offers additional time slots and revenue opportunities.
- NEXT is designed to streamline procurement and operations and strengthen margins over the long term.
- Better execution of the value strategy can stabilize U.S. guest traffic relatively quickly.
Valuation
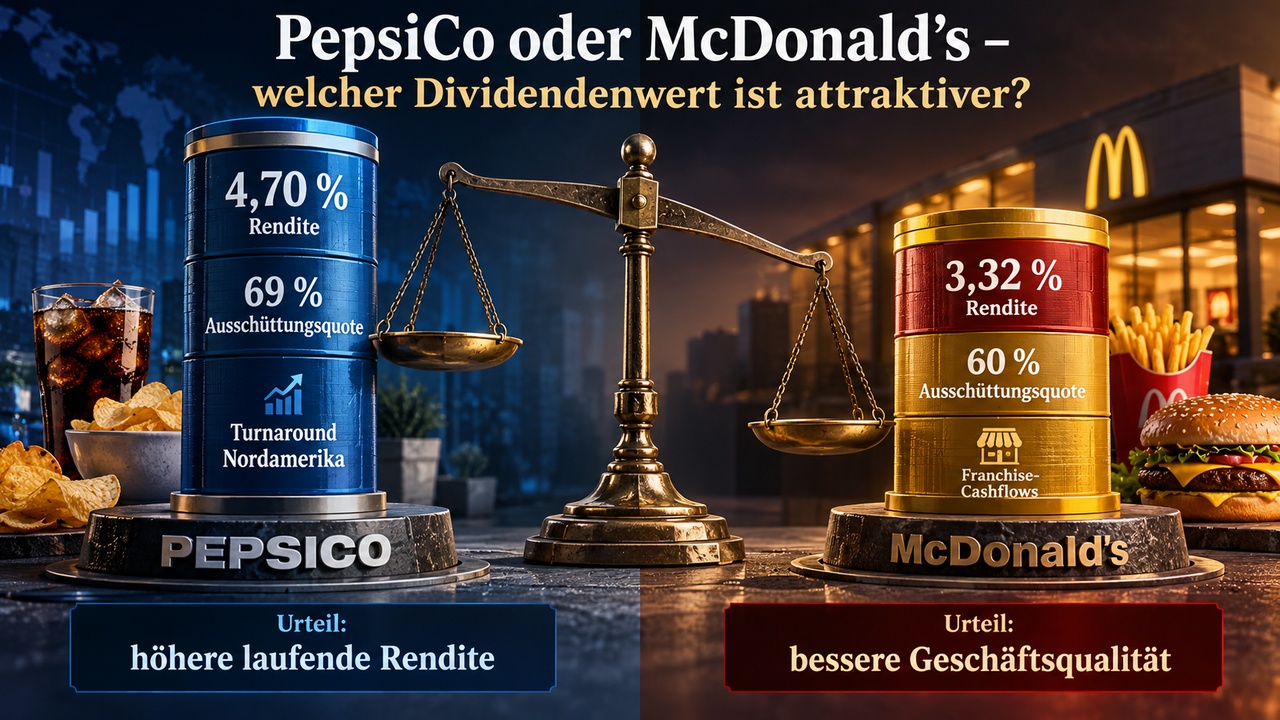
The market price for both stocks is roughly in line with the conservative base-case scenario. PepsiCo offers slightly more upside potential on a technical basis, while McDonald’s offers more robust cash flow quality. The downside risk remains significant if volume, guest frequency, or margins remain under pressure for an extended period.
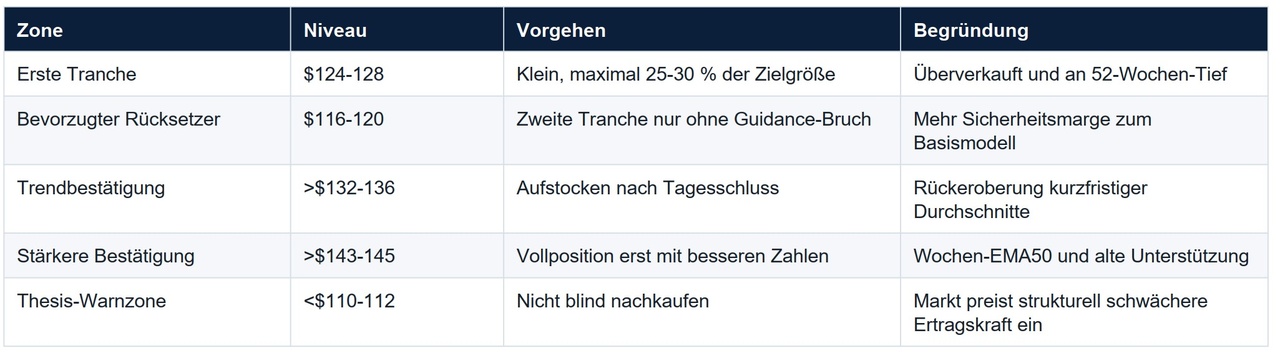
Technical Analysis and Entry Point for PepsiCo
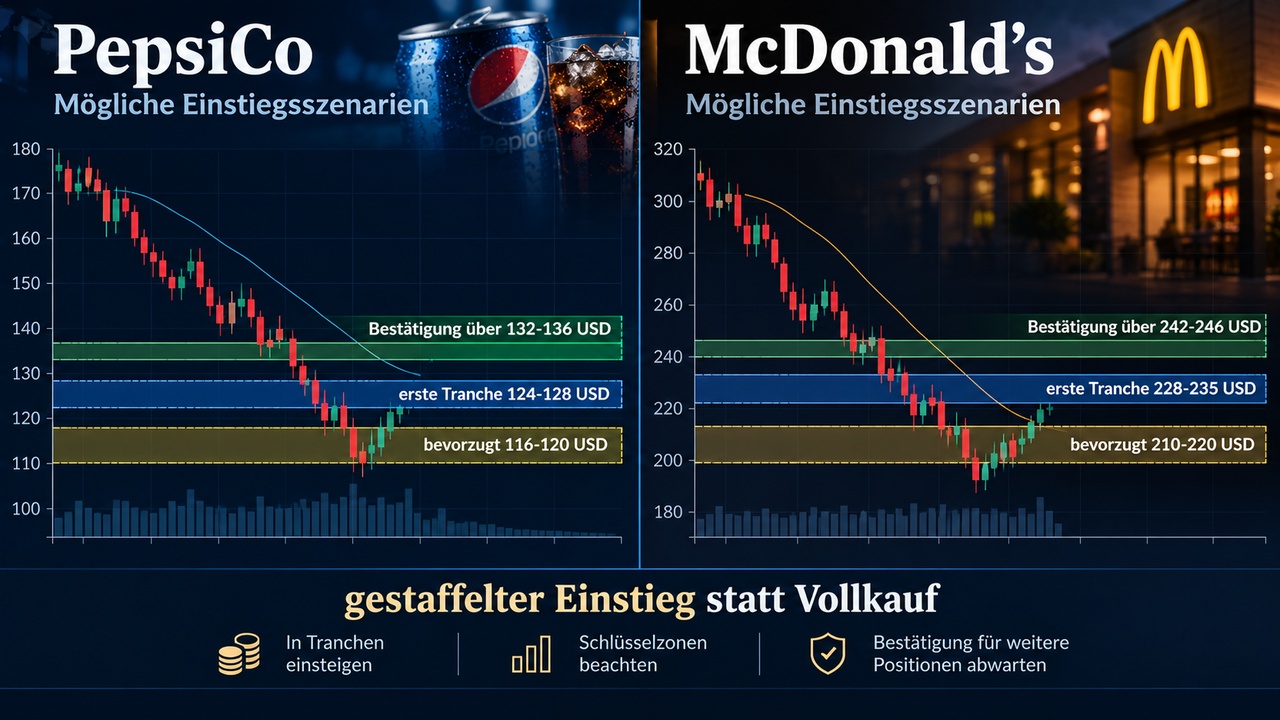
PepsiCo is in an intact downtrend. The daily and weekly prices are below the relevant 50- and 200-period moving averages. A daily RSI around 24 and a weekly RSI around 30 indicate strong oversold conditions, but no confirmed bottom yet. The MACD remains negative.
For a pure rebound position, potential first profit-taking levels are between $139 and $145, with a second zone between $152 and $160. A fundamental breakdown of the thesis would be another guidance cut, ongoing market share losses, persistently insufficient dividend coverage, or further increases in net debt despite weak growth.
Technical Analysis and Entry Point for McDonald’s
McDonald’s is technically even more oversold. The daily and weekly RSI stand at approximately 24 and 23, respectively. The stock price is trading well below the relevant moving averages, the MACD remains negative, and no reliable reversal pattern is yet visible on the weekly chart.
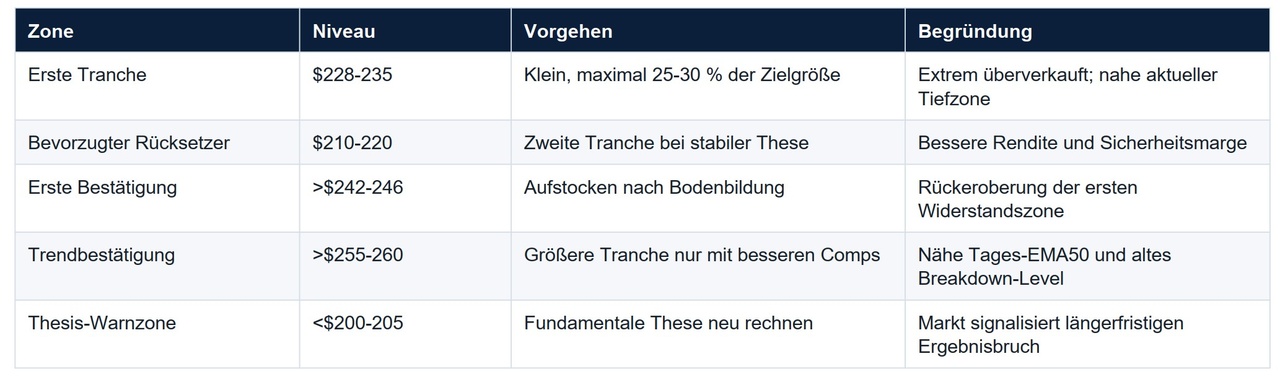
For a pure rebound position, an initial profit-taking zone lies between $255 and $270. Without a clear improvement in U.S. customer traffic and confirmed NEXT economics, $282 to $295 would represent a second valuation zone. A breakdown of the investment thesis would be sustained negative guest numbers, significantly weaker franchisee profitability, unexpectedly higher partner support costs, or a dividend that can only be covered by additional debt.
Key Risks
Both companies face certain risks that should be considered before a potential investment.
A key risk is consumers’ continued high price sensitivity.
We assess the likelihood of this as high, as well as its potential impact. Both PepsiCo and McDonald’s would be affected, as both companies rely on implementing price increases without losing too many customers or sales volume.
At PepsiCo , a particular risk lies in its North American business. Should the turnaround there fail, sales volumes, market shares, and margins could remain under pressure for an extended period. The probability of this occurring is medium to high, and the potential impact would be high.
At McDonald’s , on the other hand, there is a risk that franchisees will be unable to finance the investments and renovations required under the NEXT strategy to the planned extent. The probability of this is currently medium, but the potential impact would be high. In this case, McDonald’s might have to provide greater support to its partners, which would strain its own cash flow.
Another risk is rising costs for raw materials, labor, energy, and packaging. The probability of this occurring is medium to high, as is the potential impact. PepsiCo would be affected primarily through raw materials, production, transportation, and packaging, while McDonald’s would be affected particularly through food prices, wages, and the economic situation of its franchisees.
The high level of debt at both companies should not be underestimated. If interest rates remain high for an extended period, refinancing could become more expensive and limit financial flexibility.
The probability of this risk is medium, and the potential impact is medium to high. Both companies would be affected.
Changing health trends and the increasing use of weight-loss medications, such as GLP-1 agonists, could alter consumer behavior in the long term. We assess both the likelihood and the potential impact as moderate.
PepsiCo could be more severely affected, as lower consumption of snacks and sugary beverages would affect a larger portion of its portfolio.
McDonald’s is more affected by regulatory risks. These include, for example, stricter regulations regarding advertising, nutrition, and working conditions, as well as the potential use of automated or personalized pricing.
We assess both the likelihood and the impact as moderate.
Finally, both companies face currency and geopolitical risks.
Since PepsiCo and McDonald’s operate globally, unfavorable exchange rates, trade conflicts, supply chain issues, or political tensions could weigh on their results. We currently assess both the probability and the potential impact as moderate.
Clear Final Verdict
McDonald’s $MCD (+0,39%) is the preferred buy. The stock combines what has now become an attractive dividend yield with better dividend coverage, a capital-light business model, and a clear long-term growth path. The price around $232 is reasonable for an initial small position. A more convincing margin of safety lies between $210 and $220, or—following a confirmed bottom—above $242 to $246.
PepsiCo $PEP (+0,25%) is also an attractive option at $124 to $128, especially for current income. However, the higher yield compensates for the more uncertain North American turnaround and the tighter cash flow buffer. Ahead of the Q3 earnings report, one should therefore only open a small position or wait and see for now.
And, of course, all the others :)


