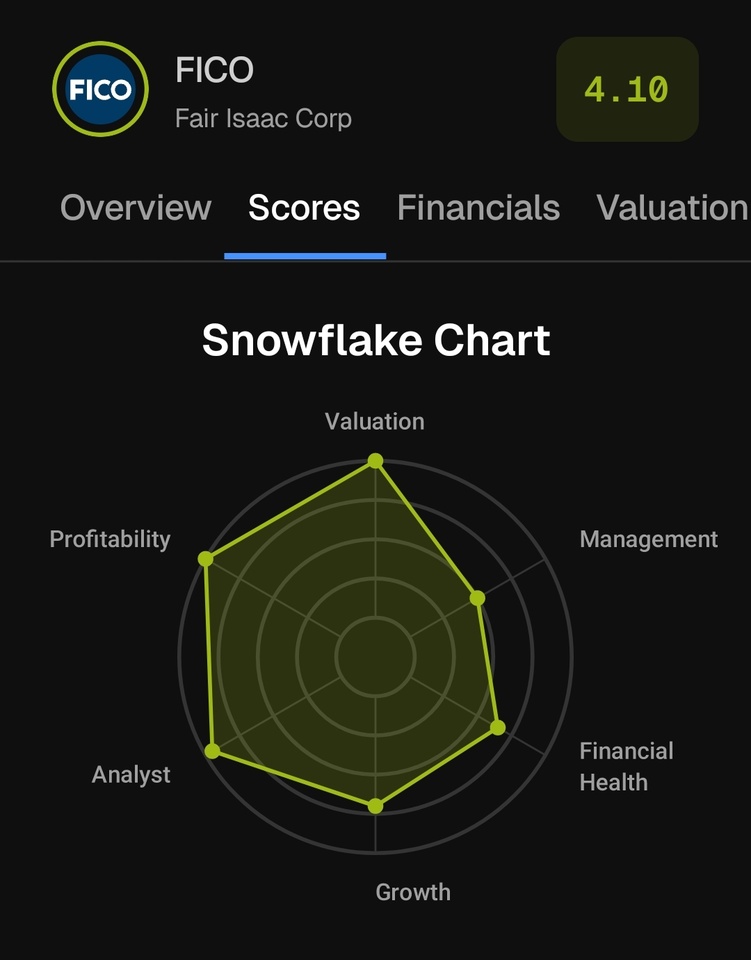
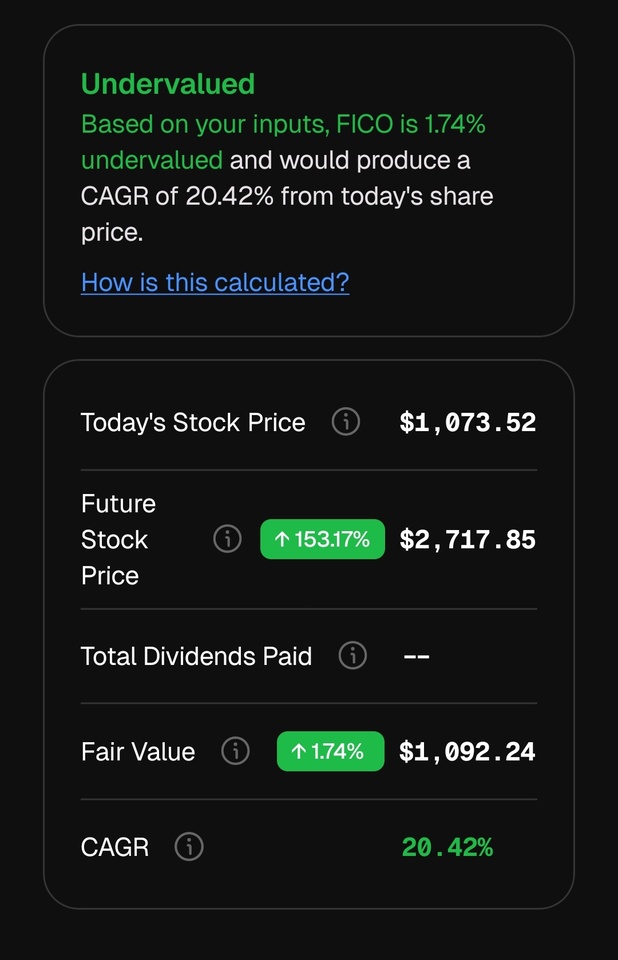
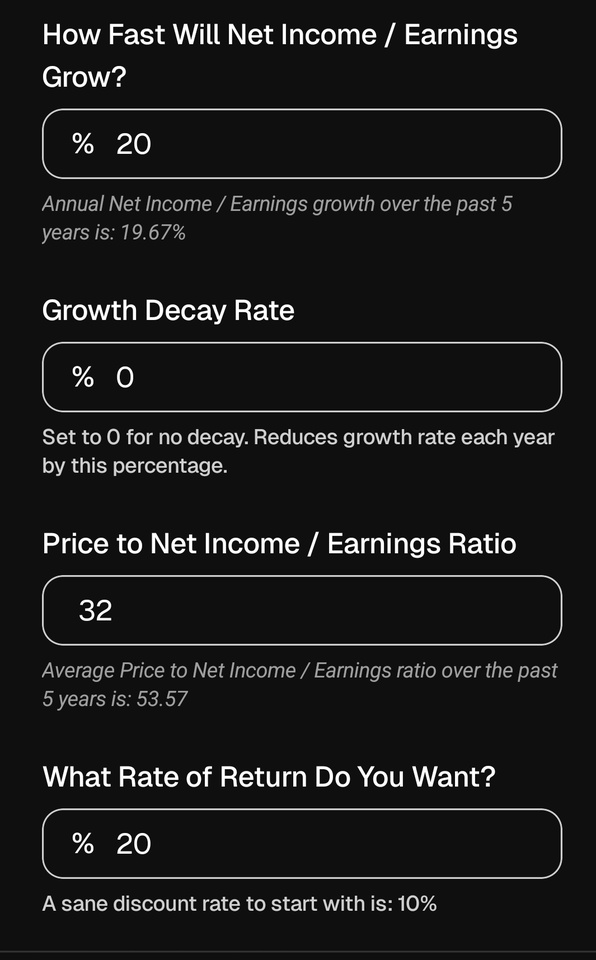
In our series on stocks with the potential for a 20% compound annual return (CAGR), we often look for "disruptors" or "growth monsters". In this installment, however, we take a look at a company that is not as loud as Nvidia $NVDA (+0,31%) but has such a deep-rooted market position that it literally speaks the "language of credit": Fair Isaac Corporation (FICO) $FICO (+0,07%) .
---
Why FICO?
FICO isn't just a company - it's an industry standard. In the USA, the FICO score is the most important indicator for assessing creditworthiness. If you want to take out a loan, you can hardly avoid FICO. This business model offers one of the strongest "economic moats" you can find on the stock market.
---
The numbers behind the thesis
Two central aspects immediately stand out in the analysis:
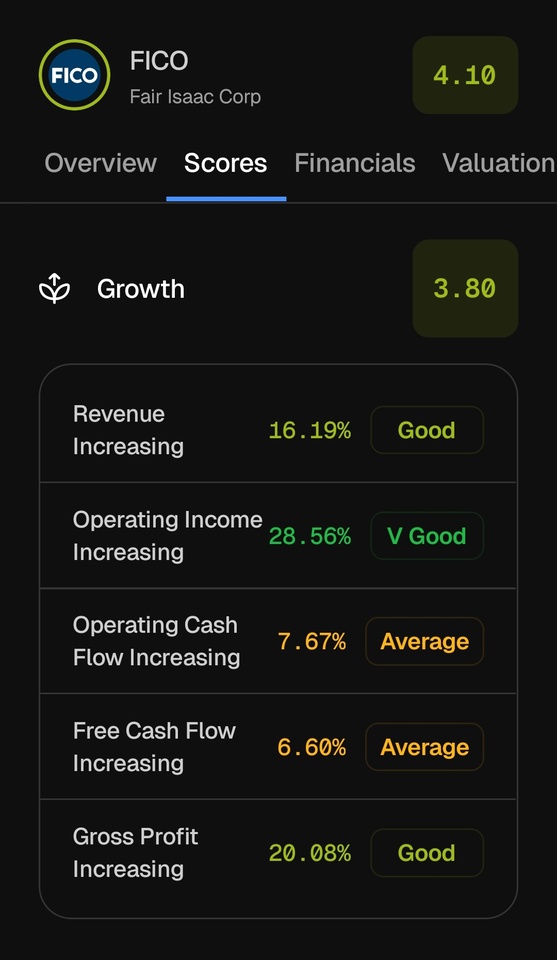
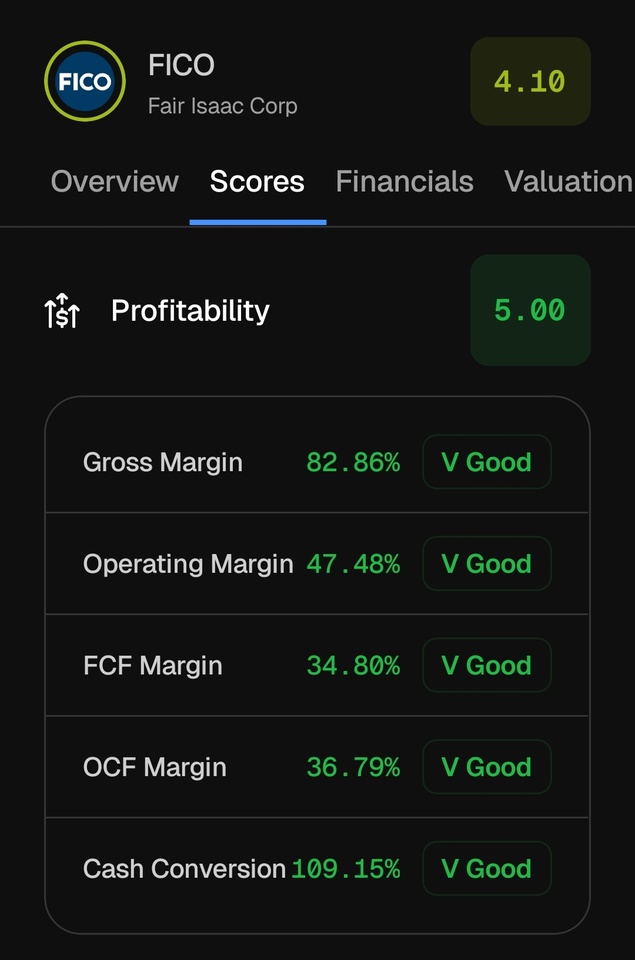
Strong growth & efficiency:
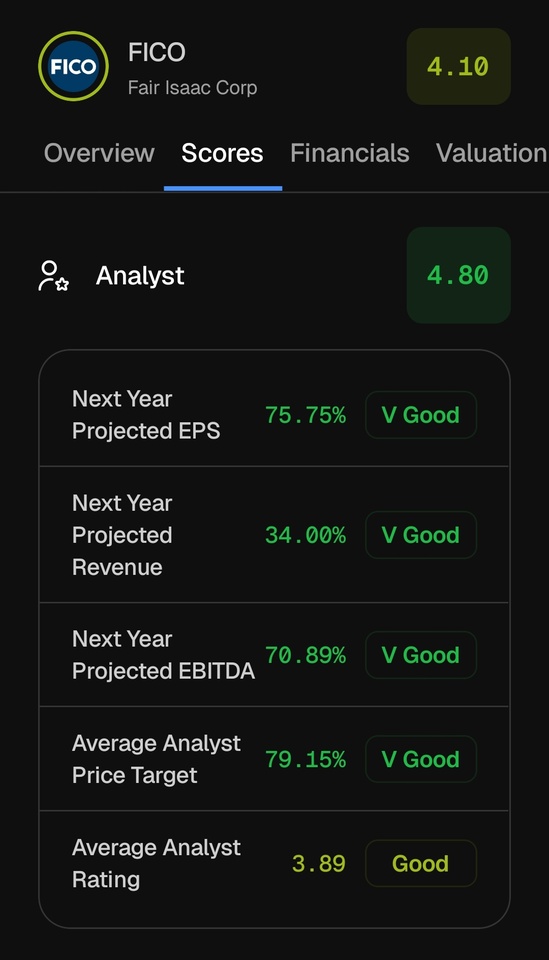
FICO shows an impressive operational development. The company has managed to significantly expand its operating margin while increasing turnover (approx. 16%) - operating income is growing by over 28%.
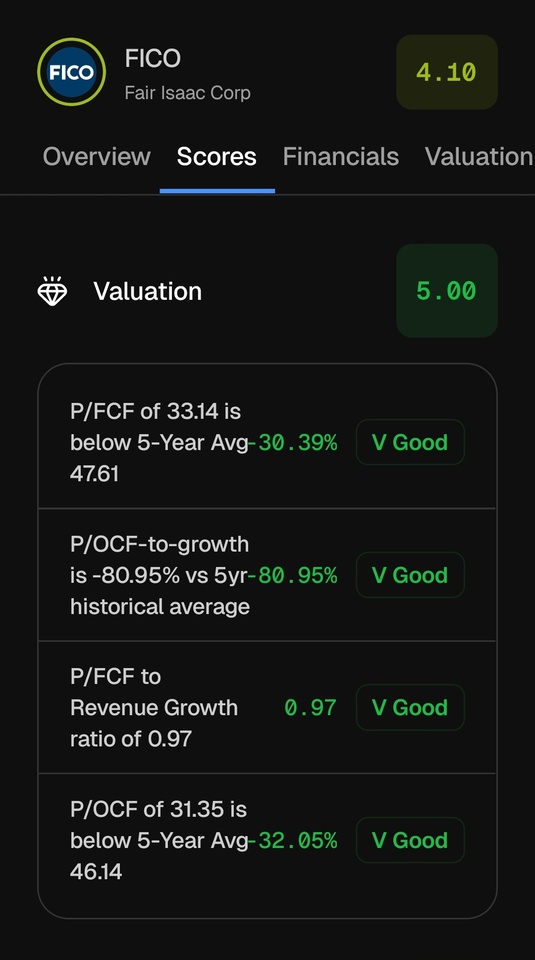
Valuation:
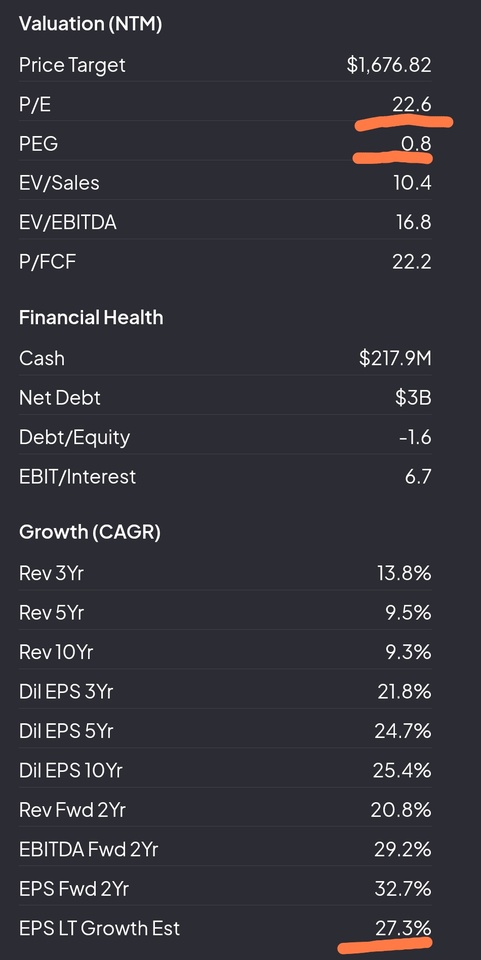
Despite the high quality and dominant market position, the share appears fairly valued to slightly undervalued on the basis of current model calculations. With a forecast CAGR of over 20% for the next five years, FICO fits the profile of this series perfectly. The valuation is lower than it has been for years.
Peg is 0.8!!!
---
Pros & Cons: FICO
Pro (opportunities)
- Monopoly-like position:
The FICO score is firmly anchored in the financial world. The network effects are enormous, as banks and lenders rely on a standardized system.
- Shareholder value:
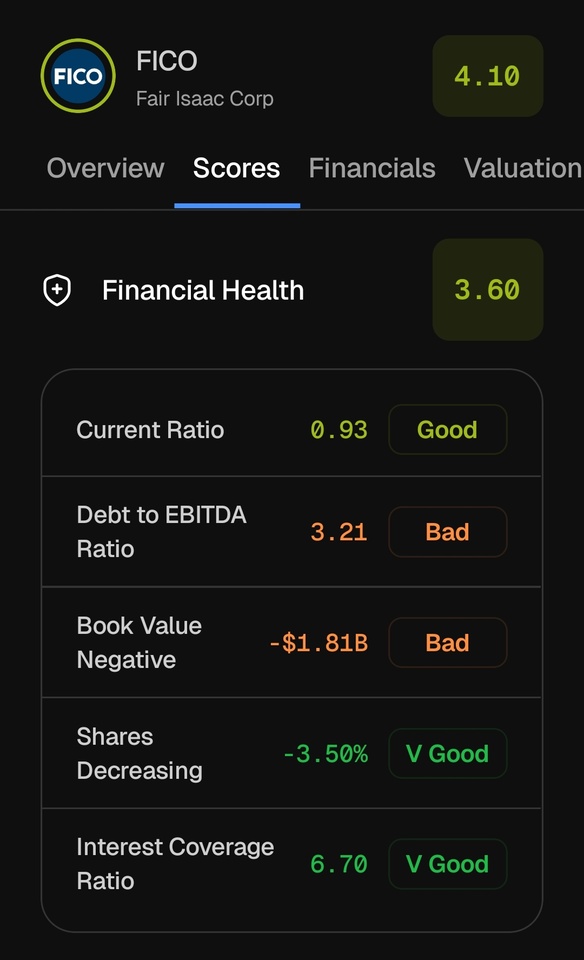
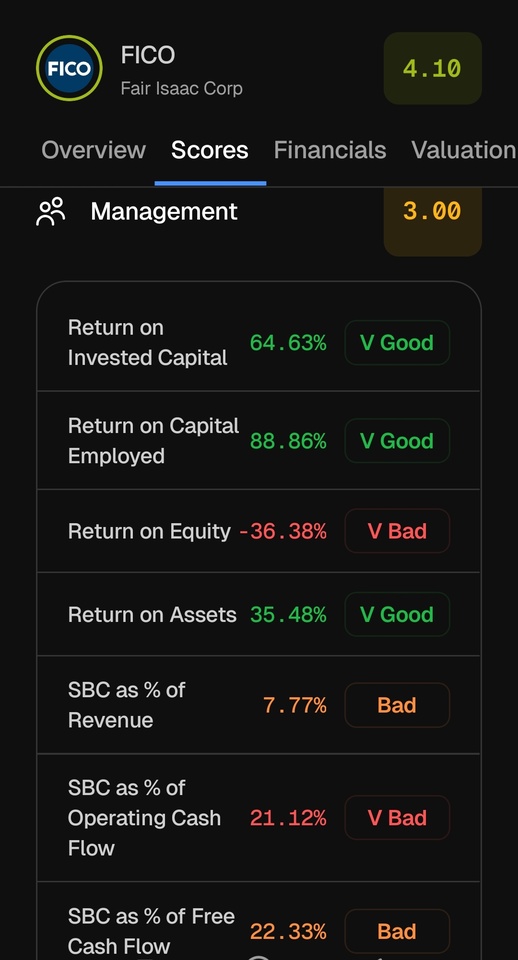
Management clearly acts in a shareholder-friendly manner. A key driver is the continuous reduction of outstanding shares (share buybacks), which increases earnings per share in the long term.
- Pricing power:
As the product is business-critical for financial institutions, FICO has strong pricing power and is good at passing on cost increases.
---
Cons (risks)
- Balance sheet structure:
A critical look at the financial position reveals a negative book value. This often results from massive share buybacks. While this can increase returns, the debt level should be monitored closely.
- Dependence on the credit market:
The business model is closely linked to credit activity. A sustained slump in demand for credit - due to permanently high interest rates, for example - could slow down growth.
---
Conclusion
FICO is an exciting example of how a seemingly "boring" software company can become a performance machine through a dominant market position. The combination of an established product and disciplined capital management (especially share buybacks) forms the basis for the potential CAGR of around 20%.
What is your opinion?
Is FICO a safe-haven stock for a 20% portfolio - or is the negative equity too much of a risk for you?
I don't own shares in FICO but I am actively considering buying shares.
A detailed analysis of FICO
https://youtu.be/Z8cFd4HLpKA?is=3HP7SjKnHopt6zOz