The next stock on my 2026 list, and arguably the most exciting one, is Zeta. This is my biggest satellite position. Yes, it’s volatile. No, it’s not a mature compounder with decades of customer lock-in yet. But it absolutely has the potential to become one over the next few years.
I started building my position toward the end of last year in the $17–18 range, and it now represents roughly 5% of my portfolio. This is not a trade. This is a long-term bet on a company that sits right at the intersection of AI, data, and enterprise marketing.
At its core, Zeta Global is a customer intelligence and marketing platform for large brands. Think Nike, Disney, Ford, or major banks. These companies have millions of customers, but their data is fragmented everywhere. Emails live in one system, website clicks in another, store purchases somewhere else entirely. Zeta’s platform, called Athena, pulls all of that data together, cleans it up, and uses AI to predict what a customer is likely to do next. It’s essentially a decision engine. Instead of blasting generic ads, Zeta helps brands reach the exact right person at the exact right time.
What has investors excited recently is the shift to agentic AI. Athena is no longer just showing dashboards and charts. Thanks to Zeta’s partnership with OpenAI, marketers can literally talk to the software. You can ask Athena to identify a specific customer cohort, design a campaign, build the content, and execute it automatically. This turns software from a passive tool into something closer to an autonomous employee. That is a massive step change.
Zeta is also very different from competitors like AppLovin. AppLovin dominates mobile apps and performance marketing, especially gaming. Zeta operates across the open internet, email, web, and connected TV, focusing on high-value purchases like cars, financial products, and long-term brand relationships. That difference matters.
The real moat, though, is data. Zeta owns a deterministic identity graph of roughly 2.5 billion real people. This is first-party, consented data. As cookies disappear and privacy restrictions tighten, much of ad-tech is flying blind. Zeta is not. Brands come to Zeta because it still knows who the customer actually is. That advantage cannot be replicated overnight.
Execution matters, and this is where Zeta really separates itself. CEO David Steinberg has been delivering quarter after quarter, with Zeta beating and raising guidance for 16 consecutive quarters. That alone puts the company in rare territory.
But let this quote from Steinberg actually sink in:
“Eight out of 512 tech companies grew at a 20%+ CAGR for four years. The other seven trade at over 50x P/EBITDA.”
Zeta trades at roughly 16.6x P/EBITDA.
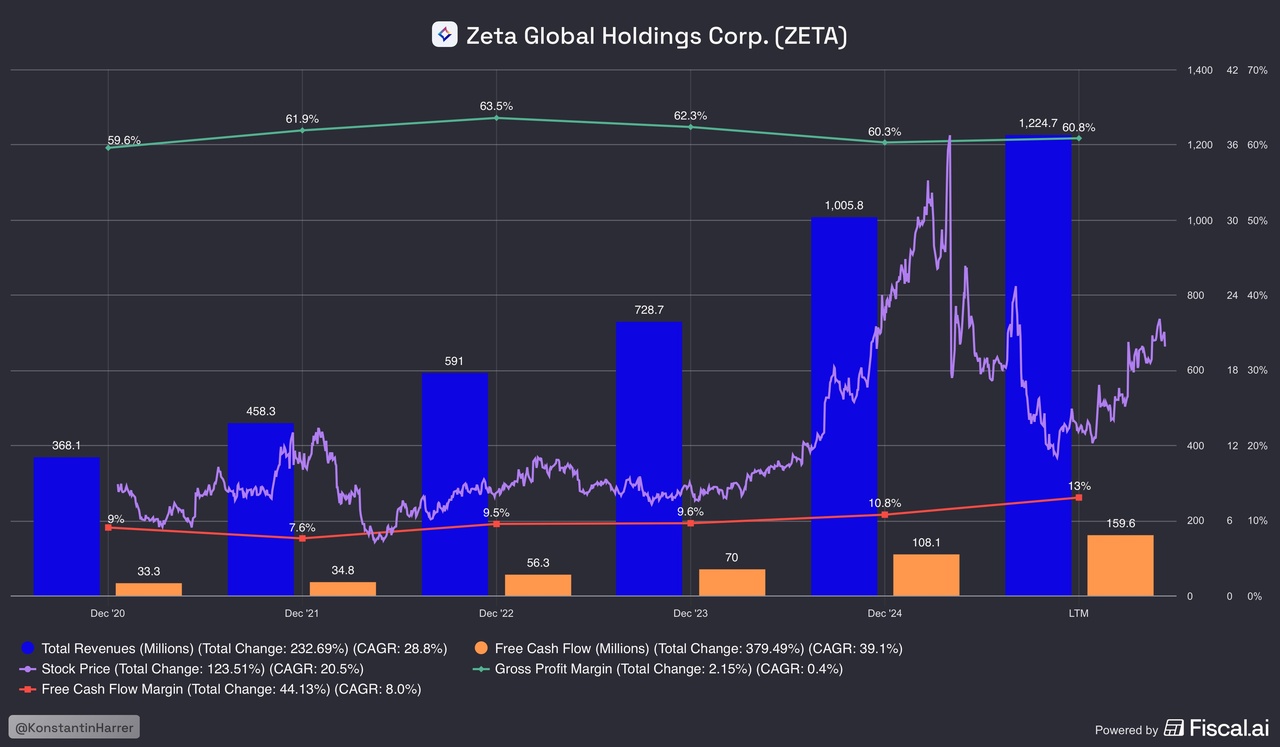
At the same time, revenue is projected to grow north of 30% annually, free cash flow yield exceeds 8% on FY27 estimates, and the company owns one of the largest first-party data clouds in the world. Steinberg has said it clearly: Zeta can make the same or better decisions for its clients in milliseconds, and that directly translates into superior ROI.
This stock is volatile. I genuinely do not care. I do not look at daily price movements. I am buying into what I believe is one of the most underappreciated AI beneficiaries in the market today.
This is a five-year story. The payoff comes later.