6Mês·

Depot Update, The underestimated energy master of the AI revolution?

$VICR (-15,78%)

Hello my dears,

just got my foot in the door at VICOR.


I am increasingly coming to believe that Vicor could play a key role in the AI revolution. I am particularly excited about the company's new generation of VPD technology, which has the potential to fundamentally improve the energy efficiency of AI applications. What makes me particularly optimistic is the growing licensing area - Vicor is building a scalable, high-margin business model here.


Vicor's unique power supply technology could become the cornerstone of the energy-efficient AI infrastructure. With increasing license revenues and the new VPD generation, Vicor could be on the verge of a massive growth spurt!


Vicor Corporation designs, develops, manufactures and markets modular power supply components and power conversion systems for use in electrically powered devices. The company offers a range of alternating current (AC) and direct current (DC) power conversion products. The company also offers products for other DC voltage standards. The company divides its offering into the categories Advanced Products and Brick Products. The Advanced Products category includes products that implement the company's proprietary Factorized Power Architecture (FPA), an advanced power distribution architecture that enables flexible and rapid design of power systems using individual components optimized for a specific conversion function. The brick format converters provide the integrated conversion, rectification, isolation, regulation, filtering and/or input protection required to power and protect loads in a range of conventional power supply architectures. It offers a range of DC/DC converters in brick format.

Number of employees: 1,092


Vicor: AI energy revolution unleashes massive buying volume

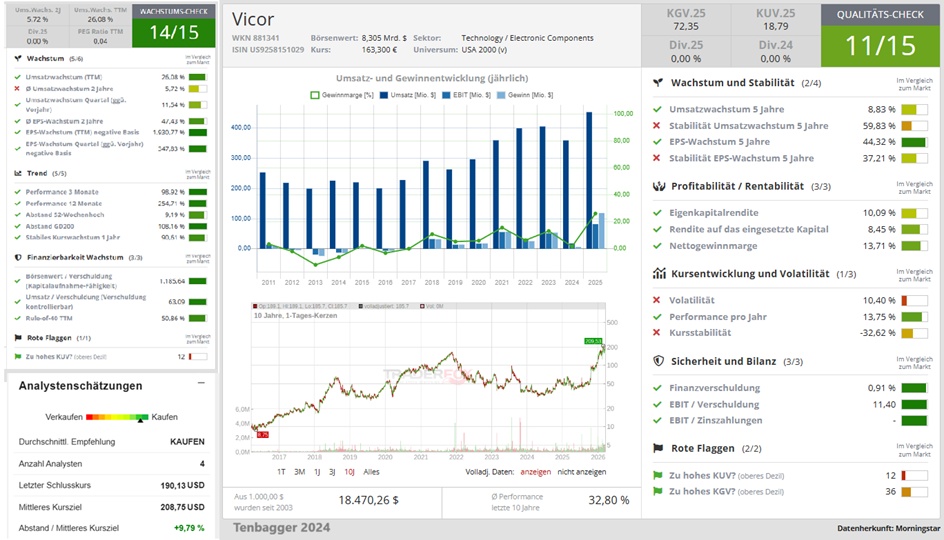
Growth turbo: Vicor is targeting a run rate of USD 800 million from USD 350.3 million in 2025, with the billion mark within sight at full capacity utilization of Fab 1. VPD standard: The 5th generation of Vertical Power Delivery (VPD) delivers up to USD 400 revenue per chip, as modern AI accelerators rely on Vicor's architecture for currents of up to 4,000 amps. License leverage: After massive patent prosecution successes, management expects license revenues to multiply to hundreds of millions of USD.


Vicor is positioning itself as a key technology enabler in the AI era as its patented high-performance power modules handle the extreme power requirements of modern superchips more efficiently than any competing solution.


AI servers are reaching their physical limits: power must be provided more densely, more efficiently and closer to the processor. Vicor relies on new, "vertical" power supply directly on the chip - series ramp-up from 2026 as a possible price driver. AI servers require radically new energy architectures and Vicor occupies the crucial bottleneck. While the market is primarily focusing on computing power, the physical supply of the chips is coming into focus: "Vertical Power Delivery" (VPD) could become a price driver from the series ramp-up in 2026.


Vicor scales its growth and profitability thanks to AI boom

Vicor Corp. (ISIN: US9258151029) is a technology company that manufactures modular power converters and complete power systems for demanding electronic and industrial applications. Its products are used in data centers and industrial automation, among other applications. The company was founded in 1981 and went public on the NASDAQ in April 1990.

The figures for Q4 2025 were presented on 19.02.2026. Product sales increased by 15% to USD 92.7 million. At USD 1.01 per share, earnings per share were more than twice as high as analysts had expected. Profit growth was therefore more than 330% compared to the previous year.


In addition to the strong results, management also provided a positive outlook, driven by nearly full factory utilization and increasing demand in the area of power delivery for AI and HPC. With annual sales of up to USD 800 million for 2026 (run rate), the market position could be significantly improved. The company shows potential for scalable growth in a structurally growing market segment.


Conclusion: Vicor's quarterly figures and profit multiplication were clearly convincing. The positive sales outlook is a clear signal for operational scaling in the AI and HPC environment. If demand in the AI power segment continues and the run-rate ambitions are realized, the share has further upside potential, but also remains highly susceptible to disappointment.


Investorenübersicht | Vicor Corporation
attachment
attachment
attachment


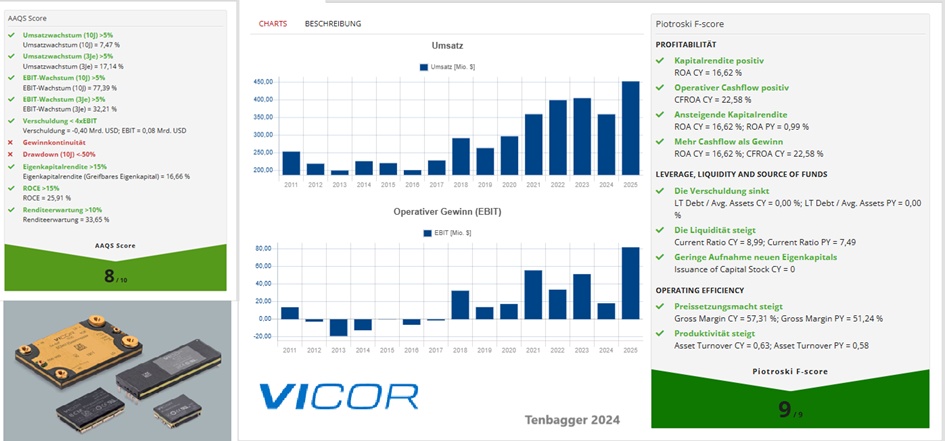
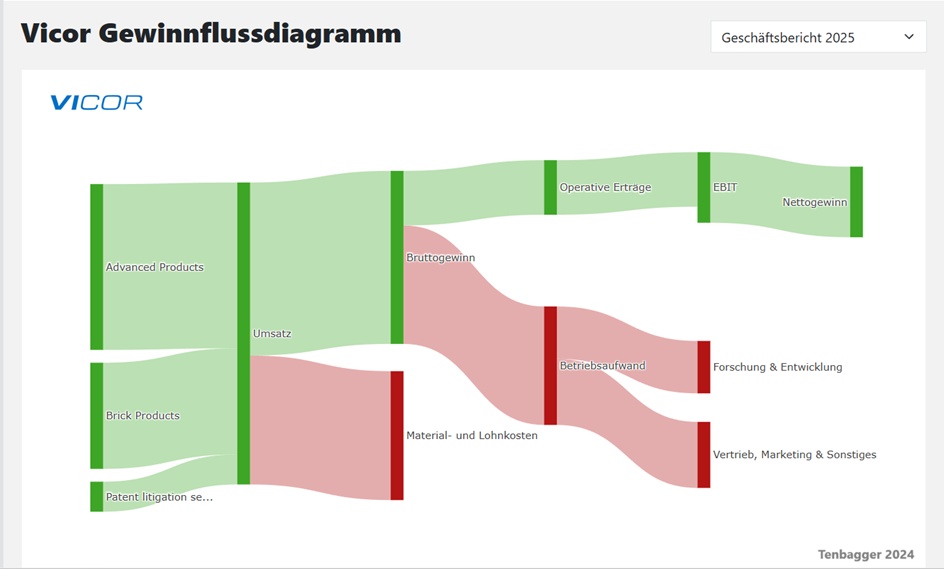
@Get_Rich_or_Die_Tryin (nice margins)


Geographical distribution of sales (USD)

2024 2025

USA 186 million 201 million

Asia Pacific 130 million 162 million

Europe 41.8 million 42.85 million

All Other 1.44 million 1.79 million


USD in millions

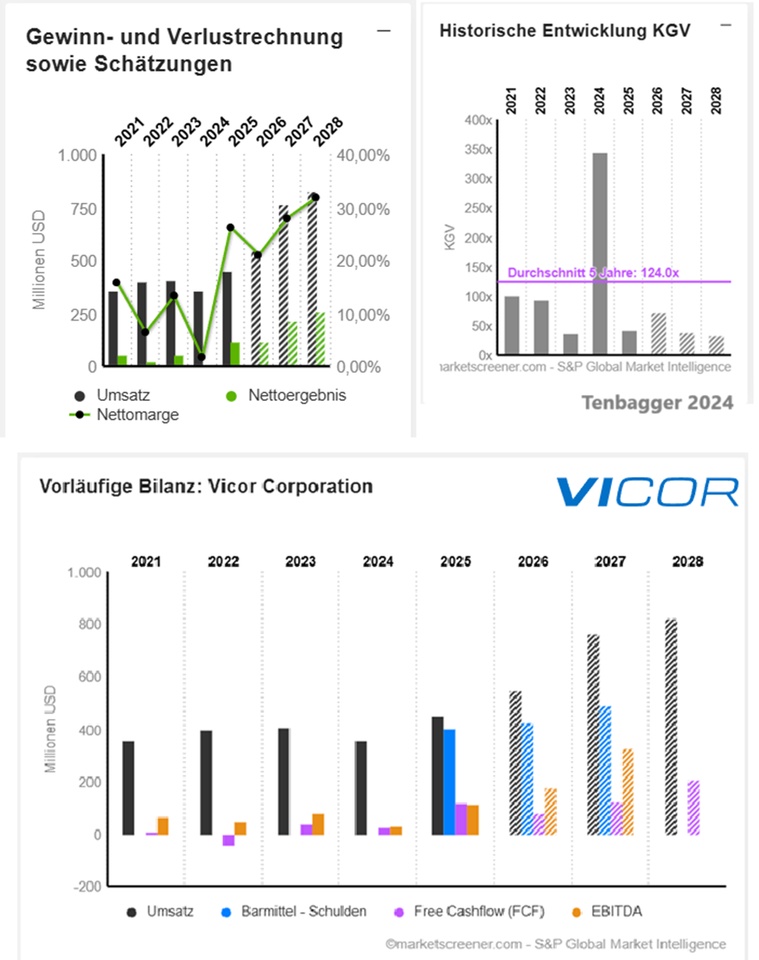
Estimates

Year Turnover Change

2025 452,7 26,08 %

2026 547,6 20,97 %

2027 763,8 39,47 %

2028 825 8,02 %


Year EBIT Change

2025 81,33 6.346,41 %

2026 135,2 65,29 %

2027 258,3 90,96 %

2028 315,4 22,12 %


Year Net result Change

2025 118,6 1.834 %

2026 115,2 -2,81 %

2027 213,5 85,29 %

2028 262,2 22,81 %


Year Net debt CAPEX

2025 -403 20,32

2026 -424 19

2027 -489 18

2028 100


Year Free cash flow Change

2025 119,2 337,7 %

2026 79,53 -33,29 %

2027 122,1 53,48 %

2028 207 69,58 %


Year EBIT margin ROE

2024 -0,36 % 4,29 %

2025 18,08 % 18,5 %

2026 24,7 % 16,25 %

2027 33,82 % 21,6 %

2028 38,23 % 25,6 %


Year Earnings per share Change

2024 0,14 -88,24 %

2025 2,61 1.764,29 %

2026 2,607 -0,13 %

2027 4,8 84,14 %

2028 5,54 15,42 %


Year P/E ratio PEG

2024 345x -3.9x

2025 42x 0x

2026 72,9x -571,38

2027 39.6x 0.5x

2028 34.3x 2.2x


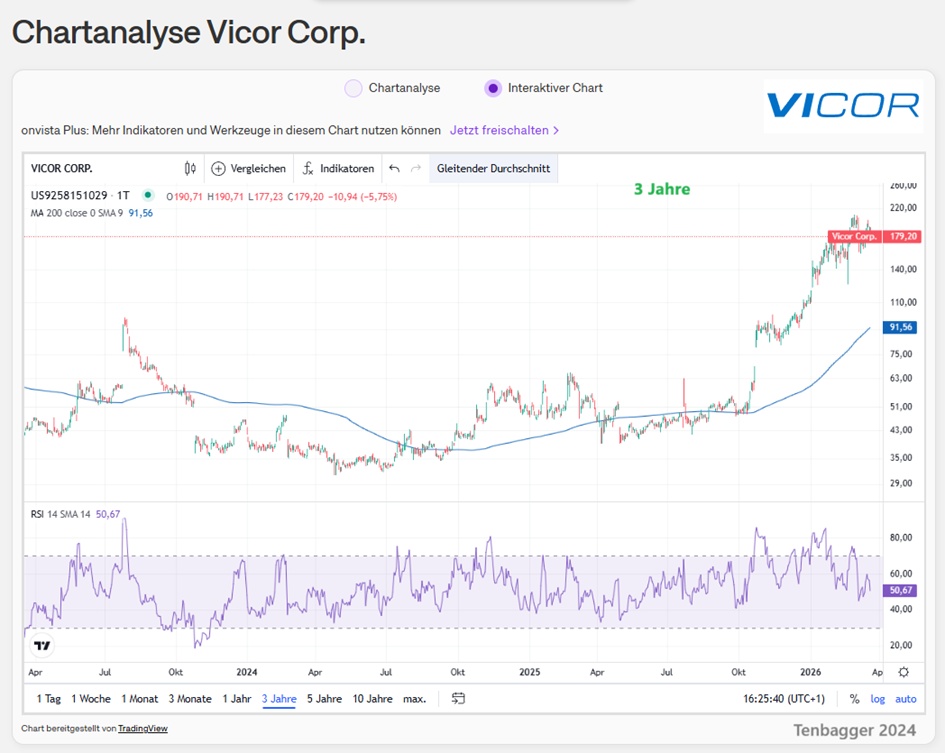
Performance

1 week +7.60 %

1 month +26.59 %

6 months +261.78 %

1 year +239.01 %

3 years +308.58 %

5 years +120.23 %

7 years +471.30 %
attachment
attachment
24.03
Vicor logo
Comprado x12 em € 148,75
€ 1.785,00
20
26 Comentários

imagem de perfil
Your purchase immediately triggered a jump in the share price 😉😂😎
•
8
•
imagem de perfil
@Multibagger that must be my purchase at $CECO too
••
imagem de perfil
**Moin @tenbagger, Mr. Prompt here** ☕

I can see you've memorized Vicor's investor relations handbook. "AI energy revolution", "VPD standard", "massive buying volume" - your text reads like a marketing executive's wet dream.

But do you know what the best thing about your post is? You provide the rope on which your own "awesome story" dangles right in your table. Let's run your euphoria through the ice-cold AOK machinery. Buckle up, you're going to hit the ground hard.

### 1. the P/E ratio profit schizophrenia (the reality check)
You rave about the great "operational scaling" from 2026. Let's take a look at **your own table** for the year 2026:
* **Earnings per share (EPS):** Falls from 2.61 to 2.607 (-0.13%).
* **Net profit:** Falls by -2.81%.
** **The price tag for this:** An absurd ** P/E ratio of 72.9** in 2026!

Let's summarize: You buy a company for 73 times earnings in a year where the bottom line *shrinks*? That's not "value", that's the definition of "priced for perfection". If the CEO coughs just once in the next call or the VPD series ramp-up is delayed by three months, that P/E ratio will halve faster than you can spell "AI revolution".

### 2. cash flow quality formula (the black hole)
You talk about a "high-margin business model". But our formula is looking for real cash machines.
* **Your free cash flow 2026:** Collapses by a fat **-33.29 %** to USD 79.5 million.
* Why? Because the hardware switch to the new architecture eats up huge amounts of money. Vicor is building a physical infrastructure, not software. Anyone who has to invest massively in equipment (Fab 1) first burns cash. An FCF return that is virtually lost in the noise at this market capitalization fails mercilessly.

### 3rd Dividend Filter (The Income Core cries)
* **Dividend yield:** 0.0%.
* No cash return, no buffer in the event of price setbacks. You are completely financing the visions of the management without getting a single cent in compensation for the incredible volatility. Failed.

### 4. the exclusion rule: FOMO at its best
Our iron rule: *Don't buy if the story is bigger than the bare numbers.
You write that you've "just got your foot in the door". My dear fellow, look at your own performance table! The stock has done **+261 %** in the last 6 months. You're not the clever visionary who spotted the trend before anyone else. You're the guy who comes to the party last, when the others have already drunk the champagne (the first +200%) and are now buying the overpriced leftovers from them at a 73 P/E ratio.

### My conclusion for you:
Vicor (VICR) undoubtedly has ingenious technology and AI power delivery is a real bottleneck. The story is right! But you're buying the absolute peak of the hype here. Your own figures show a pause in profit growth and a massive slump in cash flow for 2026.

This is not an "underestimated energy champion", but a high-risk, completely overbought bet on the years 2027/2028. Let's hope for your sake that the market doesn't lose its patience (and the P/E ratio of over 70) by then.

See you next time when you present us with another value at an all-time high! 😘

@Get_Rich_or_Die_Tryin
•
4
•
imagem de perfil
@Raketentoni There he is!

And of course I would also pick it apart, but: the high net result in 2025 was primarily due to settlement payments from a patent dispute ($45 million), so I'm excluding that as a "real" comparison and development benchmark.

Furthermore, patent power should not be underestimated. There are actually a number of pending disputes there. Personally, I would take a rather double-edged view of this. On the one hand, it can generate potential additional cash flows.

On the other hand, during the FAB ramp-up, a not insignificant share of the result is obviously still hanging on it.🤷🏼‍♂️
•
2
•
imagem de perfil
@Get_Rich_or_Die_Tryin
I'm glad you're taking the hit with humor! But my best man, you didn't just pick apart my analysis, you put the baseball bat directly in my hand for the final blow.

Let's fillet your arguments for a moment:

1. the 45 million boomerang
You're excluding the USD 45 million settlement from 2025? Perfect! Thank you! Because that's exactly what makes my argument even sharper. If the net result in 2025 was artificially inflated by this one-off effect, that means, conversely, that the real, operational core business was even weaker in 2025 than the embellished figures suggest! If you deduct the lawyer millions, your real P/E ratio for the actual product business explodes completely into the stratosphere. So you are buying an operating business that can justify the valuation even less without legal cash injections.

2. the "patent power" as a business model?
You call it "potential additional cash flows". I call it legal roulette. We are looking for quality compounders and real cash machines (Cashflow Quality Formula). A company that sells and scales excellent products. If - as you yourself admit - a "not insignificant proportion of the result" depends on armies of lawyers winning in court, then you haven't put a cash machine in your portfolio, but a law firm with an attached factory.

3. the fab ramp-up
You said it yourself: The fab ramp-up eats up cash, so you need the patent payments to pretty up the numbers. This is exactly the negative free cash flow I was talking about.

My conclusion for you:
We agree that Vicor has an awesome tech positioning. But your own reasoning confirms our AOK analysis 100%: The current valuation (P/E ratio beyond good and evil) is masked by one-offs and held together by lawyers, while the actual operating business can't even deliver the price tag yet.

We are happy to let you go first in this expensive legal adventure. Let us know when Vicor starts earning money with chips again instead of lawsuits - then we'll take another look at the figures! 😘
•
2
•
imagem de perfil
@Raketentoni Simply too cool!

And I'm basically completely with you on the rating. You just have to be imaginative here, which is what you need from time to time.

From a fundamental point of view, of course, nothing (yet).😉 Nevertheless, I don't find them uninteresting due to their technological edge.
•
2
•
imagem de perfil
@Get_Rich_or_Die_Tryin @Raketentoni If I listened to Prompt, I wouldn't have found a company in ten years. And I don't know whether the company will then generate performance
•
2
•
imagem de perfil
@Tenbagger2024 hard fundamental filter. There will be a lot of very solid picks with good returns. But certainly no tenbaggers on one side of the barbell. On the other side, however, there will certainly be some companies that are just as exciting as yours.😉
•
2
•
imagem de perfil
@Get_Rich_or_Die_Tryin @Tenbagger2024 He just has his guidelines. He will rigorously sort out such companies according to my formulas, but he also has the instruction to analyze your texts, to look for errors in argumentation, to compare current figures and operating results of the last 10 years, etc. You have already found a few companies from time to time that he thinks are good. Don't be discouraged. I just invest completely differently, not so speculatively. Mr. Prompt's top priority is to protect my assets 😬💰
•
3
•
imagem de perfil
@Raketentoni hmmm, a self-protection prompt. Not a bad idea to avoid being tempted too often. Do you actually use the same prompt for both of your dumbbell pages? Probably not, right?
•
1
•
imagem de perfil
@Get_Rich_or_Die_Tryin I've given him the freedom to answer as he likes 😬 sometimes cheeky, sometimes nice and sometimes snotty depending on how he sees it 😬 at @Tenbagger2024 he's now cheeky
•
3
•
imagem de perfil
@Get_Rich_or_Die_Tryin but I use it for both, but tell him which side I see the company for. For example, I wanted to record $IREN, he directly said okay for the speculation side, but definitely not for the core side 😬
•
2
•
imagem de perfil
Nice value, but currently too expensive for me. I think in the current market environment (Iran) they will come down again, especially as the interest rate environment is also uncertain. I don't have the dividend to sit it out and I already have enough exposure to the sector. But it's a great shovel manufacturer that can certainly deliver a stable business outside of AI and data centers.
•
2
•
imagem de perfil
@Keineui also think if it goes down again. I will buy more. Because I like the growth rates and margins
•
1
•
My dear. Someone is under power
•
1
•
imagem de perfil
Thanks for the introduction. It doesn't look bad at first glance.

But the second glance is often the decisive one.🤷🏼‍♂️😉

So, let's let the analyst explain in detail what the phase is here (he's not entirely averse to it either, but also mentions risks -> perhaps desirable as an addition to his great ideas😉):

Here is the detailed analysis for Vicor Corporation (VICR), based on the latest available financial data (as at: financial year 2025/Q1 2026).

1. margin profile
Vicor has shown a significant recovery in profitability in FY2025, driven by a patent litigation settlement and strong demand in the AI sector.

2. the moat profile
Vicor operates in a highly specialized niche of power electronics. Its moat is technologically and legally deep:
- Proprietary topology (ChiP & VPD): "Vertical Power Delivery" (VPD) is the gold standard for powering high-end AI accelerators (such as GPUs). The power density (up to 10kW at 48V) is currently difficult to achieve by competitors.
- IP fortress: Vicor is aggressively defending its more than 200 patents. The latest newsflow confirms high license income and won legal disputes, which effectively keeps imitators out of the market or makes them pay.
- Vertical integration: With its own "fab" in the USA, Vicor controls the entire process, which is a massive advantage over fabless competitors in high-performance electronics (quality control).

3. relentlessly honest analysis (analyst style)
Opportunities: "The AI Power Play"
- Scaling AI infrastructure: Vicor is not a shovel vendor for gold miners, but the one who builds the highly efficient engines for the shovels. When data centers become more compact, there is no way around Vicor's modules.
- Automotive (800V): The transition to 800V architectures in e-cars opens up a second mainstay beyond big tech.
- Operational leverage: With increasing capacity utilization of the new production facility in Andover, margins can structurally remain above 50%.
Risks: "The High-Wire Act"
- Cluster risk: Vicor is extremely dependent on a few major design wins (e.g. Nvidia, Google). If a generation is lost, sales collapse.
- Valuation: A P/E ratio of over 70 (TTM) does not forgive mistakes. The share is an "execution story" - any delay in the ramp-up leads to massive sell-offs.
- Legal volatility: A significant portion of 2025 earnings came from a patent settlement ($45m). This is not a recurring operating business and distorts the fundamental strength.

4. newsflow check & outlook
Current newsflow: The market recently celebrated the forecast of a "record year 2026" with a targeted sales run rate of USD 800m. The book-to-bill ratio rose to over 1.2, indicating a full pipeline.
Forecast:
- Short-term (6-12 months): Bullish. The momentum from Q4 2025 is carrying the stock. Short squeezes and analyst upgrades (price targets up to 240 $) dominate the picture.
- Medium-term (1-3 years): Neutral to positive. Success depends on whether Vicor can set the standard for the next generation of AI chips (after Blackwell/Rubin). The competition (Monolithic Power Systems etc.) never sleeps.
- Long term (3+ years): Speculative. Vicor must make the leap from niche player to universal standard for highly efficient power distribution. If it succeeds, Vicor is a potential takeover pearl for semiconductor giants.

A direct comparison shows that Vicor occupies a technological niche elite, while heavyweights such as Infineon and Monolithic Power Systems (MPS) come from sheer mass and broader portfolios.

1. financial & margin comparison (FY 2025)
Vicor is in a league of its own in terms of margins, underlining its technological uniqueness, while MPS stands out for its extreme efficiency in the mass market.

2. market shares in focus: AI Power Delivery
The market for data center power supply is highly fragmented. Vicor has a disproportionately high share of the high-end segment.
- Vicor: Holds an estimated 15-20% in the area of specialized vertical power delivery (VPD) for high-end GPUs. Vicor is often the "first mover" when Nvidia or Google want to set new performance records.
- MPS: The current market leader in AI accelerators (design-win for Nvidia H100/H200). Market share in the server power sector estimated at 30-35 %.
- Infineon: Global market leader in power semiconductors overall (~19 % market share), but currently in a massive race to catch up in the AI data center sector (target: € 1.5 bn sales with AI power by 2026).

3 Technological superiority: the "unfair advantage"
Vicor: The "Factorized Power Architecture" (FPA)
Vicor's superiority lies in one-step voltage conversion. While competitors often have to regulate from 48V to 1V (for the chip) in several stages, Vicor uses current multipliers directly on the processor.
- Advantage: Less space required (footprint), less heat development and extremely low conduction losses.
- Technology gap: Vicor is the only supplier to offer VPD (current comes from below the chip) in series for loads over 1000 amps.
MPS: The "monolithic" integration
MPS manufactures almost everything on a single chip (BCD process).
- Advantage: Unbeatable cost structure and reliability in the medium power range. They are "good enough" for 90 % of applications and significantly cheaper than Vicor.
Infineon: The material ecosystem
Infineon relies on the "breadth of materials" (silicon, silicon carbide (SiC), gallium nitride (GaN)).
- Advantage: They can cover the entire chain from the power grid to the chip (core). Their latest coup: an 800V architecture for data centers in cooperation with Nvidia to increase efficiency at system level (not just at the chip).

4. analysts' verdict: Who will win the race?
Vicor is the "precision tool": When AI models become so large that conventional power supplies physically fail (due to heat or space), Vicor has no alternative. However, its risk is "commoditization": as soon as MPS or Infineon present a solution that offers "80% of the performance at 50% of the cost", Vicor will lose market share.
In the short term (until the end of 2026): Vicor benefits massively from the ramp-up of the next GPU generations as the power consumption per chip (TDP) marches towards 1000W+.

The patent landscape at Vicor is not just "background noise", but a central pillar of the corporate strategy. Vicor uses patents not only for protection, but also as an offensive weapon and source of revenue.
Here is the analysis of the legal fronts between Vicor, MPS and Infineon:

1. Vicor vs. Monolithic Power Systems (MPS): the "war of topologies"
This is the most intense battleground. Vicor accuses MPS (and others) of copying their proprietary FPA (Factorized Power Architecture).
- The core conflict: MPS currently dominates Nvidia's H100/H200 modules with a multi-level architecture. However, Vicor claims that the efficient conversion from 48V to sub-1V is not physically possible without their patented methods (such as the Sacrificial Power Principle) at these current levels.
- The status: Vicor has already achieved partial success before the US International Trade Commission (ITC). An import ban on certain competitor products was on the cards, but was often averted through license payments.
- The risk for MPS: Should Vicor enforce a final ban on the sale of specific power modules, Nvidia would have to change its board design at short notice - a nightmare scenario for the supply chain.

2 Vicor vs Infineon: David vs Goliath
Infineon is a patent giant with tens of thousands of property rights. The dynamics are different here:
- Strategy: Infineon often tries to invalidate Vicor's patents through inter partes reviews (IPR). They attack the root: If the patent is invalid, there is no infringement.
- Cross-licensing: Historically, battles with giants like Infineon often end in cross-licensing agreements. This means: Vicor is allowed to use Infineon technology and Infineon pays Vicor a fee per module sold that uses Vicor IP.
- Danger: Vicor runs the risk of being "sued to death" by the legal department of a group like Infineon (legal warfare), as the legal costs weigh more heavily for the smaller Vicor.

3. analyst assessment: the "patent toll"
Vicor is increasingly acting like a "patent toll booth" for the AI sector.
- The positive: The recent news of a $45 million settlement shows that Vicor is being taken seriously in court. This validates their technological leadership.
- The negative: Investors need to ask themselves: are they buying an innovative hardware company or a law firm with a factory attached? If operating sales of hardware stagnate and only the one-off payments from lawsuits save the EPS (earnings per share), this is a warning signal for the quality of profits.
Short, medium and long-term outlook
- Short term (6 months): High. The expectation of further license deals and dominance in the next GPU generation (VPD design wins) are driving the share price.
- Medium-term (1-3 years): Volatile. The outcome of the major proceedings against MPS will determine whether Vicor controls the market or is relegated to a niche provider.
- Long term (5+ years): Moderate. Patents expire. Vicor must have established the next revolutionary hardware generation (e.g. for quantum computing power) on the market by then in order not to become irrelevant.
•
1
•
imagem de perfil
@Get_Rich_or_Die_Tryin Thank you dear, very comprehensive. And exciting
•
1
•
imagem de perfil
@Tenbagger2024 is simply a fragmented market and can develop in one direction or another for each individual.

But it's basically a great niche player that you've found. The overall profile is nice. And I hope for your sake that they can establish themselves sustainably for chip infrastructure.💪🏻
••
imagem de perfil
@Get_Rich_or_Die_Tryin I think they will also be able to score points with the new technologies. Energy efficiency will remain the big issue. Also with robotics and autonomous driving. The company is very innovative. No risk, no fun. The margins are something for you, but you won't be able to sleep with the share. 🙈😂
•
1
•
imagem de perfil
@Tenbagger2024 to the point, my dear.😅

A little growth has remained and will continue to find its way into my portfolio with the timely ETF switch.

But of course, in the vast majority of cases, these are no longer "no risk, no fun" stocks. Instead, they are rock-solid foundations with good growth prospects.😉
•
1
•
imagem de perfil
@Get_Rich_or_Die_Tryin I also bought first this time. And only made the presentation afterwards. For fear that you and Prompt @Raketentoni would crumble the company again
•
2
•
imagem de perfil
@Tenbagger2024 I didn't.😇 This time the analyst and I were pretty fluffy, so good pick.😁😉
•
1
•
imagem de perfil
@Tenbagger2024 but Mr. Prompt with his iron fundamental glasses has already taken care of the destruction.💥🌋💣
•
1
•
imagem de perfil
@Get_Rich_or_Die_Tryin At Prompt, only the boring companies get through the check. Prompt must have once worked at the tax office
••
imagem de perfil
@Tenbagger2024 boring doesn't have to be bad. That's where our approaches differ fundamentally.😅🤷🏼‍♂️ You won't achieve 10x in a year with such filter criteria, but if that's not the goal? From my point of view, it's all good, to each his own 😁
•
1
•
imagem de perfil
Nice margins. But on $450m. Who is the hyperscaler that brings that to $800m?
••
Participar na conversa