5H·

Company Profile: SBI Holdings

Hello, GQ Community,

I'm popping in again after a long hiatus! ✌️ After quite some time, I'm back today with another company spotlight.


While it feels like half the community is $SOFI (-0,84%) or $NU (+3,11%) the quintessential FinTech company, today I’d like to draw your attention to another absolute heavyweight in the industry. This time, though, we’re traveling to the Land of the Rising Sun! Today, we’re heading to Japan! 🇯🇵


Because what many people don’t even realize is this: While the U.S. and Latin America are celebrating the FinTech hype, a massive capital market revolution is currently underway in Japan—and right at the center of it all is a digital champion that dominates the entire ecosystem.


🏛️ SBI Holdings, Inc. $8473 (-0,7%) : The Japanese financial and FinTech empire of the NISA revolution
attachment

While traditional Japanese megabanks (such as MUFG $8306 (-2,75%) or Sumitomo Mitsui $8053 (-0,53%) ) are weighed down by heavy operational baggage from the branch-based era, founder Yoshitaka Kitao has created Japan’s leading digital financial mega-conglomerate with SBI Holdings $8473 (-0,7%) , Inc., has created Japan’s leading digital financial mega-conglomerate. SBI occupies the most attractive future-oriented sectors of the Japanese capital market: online brokerage (No. 1 in Japan), commercial and digital banks (including SBI Shinsei Bank and SumiShin Net Bank), asset management, venture capital/private equity, as well as crypto-assets and blockchain infrastructure. 

With the launch of the new, government-subsidized, tax-free NISA investment system (Nippon Individual Savings Account), Japan is experiencing a historic shift from savings accounts to stocks and ETFs. SBI is the primary beneficiary and infrastructure leader of this movement. On the Tokyo Stock Exchange (TSE), the stock is trading at around 2,925 JPY in October 2026.


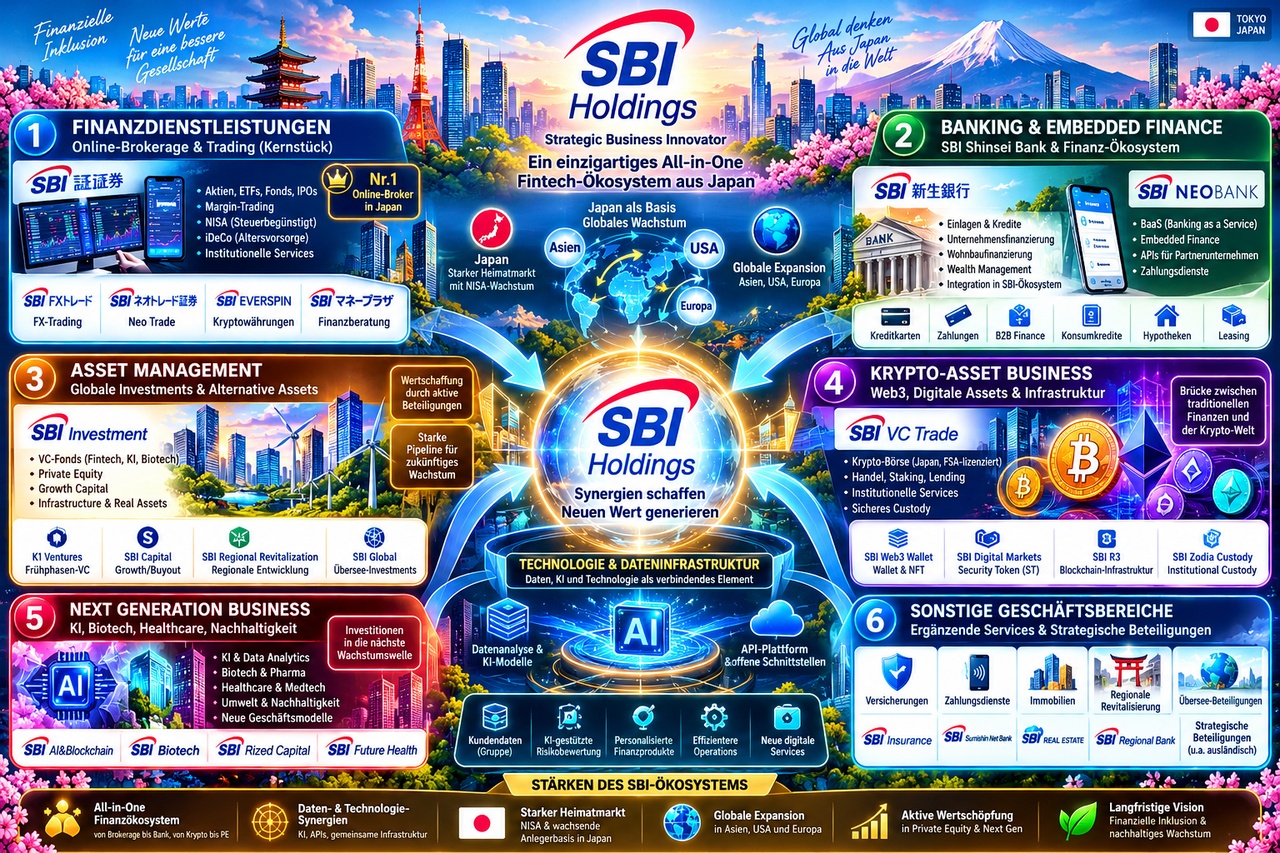
1. The Business Model: Japan’s All-in-One FinTech Flywheel ⚙️🇯🇵💳


SBI $8473 (-0,7%) operates a diversified, highly scalable ecosystem with strong synergies between banking, trading, and investment:

① Online Brokerage & Trading Market Leadership: SBI Securities is by far Japan’s largest online broker. To completely dominate the competition, SBI pioneered the zero-commission model for domestic stocks (“Zero Option”). SBI offsets this through margin trading, foreign exchange transactions, mutual fund management, and integration with its own banking division.


② Banking Powerhouse (SBI Shinsei Bank & SumiShin): Through the full acquisition of Shinsei Bank and strategic partnerships (including the sale of SumiShin shares to NTT DOCOMO to tap into millions of mobile phone customers), SBI combines $8473 (-0,7%) extremely low-cost retail customer deposits with high-margin corporate and consumer lending business.


③ Asset Management, Private Equity & Crypto: SBI $8473 (-0,7%) manages massive VC funds in the global fintech, AI, and tech sectors. In addition, the group operates its own crypto exchanges (SBI VC Trade) and maintains a closely intertwined, long-standing partnership with Ripple (XRP) for cross-border payment networks.
attachment

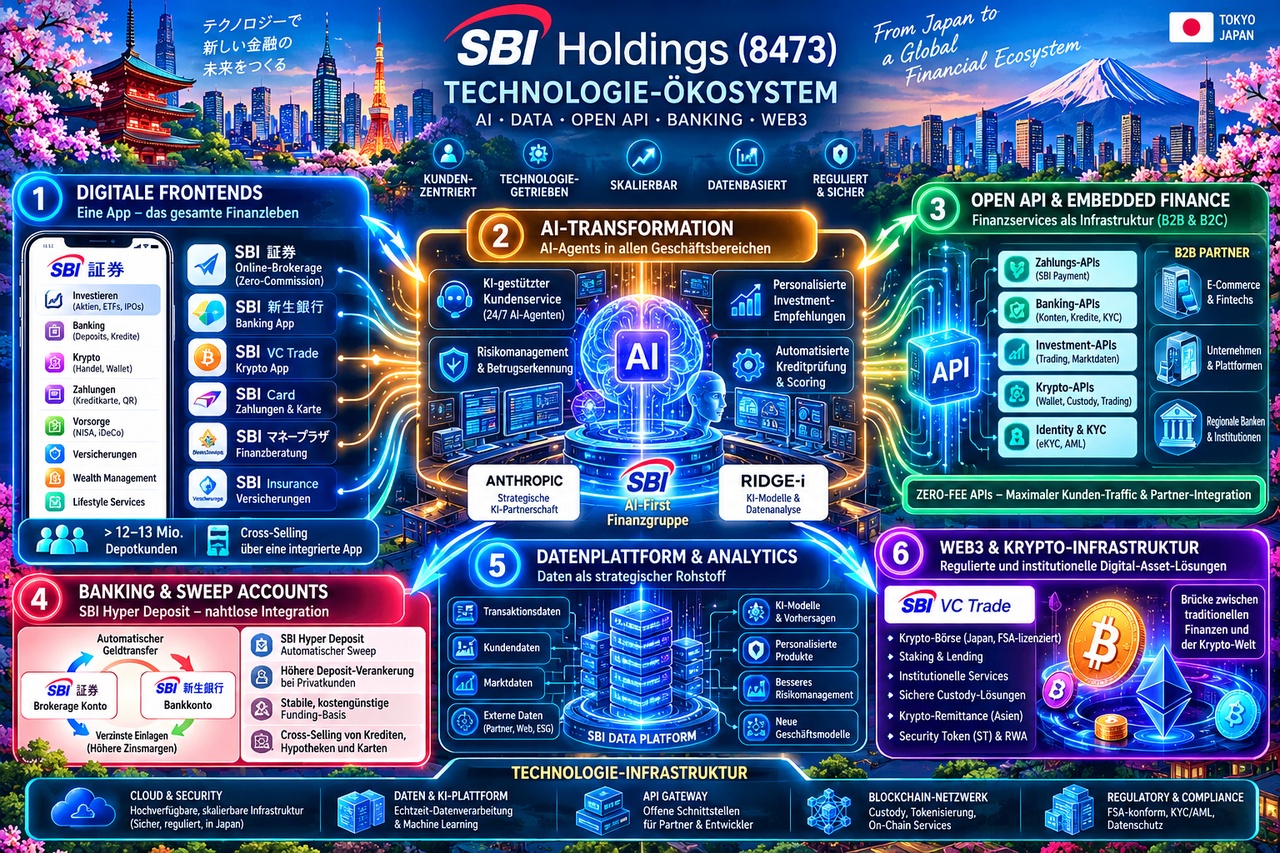
2. The Technology: AI Transformation, Zero-Fee APIs & Web3 Pioneer 🧪📊

SBI’s unique technological selling point is based on maximum customer traffic and technological scalability:


AI-First Financial Group: SBI is the first Japanese financial conglomerate to undertake a comprehensive AI transformation in partnership with Anthropic and Ridge-i to roll out automated financial AI agents in customer service and risk management.


Embedded Banking & Sweep Accounts: Through innovations such as SBI Hyper Deposit, SBI seamlessly links brokerage accounts to the bank’s balance sheet. Funds flow back and forth fully automatically and earn interest, which significantly strengthens deposit retention among retail customers.


Web3 & Crypto Infrastructure: While European TradFi banks are shying away from digital assets, SBI is expanding regulated custody, trading, and remittance solutions for institutional and retail customers in the Asian region.
attachment

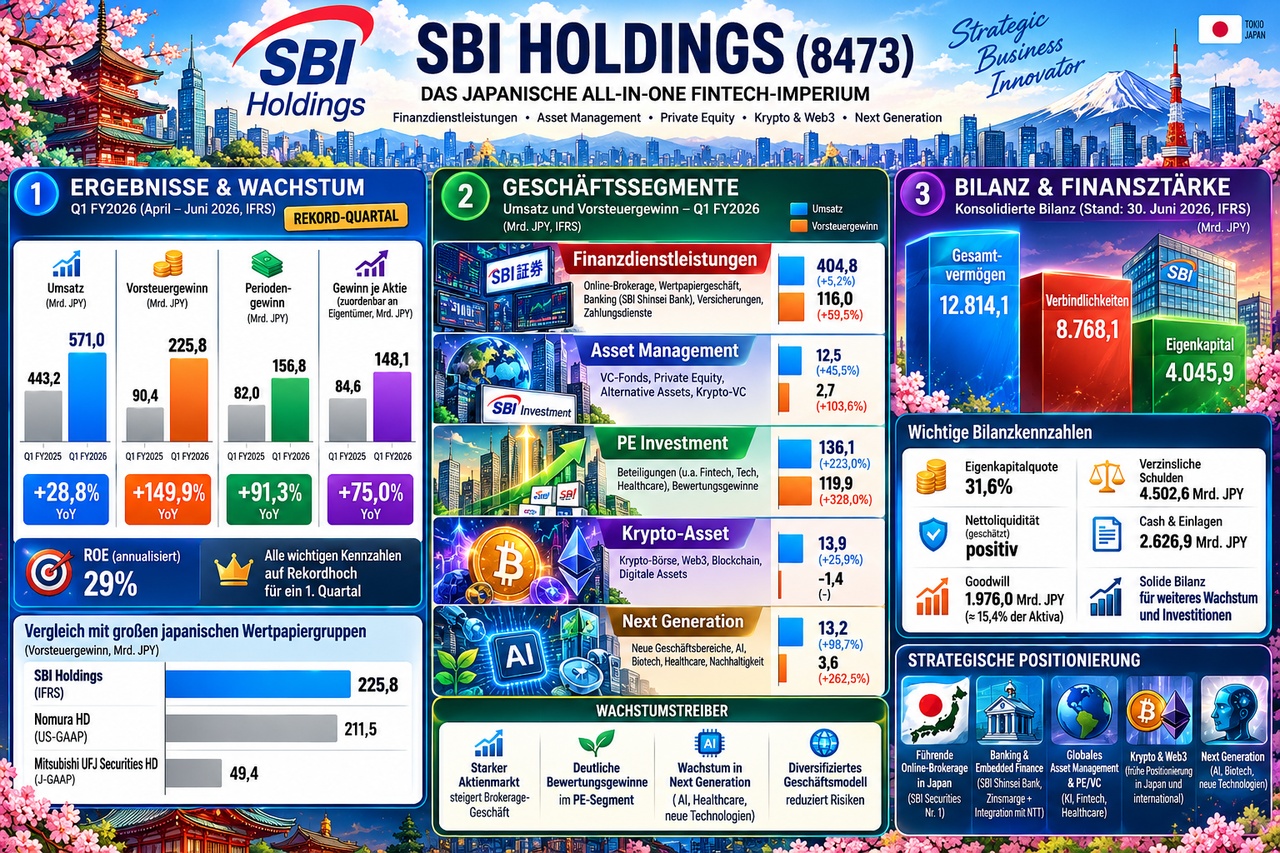
3. Key Figures 📊

Stock Exchange Listing: Listed on the Tokyo Stock Exchange (Prime Market) under the ticker $8473 (-0,7%)

Current price: ~2,925 JPY.

Market capitalization: ~1.93 trillion JPY (~12.5 billion USD / EUR).

Earnings Surge (Q1 FY26): SBI posted record results in the first quarter of FY2026: Pre-tax profit rose by +149.9% year-over-year to 225.8 billion JPY. Net income climbed by +75.0% YoY to 148.1 billion JPY. 

Profitability (ROE): The annualized ROE in this record quarter was >24–29% (the bank’s medium-term target is >15%).

Dividend: Solid dividend policy. Expected dividend yield of ~3.2% to 3.5% (target for FY2026 is ≥ 95–170 JPY per share; interim dividend raised).

Appears extremely undervalued: Trailing P/E ratio ranging from an extremely low ~3.95x to 4.2x. The price-to-book (P/B) ratio is at a favorable ~0.85x to 0.9x (substantial conglomerate discount).
attachment

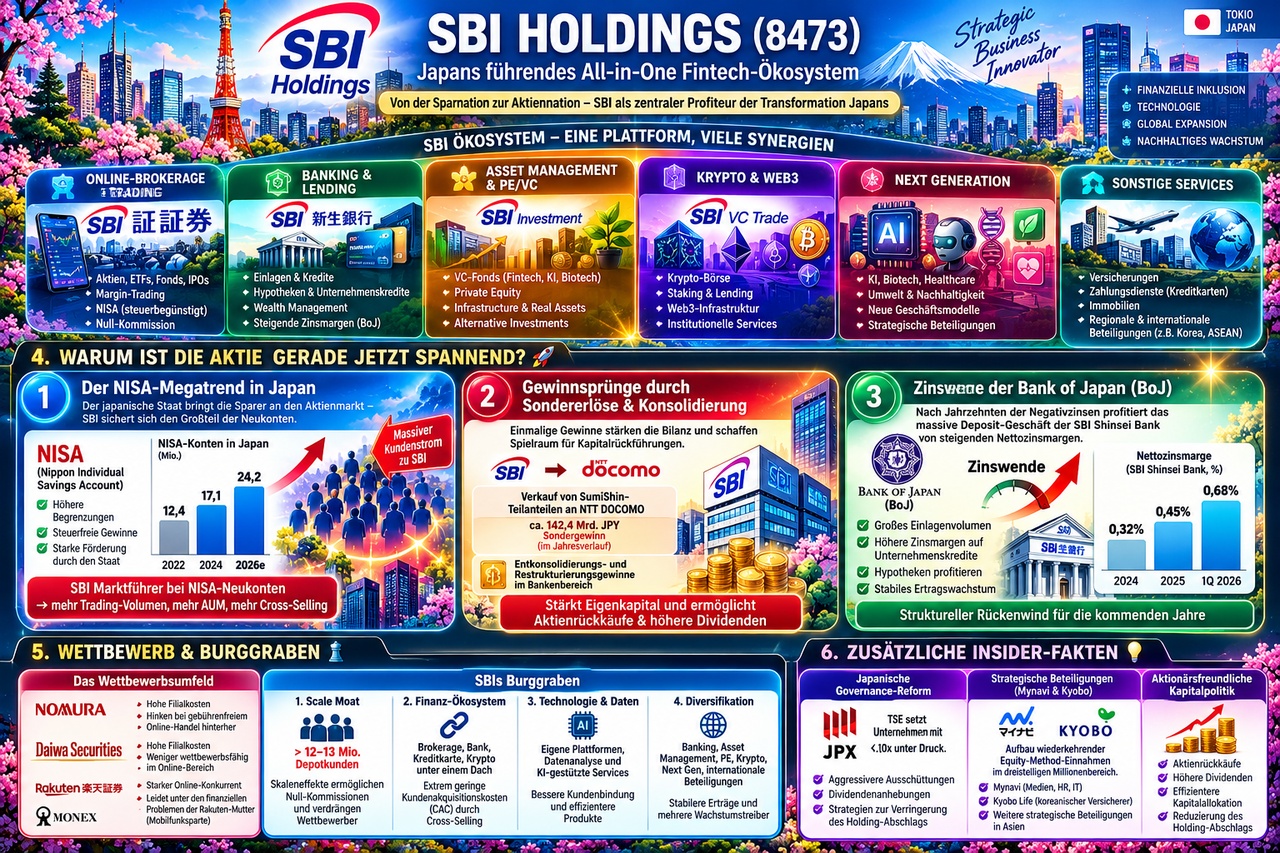
4. Why is this stock particularly exciting right now? 🚀


1. The NISA megatrend in Japan

Through the reformed NISA program, the Japanese government is effectively forcing savers to move their money—which is sitting idle in checking accounts—into the stock market. SBI is securing the lion’s share of these new accounts and AUM.


2. Profit surges driven by one-time gains & consolidation

Sales of SumiShin shares to NTT DOCOMO (approx. 142.4 billion JPY in extraordinary gains over the course of the year), as well as deconsolidation and restructuring gains in the banking sector, are bolstering the balance sheets and generating capital for share buybacks. 


3. Bank of Japan (BoJ) Interest Rate Shift

After decades of negative interest rates, SBI Shinsei Bank’s massive deposit business is benefiting significantly from rising net interest margins on corporate loans and mortgages. 


5. Competition & Moat ♟️

The Environment:

Traditional brokers (Nomura Holdings $8604 (+0,22%) , Daiwa): They have high branch costs and are lagging behind in modern, commission-free online trading. SBI $8473 (-0,7%) has already surpassed Nomura $8604 (+0,22%) in quarterly pre-tax profit.

Online rivals (Rakuten Securities, Monex): Rakuten $5838 (-1,48%) is a strong competitor but suffers from the financial problems of its parent company, Rakuten $4755 (+0,07%) (mobile communications division).

SBI’s competitive moats at a glance:

Network & Economies of Scale (Scale Moat): Over 12–13 million brokerage account holders generate economies of scale that allow SBI to set commissions to zero and erode competitors’ margins.

Financial Ecosystem (Cross-Selling): The integration of brokerage, bank accounts, credit cards, and a crypto exchange under one roof ensures extremely low customer acquisition costs (CAC).


6. Additional Insider Facts💡

Japanese Governance Reform: The Tokyo Stock Exchange is putting pressure on companies trading below their book value (P/B < 1.0x). SBI is responding with more aggressive payouts, dividend increases, and strategies to reduce the holding discount. 

The Mynavi & Kyobo Asset: Through strategic investments (such as in the Korean insurer Kyobo Life or Mynavi), SBI is systematically building recurring equity-method income in the triple-digit millions.
attachment

7. Risks ⚠️

Equity Gain Volatility (Fair Value Accounting): As a holding company, SBI accounts for its massive private equity and VC portfolio at fair value under IFRS. A weak tech or IPO market immediately has a negative impact on net income for the period. ❗️

Cyclical Dependence on Trading Volumes: In bear markets, trading fees and margin loans plummet. ❗️

Crypto & Regulatory Exposure: Activities in the crypto sector (Ripple/XRP) carry a higher regulatory risk and risk of negative media coverage compared to traditional banks. ❗️


8. Conclusion

SBI Holdings is a highly dynamic FinTech and banking empire that appears to be valued at a bargain and is leading the digital transformation of Japan’s financial sector. Despite highly volatile VC results, the company offers substantial rebound and re-rating potential driven by the NISA boom and rising interest rates in Japan. 

Should the global tech sector collapse and SBI’s VC investments lose massive value, while at the same time the Japanese stock market stagnates following the NISA hype, the P/E ratio of ~4x could remain a value trap. The market often punishes complex holding structures with crypto exposure for a long time during crises.


@Get_Rich_or_Die_Tryin
@Tenbagger-Capital
@Dividendenopi
@Raketentoni
@schlimmschlimm
@PikaPika0105
@Multibagger
@Stocktective And, of course, everyone else ✌️

13
7 Comentários

imagem de perfil
The NISA program is so great—I wish we had something like that in Germany, too….

Considering that MUFG and SMFG are saddled with “significant legacy burdens,” their operations are actually going pretty well 😂

Rakuten Securities is actually being held back by its parent company, but Rakuten Bank—which is affected by this—could potentially become more independent in the future (Rakuten currently holds just under 50%).

I think a very relevant competitor you didn’t mention is PayPay. PayPay is a payment platform used by over 70 million Japanese people. The company is part of the SoftBank empire. They also already operate a brokerage firm, though it isn’t that big yet. Nevertheless, PayPay is constantly expanding its banking services and has enormous potential thanks to its massive customer base and powerful owners. SoftBank also operates the country’s third-largest telecommunications group and owns the messaging service LINE, which everyone in the country uses. So, if they want to, they can reach almost every Japanese person. In my opinion, that would be one of the main risks for SBI right now.

But of course, that only applies to the retail business itself. All other financial services behind the scenes (e.g., APIs, VC, etc.) remain attractive, of course. They will certainly continue to perform well. However, the further the NISA program progresses, the fiercer the competition will become in certain areas.
•
2
•
imagem de perfil
@PikaPika0105 This is indeed a very important point that should definitely not be underestimated when considering SBI. The enormous reach of PayPay and LINE in everyday Japanese life, in particular, could create competitive pressure in the long term. 👀
With over 70 million users, PayPay naturally has a massive advantage when it comes to customer acquisition. If they succeed in integrating securities trading and NISA savings even more deeply into their existing ecosystem, that could cost SBI a significant share of the market, especially among younger investors and newcomers. After all, the barrier to entry is extremely low.
However, I’d like to make a slight distinction here. I currently see PayPay primarily as a serious competitor in the area of micro-investing and among casual investors. SBI, on the other hand, continues to hold a significantly stronger position when it comes to larger portfolio volumes, long-term wealth accumulation, and active traders. The question is whether PayPay can convert its enormous user base into correspondingly high assets under management in the long term.
There’s also something else we mustn’t forget about SBI. We’re not just talking about a traditional online broker here. Through SBI Shinsei Bank, its investment business, and its various B2B and crypto activities, the company relies on multiple revenue streams. The shift in Japanese interest rates, in particular, could provide additional momentum for the banking business. That’s why, while I would certainly take the increasing competition from PayPay seriously, I wouldn’t automatically view it as a threat.
For me, the greatest risk actually lies in future growth in the retail and NISA businesses. If PayPay were to gain increasing market share there, one would certainly have to take a more critical look at SBI’s long-term growth expectations.
On the other hand, given its broad portfolio and low valuation, SBI still strikes me as an attractive investment. That said, one must of course also question to what extent this valuation discount is justified by the complex corporate structure.
•
1
•
imagem de perfil
@Aktienhauptmeister I would agree with that
•
1
•
imagem de perfil
Hi there, thanks for the great overview. If I'm reading this correctly, the P/E ratio is rising every year. Those aren't the best conditions for continued performance. What's your take on this?
•
2
•
imagem de perfil
@Tenbagger-Capital I believe that, above all, one must take into account the company’s unique corporate structure and accounting practices. After all, SBI is not just a traditional financial services provider; it also holds an extensive portfolio of private equity and venture capital investments.
The problem is that changes in the value of these investments are sometimes recognized directly in the income statement. In years with successful exits, IPOs, or significant revaluations, reported net income can literally skyrocket as a result, making the P/E ratio appear extremely low at first glance. If these effects disappear in the following year, the P/E ratio rises significantly again, even though the actual operating business may not have changed much at all.
Added to this are major one-time transactions, such as the sale of shares in SumiShin Net Bank in connection with NTT DOCOMO’s investment. Such extraordinary gains can further distort consolidated earnings significantly and don’t exactly make a historical P/E ratio comparison any easier. 😅
That’s why, when it comes to SBI, I personally would focus less on the reported P/E ratio for a single fiscal year and instead try to identify the sustainable earnings power of the individual business segments.
•
2
•
imagem de perfil
Wow...that's really nice! I'll take a closer look. Thanks for the great introduction!
•
1
•
imagem de perfil
Hey, @Aktienhauptmeister! ✌️

SBI sounds like an exciting prospect. You’ve actually convinced me to take a closer look at the company. So, together with Mika, I’ve gone through the numbers and the original reports.

**The company has a lot to offer. However, we need to take off the rose-colored glasses in a few places when it comes to your “bargain” story.** 😬

**1. The P/E ratio of 4: nicely cheap—or just a particularly attractive calculation? 🧐**

Your quarterly figures are correct: **225.8 billion yen in pre-tax profit, up 149.9%, and 148.1 billion yen in profit for SBI shareholders, up 75%.** There’s nothing to quibble about there.

The key point, however, lies in the breakdown: The **private equity segment alone generated 119.9 billion yen in pre-tax profit**. SBI reports **120.3 billion yen from valuation changes and sales of investments** in that segment and explicitly mentions significant valuation gains.

These are legitimate gains and part of the business model. However, they are less reliably repeatable than ongoing interest or management surpluses. And just because an investee company is valued higher doesn’t mean SBI will automatically receive the corresponding amount in its account.

**A P/E ratio of 4 based on extraordinary gains isn’t necessarily a bargain. Sometimes the denominator is just having a particularly good day.** 😉

To determine if something is “a steal,” you’d first have to figure out what SBI consistently earns over a normal market cycle.

**2. When it comes to book value and dividends, the calculator needs a quick reference 📟**

You mention a **P/B ratio of 0.85 to 0.9**. However, with the current book value of around **2,886 yen per share** and your share price of **2,925 yen**, I arrive at approximately **1.01**.

So it’s roughly the book value—not a documented discount of 10 to 15% below it.

A holding discount relative to the value of the individual holdings may still exist. To determine that, however, one would have to value those holdings individually. **A low P/E ratio does not prove this discount.**

Your dividend range of “95–170 yen” also doesn’t match the stated yield range:

**At a price of 2,925 yen, 95 yen represents about 3.25%.
In contrast, 170 yen would yield about 5.81%.**

The official announcement mentioned a **30-yen interim dividend** and a targeted annual level of **at least 95 yen**. The specific total dividend was explicitly left open in this announcement. In addition, the **2:1 stock split in December 2025** must be taken into account.

**The dividend may grow, but the percentage calculation must still hold up.**

**3. Sumishin no longer belongs on your banking shelf 🏦**

There’s a significant error in your description of the company here.

SBI has transferred **its entire stake in Sumishin**. The transaction was already confirmed on **October 2, 2025**. So this wasn’t merely the sale of a small portion of SBI’s stake.

The most recently reported consolidated profit from the sale amounted to **141.6 billion yen**, compared to the originally estimated 142.4 billion yen. This profit was recognized in the fiscal year ending **March 2026**.

The business partnership is expected to continue. **However, a partnership is not the same as an ownership stake.**

The sale generates capital, while at the same time the previous stake is removed from the portfolio. Both factors must be factored into the valuation.

**You can sell a bank. You just shouldn’t continue to count it as part of your own financial empire afterward.** 😅

A key detail is also missing regarding Shinsei: The previous description of a full takeover no longer reflects the current ownership situation. In its 2026 consolidated report, SBI lists Shinsei as a publicly traded subsidiary with a **71.2% stake**. Control remains—but there are also minority shareholders who own a portion of the profits.

**4. When it comes to competition, some of the wrong companies are in the ring 🥊**

Your ticker symbol **8053** belongs to **Sumitomo Corporation**, a trading company. The Sumitomo Mitsui Financial Group you’re referring to has the ticker symbol **8316**. And **5838** is **Rakuten Bank**, not Rakuten Securities.

No big deal, but for a competitive comparison, we should make sure we’re talking about the right company.

SBI’s brokerage scale, on the other hand, is a real plus. Your figure of 12–13 million accounts is actually outdated by now: as of the end of March 2026, there were already **15.825 million securities accounts at the group level**. However, accounts don’t automatically equate to that many different active customers.

The zero-fee program is also called **“ZERO Revolution”**. Rakuten introduced its own equivalent plan at virtually the same time, in early October 2023. Fee-free trading is therefore not an exclusive SBI feature.

Economies of scale and cross-selling make sense. **“Extremely low customer acquisition costs,” however, remains a hypothesis without concrete figures.**

**5. NISA and AI: Real Opportunities, But Please, No Magic Wands 🚀**

The NISA tailwind is real. The expanded system has been in place since **January 2024** and significantly improves the tax advantages for long-term investments.

However, the Japanese government does not **force** anyone to buy stocks. It provides incentives. And that does not necessarily mean a guaranteed surge in profits for SBI.

The partnership with **Anthropic and Ridge-i** is also a positive development. The specific claim, however, is: **“first Japanese financial group with this company-wide Anthropic partnership.”** That’s more specific than “first Japanese financial group with comprehensive AI transformation.”

The announcement describes the introduction, development, and testing of relevant applications. It does not yet deliver a proven productivity or profit advantage.

**An AI partnership is a strategic move. Anthropic doesn’t include a ready-made moat in the welcome package.** 😉

**6. With Ripple, technical risk is on the table 🔐**

The connection is substantial: According to the corporate directory, SBI holds **a 60% stake in SBI Ripple Asia**.

A recent example of technical risk is the recently disclosed XRP Ledger vulnerability. Veria demonstrated a flaw that allowed a manipulated transaction to generate approximately **18.45 trillion XRP**.

The key takeaway: **The vulnerability was fixed in version 3.4.1 on September 25. According to the developer report, there is no evidence of exploitation on public networks.** So, trillions of additional XRP were not actually put into circulation.

This does not prove any concrete damage to SBI. However, it does illustrate why, in addition to regulation, software, trust, and valuation risks are also relevant here.

**7. The remaining arguments also need to be toned down a bit**

Kyobo and Mynavi are real investments. The group report cites approximately **20.4% and 20%, respectively**. However, your earnings figure—“in the hundreds of millions”—still needs to specify the currency and time period to be meaningfully assessed.

The Japanese governance initiative is fundamentally sound. However, it applies to **all companies in the Prime and Standard markets**, regardless of their P/B ratio. That isn’t an automatic driver of share price.

And rising interest rates can help the banking business. However, higher funding costs, credit risks, and potential valuation losses must also be factored in.

**My conclusion:**

You’ve presented an interesting financial conglomerate and have already highlighted key risks. SBI has real strengths in brokerage, banking, and investments.

**Still, the claim that it’s “a steal” goes a step too far for me.** What’s missing is a robust adjustment for extraordinary gains and a current valuation of the individual holdings, including minority interests.

I would therefore examine SBI more closely. I wouldn’t label it a bargain until it’s clear how much of this record profit remains even under less favorable market conditions.

**A low price relative to the latest profit is just one metric. A bargain stock is the result of analysis.**

Best regards
Raketentoni & Mika 🚀
••
Participar na conversa