

Reading time: about 4–5 minutes
In October 2025, $MSFT (+0,51%)
quarterly results that beat consensus estimates across the board. Revenue was better than expected, earnings were better than expected, and yet the stock fell three percent. Azure had gained 26 percent during the quarter; the market had expected about 30 percent, and those four percentage points overshadowed everything else.
In the short term, markets do not price in absolute earnings, but rather deviations from the consensus. This is the mechanism that explains earnings reactions. In the long term, it is indeed the development of cash flows that drives the stock price. But anyone who focuses solely on the long-term perspective and ignores the revision mechanism fails to understand why stocks move the way they do in the meantime.
The analyst consensus serves as the visible reference point here. It is derived from dozens of models that are based on the same public information, the same guidance comments from management, and the same industry data. Their average forms the published expectation. However, it is important not to equate the consensus with the market’s overall expectations. The buy-side—that is, the large fund managers—often has its own internal estimates that deviate from the published consensus. What really moves the price is the deviation from what the market as a whole had expected. The two are often close to each other, but sometimes they are not.
What has puzzled me about this mechanism for years is not the principle itself—that is self-evident. What puzzles me is how slowly the consensus reacts to new information. It is systematically too slow, and there are reasons for this that lie deep within the structure of the analyst profession.
The first problem is called anchoring. Anyone who has made an estimate of $8 in EPS for the next quarter does not start from zero during the next revision, but from $8, and works forward from there. New information is not processed independently, but is always evaluated relative to the existing anchor. This leads to incremental rather than discrete revisions, even when reality would actually justify a much larger jump.
The second problem is career risk. An analyst who is the only one to make a radical upward revision and then gets it wrong faces a personal problem. Someone who is off the mark along with the consensus does not. This asymmetry creates herd behavior: No one is the first; everyone waits for the next data point before venturing further. What is rational at the individual level produces sluggish estimates at the aggregate level.
The result of these two forces is well documented empirically. There is an effect known as post-earnings-announcement drift: After a positive surprise, stocks tend to continue drifting higher for weeks; after a negative surprise, they drift lower accordingly. It is important to clarify: A large portion of the new information is priced in immediately. What is delayed are the analysts’ subsequent revisions—and thus the second and third waves of the market reaction. The effect has weakened over the years, particularly for large, closely watched stocks. For companies with less analyst coverage, I believe this effect remains relevant.
Revision cycles follow a recognizable pattern. In the early phase, the first upgrades occur while the broader consensus remains skeptical. Expectations are low, the valuation is still attractive, and every quarter that beats expectations triggers further revisions. In the middle phase, the consensus has shifted; the revision has become the consensus view, the stock price has risen, and the valuation has increased. In the late phase, revisions are at their peak—which, paradoxically, is the most difficult moment, because expectations are now so high that positive surprises become structurally rarer and the market reacts less sensitively to good news.
$NVDA (-1,6%) That has been the lesson of recent years. In early 2023, the EPS consensus for fiscal year 2024 stood at approximately $3 to $4—the starting point following a painful downturn in the gaming segment. Then came the first data center figures and the first signs of the AI infrastructure boom. One upward revision followed another; quarter after quarter, estimates were exceeded, and quarter after quarter, the consensus lagged behind reality. By the end of fiscal year 2024, actual earnings stood at over $11 per share; the consensus had been revised upward by nearly 200 percent and still hadn’t caught up.
The stock didn’t rise just because earnings were high. Revisions were the key driver; multiple expansion also played a role, as the AI narrative made investors willing to pay more for those earnings. Together, these two factors explain the magnitude of the move. But without the earnings revision cycle—which surprised the consensus quarter after quarter—the narrative alone would not have been enough.
The counterexample is $META (-0,66%) in 2022. At the start of the year, analysts estimated profits in the high double-digit billions; then the cycle reversed. Metaverse investments eroded margins, advertising revenue weakened, and costs rose faster than revenue. Each downward revision triggered the next round of revisions—too small, too slow, in small steps—until the stock price had lost 70 percent of its value. The stock wasn’t valued fairly all at once; it was revised downward further, quarter after quarter.
The turning point in mid-2022 is interesting. Zuckerberg announced layoffs and cost discipline; the first upward revisions came—again hesitantly, again in small steps. Anyone who recognized at that point that the revision cycle was turning had a head start of more than a year over the broad consensus.
What I take from this for my analysis: The direction of earnings revisions is a standalone filter, independent of the absolute valuation. A stock that appears cheap in a negative earnings revision trend is often cheaper than it seems, because the next downward revision is already on the way. Conversely, a stock that appears expensive in an early positive revision phase may have significantly more upside potential than its current valuation suggests.
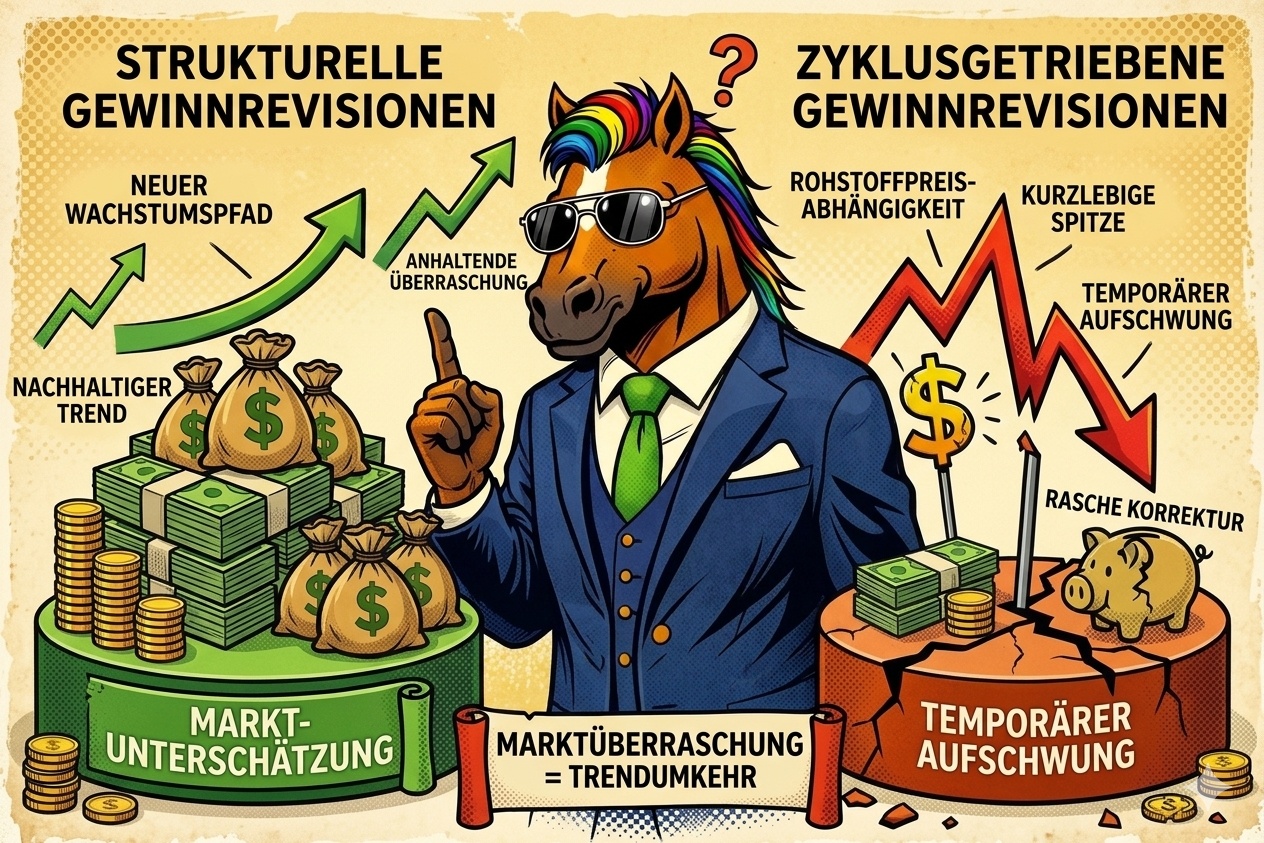
Here, it’s important to make a distinction that is often missing from most discussions. Structural revisions occur when a business model undergoes a fundamental change, as is the case $NVDA (-1,6%) the AI infrastructure boom. They last longer because the extent of the change is harder for the consensus to assess. Cycle-driven revisions follow external factors such as commodity prices, interest rates, or demand cycles. They are shorter-lived and often more predictable because the drivers are easier to isolate. This difference has practical implications for position size and holding period.
This results in an industry where earnings revisions depend almost entirely on a single external factor, where analysts essentially model the commodity price rather than the company itself, and where the question of how to invest differs fundamentally from standard analysis.
In the next article, I’ll take a closer look at exactly that, using the example of $XOM (-2,06%) and the energy sector.


