
In this post, we want to take a closer look at the two companies and carry out a brief analysis of which of the two companies is ultimately more suitable, or whether you should buy both or neither.
In the middle of the analysis, however, time has run out, so I have now gone into more detail on $INTU (+0,6%) in more detail and not at all on Service Now for the time being.
Intuit:
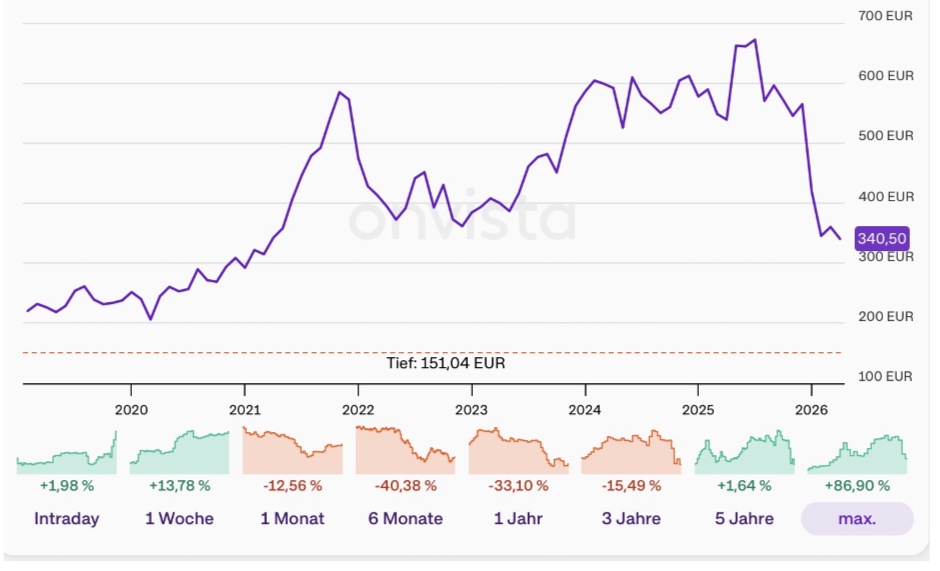
Point 1: Company profile & business model
Intuit is a giant in the field of financial and business software.
- Core brands: TurboTax (tax preparation), QuickBooks (accounting for SMBs), Credit Karma (financial advice) and Mailchimp (marketing automation).
- How they make money: Primarily through subscriptions (SaaS) as well as transaction-based fees (e.g. payment processing in QuickBooks).
- Industry: Application software / FinTech.
Point 2: The moat & market position
Intuit has one of the widest moats in the software sector.
- Moat factors: Extremely high switching costs.
- Future competitive advantage: Intuit massively integrates generative AI ("Intuit Assist") to automate accounting tasks.
- Warning: The biggest threat is the US Internal Revenue Service (IRS), which is working on its own free e-filing systems (Direct File). Should this be massively expanded, TurboTax's core business could come under pressure.
- Market position: Absolute market leader in bookkeeping for SMEs and tax returns for private individuals in the USA.
Score moat:
8 / 10
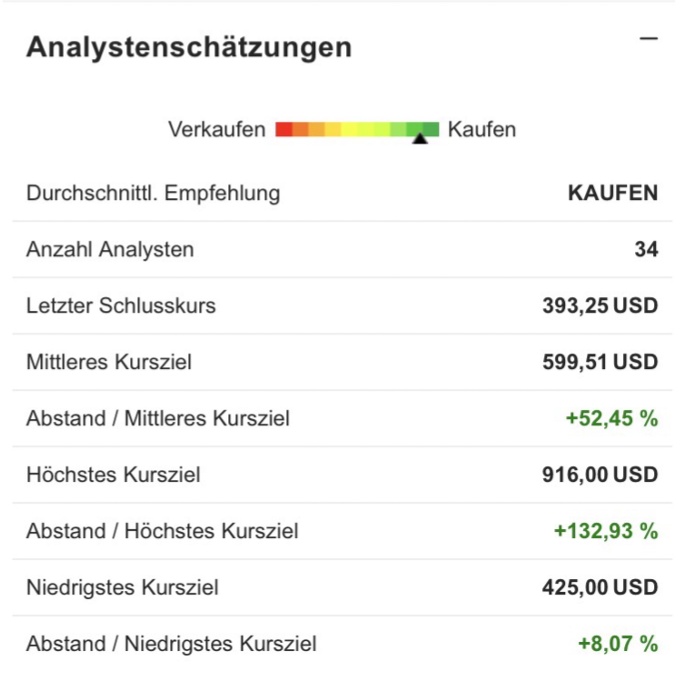
The analysts are also completely optimistic.
Point 3: The figures
- Growth: turnover recently grew by 17%. EPS growth of around 15-20% is forecast for 2026 as a whole.
- Growth score: 9 / 10
- Margins:
- Gross margin: approx. 78.5 %.
- Net margin: currently approx. 21.6 %. Margins are benefiting massively from the scalability of the platform and the switch to subscription models.
- Score margins: 9 / 10
- Debt:
- Debt-to-equity: approx. 0.32.
- Assessment: Debt is very low for a company with this stable cash flow. The balance sheet is extremely solid.
- Debt score: 10/10
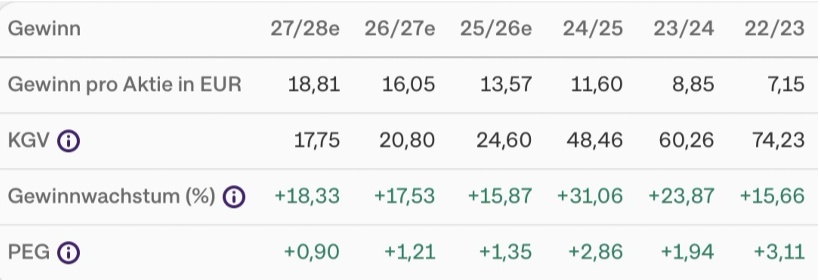
Point 4: Valuation & Peer Group
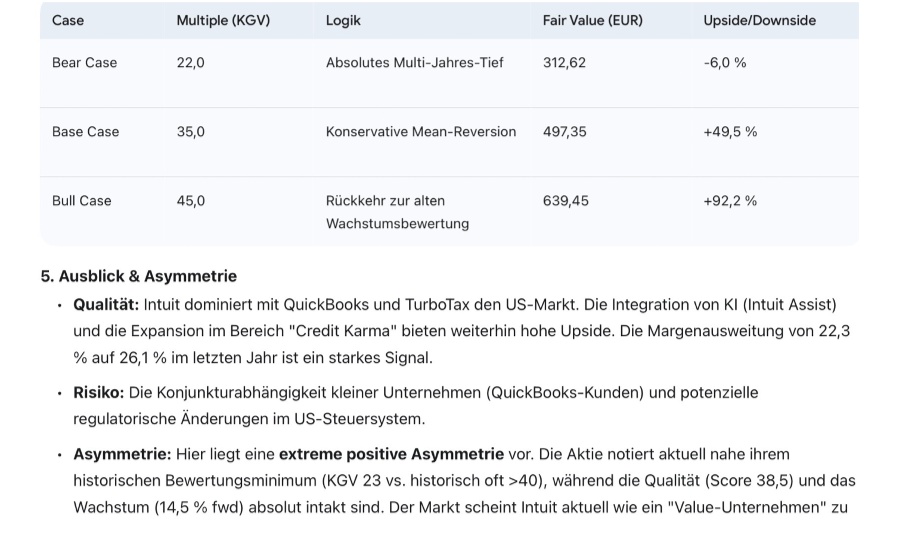
- Current P/E ratio (TTM): approx. 25.1
- Forward P/E ratio (2026): approx. 20.8
- P/E ratio: approx. 5.4
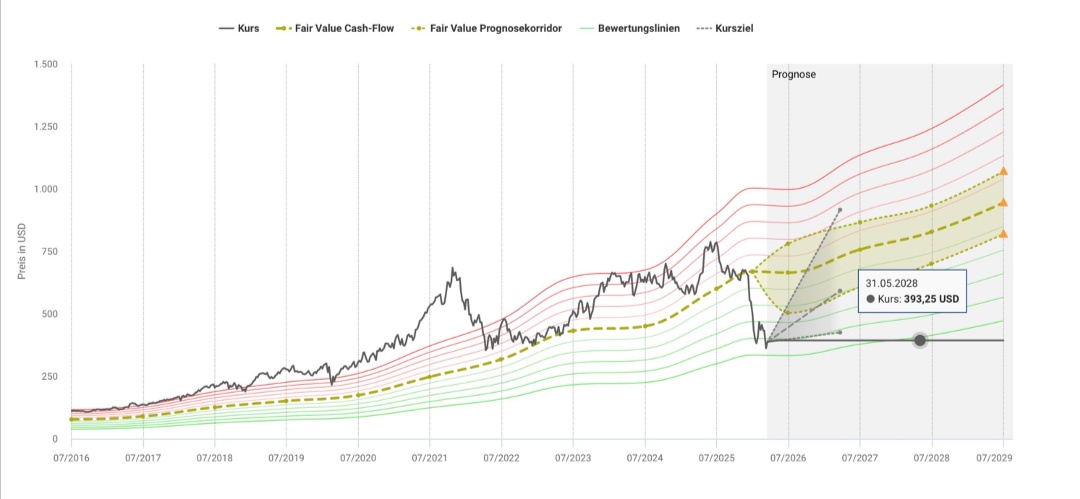
- Historical comparison: The average P/E ratio of the last 5 years was over 50. With a current P/E ratio of approx. 25, the share looks almost cheap from a historical perspective, although growth remains in double digits.
- Peer group: Salesforce (P/E ratio ~24) is currently trading at a similar P/E ratio, while Adobe (P/E ratio ~14) is a further 10 points below.
Score Rating: 9/10
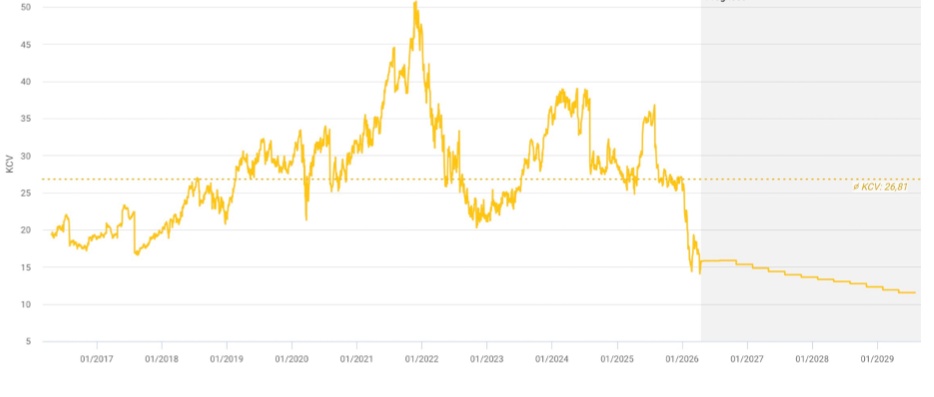
The KCV, i.e. price/cash flow ratio, is shown here in yellow. And here again you can see how the company appears undervalued from this perspective.
Point 6: Future check
The digitalization of small businesses and the use of AI in finance are long-term megatrends. Intuit is ideally positioned here to act as the "financial brain" for millions of customers.
Future score: 9 / 10
The fear of AI:
Intuit no longer just sells software licenses for "brains" but automates complete results (like the completed tax return) for a fee, monetizing the time savings of AI itself. As a certified "gatekeeper" to the tax office, Intuit offers legal certainty and liability that a free AI cannot provide - turning it from an interchangeable tool into an indispensable financial infrastructure. Despite the progress of AI, Intuit's revenue per customer and profit margins (approx. 32%) are currently increasing because customers pay for peace of mind, not for working hours.
Investment judgment:
We have an overall average of 8.85 points out of a total of 10 points. This speaks in favor of a buy. Intuit is an excellent investment at the current price of around EUR 333. The company combines a deep moat with an unusually moderate valuation by its standards (P/E ~25 vs. historical ~50). Despite regulatory risks in the tax business, the dominance in the business software segment (QuickBooks) is so strong that the share fits into almost any portfolio as a defensive growth stock. A clear buy for long-term investors.
What do you think about the company and are you invested? I am not yet.
Are you still interested in an analysis of $NOW (+2,86%) the significantly more expensive player, which is still trading at a high price level despite a sharp fall in the share price (Kgv at almost 60)?
Which company do you think is better Intuit or Service Now
@Tenbagger2024
@Get_Rich_or_Die_Tryin
@Liebesspieler
@Klein-Anleger
@Raketentoni


