
$BAYN (-1,34%) - Just adjusted the quantity again and scaled the position up to its final size. Will it bounce back to its former strength, or will the glyphosate hammer come down? We'll see. 😉
Bayer
Ação
Ação
ISIN: DE000BAY0017
Ticker: BAYN
DE000BAY0017
BAYN
Price
Discussão sobre BAYN
Postos
253
2Semana·
Bayer Stock in 2026: Supreme Court Victory Celebrated, Now the Next Trial — Will Sentiment Shift?
Summary
Sentiment is already waning: Following the Supreme Court victory in June, Bayer’s stock rose to 53.92 EUR by early July, but since the start of a new Roundup trial in Missouri on September 29, they fell by about 10% within a week to approximately EUR 44 and crossed below the 100-day moving average on October 2. The reason lies in the details of the ruling: On June 25, the Supreme Court ruled 7–2 that lawsuits seeking additional warning labels may be barred. In the new lawsuit, three plaintiffs accuse Bayer subsidiary Monsanto of designing Roundup defectively and failing to test it sufficiently—a separate cause of action on which the court did not rule directly. According to Reuters, a total of approximately 65,000 Roundup claims are still pending, and the class-action settlement of up to $7.25 billion continues to await final approval following the September 14 hearing. Operationally, however, Bayer is performing solidly: In the second quarter, EBITDA before special items rose by 1.9% to 2.144 billion EUR, exceeding expectations, and the full-year forecast was confirmed. Analysts have an average price target of 51.65 EUR, about 17% above the current price.
Key points:
New Roundup lawsuit in Missouri since September 29, 2026: Allegations of faulty product design and inadequate testing; the Supreme Court ruled 7–2 in favor of Bayer on June 25, 2026, though the case concerned lawsuits over missing warning labels; approximately 65,000 Roundup claims are still pending (Reuters)Class-action settlement of up to $7.25 billion over up to 21 years: final hearing on September 14, decision pending. Share price: approx. 44 EUR, about 18% below the 52-week high (53.92 EUR), weekly decline of about 10%; 100-day moving average crossed downward on Oct. 2, 2026 (at 44.90 EUR); Q2: EBITDA: 2.144 billion EUR (+1.9%); 2026 full-year forecast confirmed: EBITDA of EUR 9.6 to 10.1 billion; free cash flow in the first half of the year was −EUR 2.7 billion, weighed down by legal settlements totaling EUR 2.5 billion; Analysts: Average price target: 51.65 EUR (62 analysts); JPMorgan: Overweight at 61 EUR; UBS: Buy at 62 EUR. Next quarterly results: November 3, 2026
What are the current key metrics for Bayer stock? (As of October 6, 2026)
Bayer stock is currently trading at approximately 44 EUR, with an expected P/E ratio of around 9.8 based on adjusted earnings and a dividend yield of only about 0.25%.
Key FigureValueDate
Price (XETRA: BAYN)
approx. 44.07 EUR
October 5, 2026
Daily performance
−1.9%
October 5, 2026
Weekly Performance
approx. −10 to −11%
Oct. 2, 2026
52-Week High
53.92 EUR
July 3, 2026
52-Week Low
25.78 EUR
November 7, 2025
Distance from 52-week high
approx. −18%
October 5, 2026
Distance from the 52-week low
approx. +71%
October 5, 2026
100-day moving average
Crossed downward on October 2, 2026 (at 44.90 EUR)
Oct. 2, 2026
Revenue Q2 2026
EUR 10.872 billion (+2.2% on a currency- and portfolio-adjusted basis)
Aug. 4, 2026
EBITDA before special items for Q2 2026
EUR 2.144 billion (+1.9%, above the consensus estimate of approximately EUR 1.94 billion)
August 4, 2026
Adjusted EPS for Q2 2026
EUR 0.95 (−16.7% YoY)
August 4, 2026
Free Cash Flow H1 2026
−EUR 2.7 billion (of which legal payments: EUR 2.5 billion)
August 4, 2026
Net financial debt
EUR 33.6 billion (June 30), year-end forecast: EUR 29–30 billion (previously EUR 32–33 billion)
August 4, 2026
Full-Year Forecast 2026
EBITDA: 9.6–10.1 billion EUR · Core earnings per share: 4.30–4.90 EUR · Revenue: 45–47 billion EUR
Confirmed Aug. 4, 2026
P/E ratio 2026 (expected, adjusted consensus EPS of EUR 4.51)
approx. 9.8
Oct. 5, 2026
P/E ratio (reported earnings, last 12 months)
negative (−10.06)
Oct. 2026
Dividend 2025 / expected 2026
0.11 EUR / 0.11 EUR
—
Dividend yield
approx. 0.25%
Oct. 5, 2026
Roundup: Pending claims
approx. 65,000 (according to Reuters)
Oct. 1, 2026
Roundup class-action settlement
up to $7.25 billion over up to 21 years; final decision pending
Hearing Sept. 14, 2026
New Roundup lawsuit
Missouri, three plaintiffs, product design and testing
Since September 29, 2026
Supreme Court (Durnell case)
7–2 in favor of Bayer
June 25, 2026
WKN / ISIN / Ticker
BAY001 / DE000BAY0017 / BAYN
—
Analysts’ Average Price Target
51.65 EUR (62 analysts, range 23–70 EUR)
Oct. 2026
JPMorgan / UBS
Overweight 61 EUR / Buy 62 EUR
Sept./Oct. 2026
Next Quarterly Results (Q3)
November 3, 2026
—
What news is currently driving Bayer stock?
The most important news regarding Bayer stock from the past few weeks at a glance:
Currently, Bayer stock is primarily being driven by the new Roundup lawsuit in Missouri, the pending approval of the $7.25 billion class-action settlement, and the quarterly earnings report on November 3.
Date | News | Details | Assessment
October 5, 2026
Stock continues to fall to approx. 44 EUR
Bayer stock lost about 1.9% on Monday and was among the DAX’s biggest losers. At the same time, it was announced that Bayer plans to invest over $2 billion in a new U.S. facility in Ohio—a sign of long-term confidence in the U.S. market, though this did not provide short-term support for the stock price.
Bearish
October 2, 2026
100-day moving average crossed downward
Pullback to 44.90 EUR—the stock falls below the 100-day moving average and ends the week down about 10%. The 50-day moving average at approximately 48.60 EUR is thus well above the current price.
Bearish
October 1, 2026
JPMorgan confirms “Overweight” rating, warns about Q3
JPMorgan maintains its “Overweight” rating on Bayer with a price target of 61 EUR, but considers expectations for the third quarter to be too high due to timing effects in the agricultural business.
Mixed
September 29, 2026
New Roundup trial begins in Missouri
Three plaintiffs accuse Bayer subsidiary Monsanto of designing Roundup defectively and failing to test it sufficiently. The basis of the lawsuit differs from the warning label lawsuits on which the Supreme Court ruled in June. The stock falls 3.78% to 48.88 EUR on this day.
Key
September 29, 2026
Patent Dispute Against BioNTech, Pfizer, and Moderna
Bayer is suing BioNTech, Pfizer, and Moderna in court—another legal battleground, but this time with Bayer in the role of the plaintiff.
Neutral
September 17, 2026
FDA Approval for Kerendia for Type 1 Diabetes
The U.S. Food and Drug Administration (FDA) grants approval for Kerendia for type 1 diabetes—the stock rises and bolsters the pharmaceutical division, which had recently suffered from declining sales of Eylea.
Bullish
September 14, 2026
Final Hearing on Class-Action Settlement
A hearing is held in a Missouri court to seek final approval of the Roundup class-action settlement worth up to $7.25 billion. A final decision is still pending.
Pending
August 4, 2026
Q2: EBITDA Exceeds Expectations, Forecast Confirmed
EBITDA before special items up 1.9% to EUR 2.144 billion; Crop Science up 30.2%. Full-year forecast confirmed; net financial debt is expected to decline to between 29 and 30 billion EUR by year-end. Free cash flow remained negative at −371 million EUR for the quarter.
Bullish
July 3, 2026
52-week high at EUR 53.92
The stock reaches its annual high, about a week after the Supreme Court ruling—the starting point of the correction that has been underway since then.
Historical
June 25, 2026
Supreme Court rules 7–2 in favor of Bayer
In the Durnell case, the highest U.S. court rules that lawsuits seeking additional warning labels may be barred under the laws of individual states. This removes a significant portion of the legal uncertainty, and the stock rises sharply.
Very Bullish
What does Bayer do—and how exactly does the company make money?
Company Description
Bayer AG The company generates revenue from crop protection and seeds, prescription drugs, and over-the-counter health products. Bayer AG (ISIN: DE000BAY0017, WKN: BAY001), headquartered in Leverkusen, was founded in 1863 and is listed on the DAX. With the acquisition of Monsanto in 2018, the seed and glyphosate businesses were added to the group, but so was the Roundup legal risk, which continues to shape the stock to this day.
The three divisions—and how Bayer actually makes money:
Crop Science: Seeds, crop protection products, and digital solutions for farmers, including glyphosate-based herbicides such as Roundup. Generates revenue through sales to farmers and distributors. In the first half of 2026, revenue grew by 5.5% with an EBITDA margin of 31%. Pharmaceuticals: Prescription drugs, including the cancer drug Nubeqa (€820 million in revenue in the second quarter; prior year: €546 million) and Kerendia, which received FDA approval for type 1 diabetes in September. Revenue is generated primarily from patented drugs, which is why expiring patents—such as those for Eylea—represent the key risk. Consumer Health: Over-the-counter health products sold in retail stores. EBITDA in the second quarter was EUR 319 million (−3.6%)
The extent to which a pharmaceutical company with a stellar core business can be held back by legal and antitrust disputes is also illustrated by Novo Nordisk Aktie: Here, too, it’s not just the balance sheet but also disputes outside the lab that determine market sentiment.
Fundamental Analysis: How Undervalued Is the Bayer Stock Really?
Fundamental Analysis (as of October 6, 2026)
Partially undervalued: Operationally, Bayer is solidly positioned, but legal risk and cash flow justify a significant valuation discount.
Valuation in the Context of Legal Risk: Based on adjusted earnings per share (2026 consensus: 4.51 EUR, Group forecast: 4.30 to 4.90 EUR), the P/E ratio stands at around 9 to 10. By contrast, reported earnings for the last twelve months are negative due to legal costs and one-time charges. Depending on which earnings metric you use, the stock therefore appears either like a bargain or a money-loser. It is precisely this gap between adjusted and reported earnings that represents the cost of the Roundup complex. The dividend of 0.11 EUR per share (yield approx. 0.25%) also makes Bayer a pure turnaround investment with no dividend cushion.
Margin Performance and Segments: Crop Science is driving the group: EBITDA rose by 30.2% to EUR 902 million in the second quarter; in the first half of the year, the EBITDA margin stood at 31%. In the Pharmaceuticals division, revenue remained at the prior-year level, while earnings were lower: Nubeqa is growing strongly, while Eylea revenue fell by 27% due to biosimilars. Consumer Health delivered EBITDA of EUR 319 million (−3.6%). Adjusted earnings per share fell by 16.7% to EUR 0.95 in the second quarter, despite the rise in EBITDA.
Cash Flow, Debt, and Legal Costs: Free cash flow for the first half of the year was −2.7 billion EUR, weighed down by litigation payments of 2.5 billion EUR. Net financial debt stood at EUR 33.6 billion at mid-year; Bayer now expects it to be between EUR 29 and 30 billion by year-end, down from the previous forecast of EUR 32 to 33 billion. The company has demonstrated over the years Deutsche Bank Aktie demonstrated over the years: Investor confidence returned only after the legacy issues had been resolved.
The legal risk operates on two levels: On the first level, lawsuits alleging a lack of warning labels have lost their impact following the Supreme Court ruling of June 25. On the second level are lawsuits regarding product design and testing, such as in the current trial, as well as the class-action settlement of up to $7.25 billion, which is still awaiting final approval. Bayer denies any link between Roundup and cancer and points to the U.S. Environmental Protection Agency (EPA), which has so far classified glyphosate as “probably not carcinogenic.” A reevaluation is expected to be completed by the end of 2026.
Conclusion of the fundamental analysis: Operating performance justifies a higher valuation, but uncertainty regarding the number and amount of future legal costs is keeping it down. Only once the settlement and subsequent lawsuits make the costs tangible is the discount likely to shrink.
Earnings and Free Cash Flow Trends for Bayer Stock in 2026 (as of Oct. 6, 2026) – Source: Aktienfinder / Christian Lill
Bayer Stock: Price Targets and Forecast for 2026
How is the Bayer stock price performing? (As of October 6, 2026)
According to 62 analysts, the average price target for Bayer stock is 51.65 EUR, about 17% above the current price of approximately 44 EUR, with an extremely wide range of 23 to 70 EUR. The group’s 2026 forecast calls for adjusted EBITDA of 9.6 to 10.1 billion EUR and core earnings per share of 4.30 to 4.90 EUR. JPMorgan (Overweight, 61 EUR) and UBS (Buy, 62 EUR) are the most bullish on the stock, but warn that expectations for the third quarter may be too high.
The stock’s price performance shows just how heavily it is influenced by legal news: From its 52-week low of 25.78 EUR (November 7, 2025), it rose to its annual high of 53.92 EUR on July 3, shortly after the Supreme Court ruling. Since then, it has lost about 18%. Before the hearing on the class-action settlement on September 14, the stock price rose again, but on September 29—the start of the new trial—the stock fell 3.78% to EUR 48.88, and within a week, the loss totaled about 10%. On October 2, it crossed below the 100-day moving average; it is currently trading at approximately 44.07 EUR. You’re familiar with this pattern from the Rheinmetall Aktie: The numbers are improving, yet the price is falling anyway because the market doesn’t focus on what has happened, but on what might still happen.
Key price levels:
52-week high: 53.92 EUR (July 3, 2026)52-week low: 25.78 EUR (November 7, 2025)Current price: approx. 44.07 EUR (October 5, 2026)100-day moving average: 44.90 EUR — crossed downward on Oct. 2First resistance: approx. 50.20 WURSecond resistance: 53.92 EUR (annual high)Analysts’ price targets: Ø 51.65 EUR, JPMorgan 61 EUR, UBS 62 EURCritical support level: A drop below the psychological threshold of 40 EUR would significantly weaken the recovery that began in fall 2025
Technical Analysis:
Bayer shares have recently come under heavy pressure due to the news. The stock hit a hard resistance level at around 50.20 EUR. Nevertheless, buying opportunities continue to outweigh selling pressure as long as Bayer trades above 40.50 EUR. Incidentally, that would be an ideal buying level given the current price. Breaking through the 50.20 EUR barrier, on the other hand, would immediately trigger a procyclical buy signal, pushing the price into the 56.60–61.40 EUR range.
Bayer Stock Price Targets and Forecast for 2026 (as of Oct. 6, 2026) – Source: Stock3 / Christian Lill
Conclusion: Buy, sell, or hold Bayer stock?
My Assessment: Buy
Is sentiment shifting? It’s already wavering, but the fundamentals remain strong: Bayer is delivering solid operating results, the forecast stands, and the Supreme Court victory remains a true milestone. However, the new Missouri lawsuit shows that the June victory did not resolve every cause of action, and with approximately 65,000 pending claims, negative free cash flow, and a settlement that has not yet been approved, legal risk remains the number one pricing factor. The Coinbase Aktie: There, regulators decide; here, judges do.
Investors who believe in the fundamentals of the agricultural and pharmaceutical businesses and view the legal risk as limited will find an entry point here about 18% below the annual high, with an expected P/E ratio of less than 10 and analyst targets well above the current price. Those who want to play it safe should definitely wait for the Missouri court’s decision on the class-action settlement, the outcome of the new trial, and the quarterly earnings report on November 3.
✅ Opportunities
⚠️ Risks
- Supreme Court victory (7–2) limits lawsuits over missing warning labels
- Q2 EBITDA +1.9% above consensus; full-year forecast confirmed
- Crop Science performs strongly: EBITDA +30.2%, margin 31% in the first half of the year
- Nubeqa grows to EUR 820 million in quarterly revenue; FDA approval for Kerendia for type 1 diabetes
- Net debt is expected to fall to EUR 29–30 billion by year-end
- Average price target of EUR 51.65 is about 17% above the current price; P/E ratio below 10
- New process for product design and testing, not covered by the Supreme Court ruling
- Approximately 65,000 Roundup claims pending; approval of the $7.25 billion settlement is pending
- Free cash flow in the first half of the year was −2.7 billion EUR; legal settlements totaled 2.5 billion EUR
- Crossed below the 100-day moving average on Oct. 2; weekly decline of about 10%
- Eylea sales decline due to biosimilars; expiring patents weigh on the pharmaceutical division
- Analyst price targets ranging from 23 to 70 EUR reflect extreme valuation uncertainty
FAQ: Frequently Asked Questions About Bayer Stock
Is the Bayer stock a buy in 2026?
Analysts see an average upside potential of about 17% (average price target of 51.65 EUR based on 62 analysts); JPMorgan (Overweight, 61 EUR) and UBS (Buy, 62 EUR) are positive. Based on adjusted earnings, the stock is attractively valued at a P/E ratio of around 9.8. However, this is offset by a negative free cash flow of 2.7 billion EUR in the first half of the year and approximately 65,000 pending Roundup claims; legal risk remains the decisive factor.
Why has Bayer’s stock price fallen recently?
A new Roundup trial has been underway in Missouri since September 29, in which plaintiffs accuse Bayer of defective product design and insufficient testing. The Supreme Court ruling of June 25 does not directly address these claims. The stock fell by about 10% within a week to approximately 44 EUR and crossed below the 100-day moving average on October 2.
What is the price target for Bayer stock?
The average price target is EUR 51.65 (62 analysts, range EUR 23 to 70), which is about 17% above the current price of approximately EUR 44. JPMorgan cites EUR 61, and UBS cites EUR 62.
When will Bayer release its next earnings report?
Bayer will release its next quarterly results on November 3, 2026. The company last reported on August 4: EBITDA before special items of EUR 2.144 billion in the second quarter and a confirmed full-year forecast. JPMorgan considers the expectations for the third quarter to be too high due to timing effects in the agricultural business.
How much is Bayer’s dividend?
Bayer paid a dividend of 0.11 EUR per share for fiscal year 2025; analysts also expect 0.11 EUR for 2026. At a share price of approximately 44 EUR, this corresponds to a dividend yield of around 0.25%.
How does Bayer make money?
Bayer generates its revenue through three divisions: Crop Science (seeds and crop protection), Pharmaceuticals (prescription drugs such as Nubeqa, with quarterly revenue of 820 million EUR), and Consumer Health (over-the-counter health products). In the first half of 2026, the company generated EUR 24.3 billion in revenue and EUR 6.6 billion in EBITDA before special items.
What is the new Roundup lawsuit against Bayer about?
Three plaintiffs accuse Bayer’s subsidiary Monsanto of designing Roundup defectively and failing to test it sufficiently before its market launch. This differs from the “failure-to-warn” lawsuits, in which the Supreme Court ruled 7–2 in Bayer’s favor on June 25. Bayer denies the allegations.
How many Roundup lawsuits are still pending?
According to Reuters, approximately 65,000 Roundup-related claims are still pending. A class-action settlement of up to $7.25 billion, spread over up to 21 years, is expected to resolve a large portion of them. The final decision by the Missouri court following the September 14 hearing is still pending.
Do you think the next trial will have a major impact on the $BAYN (-1,34%) stock?
22

1Mês·
Portfolio Overview
Hi everyone,
I often read posts here where people ask for feedback, but the story behind them is missing. That’s why today I’d like to share my own portfolio—and my story—in a completely transparent way.
A little about me:
I’m 31 years old and have been active on GQ for quite some time. My current net worth of just under 1.28 million euros is the result of my own hard work. Even as a child, I would occasionally try out potentially profitable business ideas on the side to earn some money—and six years ago, I took the plunge into self-employment.
I now have two companies in different industries. It became clear to me quite early on that I needed a high, recurring active income if I wanted to build up a certain level of wealth, so I left my full-time job fairly early on.
For the next 12 months, I’m planning on a monthly income of approximately 30,000 euros. In addition, I naturally have recurring income, which can fluctuate up or down over the long term.
My goal is to continue growing this wealth prudently so that I can eventually live entirely off the dividends. Currently, for tax reasons, I hold portions of two stocks ($MSFT (-1,87%) and $NOVO B (+1%) ) are held as individual positions in my holding account, and the rest is held in my personal account.
My Strategy and the Core of the Portfolio
I follow a classic core-satellite approach. The core—which I intend to use later as a kind of pension substitute—consists of two ETFs: the $HMWO (-0,98%) and the $QQQ. (-2,81%) I’m aware that these two holdings overlap; I continue to contribute to both monthly via a savings plan.
The individual stocks and my problem children
When it comes to individual stocks, I look for a combination of long-term trends and reliable cash flow. On the one hand, I deliberately overweight tech stocks and future classics such as $MSFT (-1,87%) , $GOOGL (-3,13%) , $NVDA (-4,48%) , $META (-11,25%) , $AMZN (-4,41%) and $AAPL (+1,46%) , because I am firmly convinced that these industries will continue to perform well in the coming years.
For my dividend strategy and the necessary cash flow, I’ve invested in quality stocks such as $ALV (-0,24%) , $MUV2, $NOVO B (+1%) and $UNH (+2,16%) in my portfolio. This is complemented by classic dividend-paying stocks such as $BATS (+2,42%) , $SIE (-3,48%) , $ARCC (+2,13%) and $O (+2,86%).
But let’s be honest: values like $MPW (+3,15%)
$PYPL (+0,27%) , $BAYN (-1,34%) or gambling $LILM aren’t performing at all as once hoped.
In the crypto sector, $BTC (-3,99%) as the largest holding, along with a small amount of $SOL (-4,53%) and $XRP (-5,98%) the whole thing—in the future, I’ll consolidate everything into the position $BTC (-3,99%) and add a little $4GLD (-2,67%) to it.
What’s Next
At the end of this month, I’m expecting a large incoming payment of around 50,000 euros. I’d like to split the amount and invest it both in the $HMWO (-0,98%) as well as specifically into my dividend stocks to further strengthen the foundation.
The goal is to reach a portfolio value of 1.5 million by the end of the year.
Feel free to share your thoughts—I look forward to the discussion :-)
27Posições
€ 1.280.261,12
30,94%
125125
76 Comentários
D.S.@Crash-Propheteus
1Mês
•
6060
•Ver todas as 6 restantes respostas

1Mês·
2 year review
What do you think of my portfolio performance for the last 2 years?
$KO (+2,95%)
$VWRL (-1,17%)
$VUSA (-1,01%)
$VEUR (-0,72%)
$VOW (+0,4%)
$ENI (-0,25%)
$BAYN (-1,34%)
$INTC (-8,92%)
$SAN (+2,1%)
$FCT (-1,14%)
$SL (-1,91%)
$ISP (-3,56%)
$SHEL (+0,55%)
$LDO (+0,65%)
$QBTS (-4,32%)
21Posições
19,25%


1Mês·
Zoetis—A Countercyclical Opportunity or a Crisis?
Hi, some of you have already drawn some attention to the stock of $ZTS (+2,98%) .
Profile:
$ZTS (+2,98%) is a global animal health company. In 2013, it was $PFE (+2,01%) and has been independent ever since.
The company’s focus is entirely on the animal health sector—this is where it generates its revenue through the development, manufacture, and distribution of pharmaceuticals, diagnostics, vaccines, and genetic tests.
Strictly speaking, the Animal Health division is divided into the companion animal segment—such as dogs, cats, etc.—and the livestock segment—such as cattle, sheep, and similar animals.
Zoetis generates about 70% of its revenue from the companion animal market.
This is important because, unlike the livestock market, the pet market exhibits higher growth momentum due to the humanization of pets —Private individuals are more willing to buy medications here when their pet is unwell than a farmer who has more than 2,500 head of cattle and is struggling with regulations, meat prices, and so on.
Risk: But there is also a high risk here—due to the humanization of pets, a company and its products can lose customer trust more quickly and permanently if they do not help or, worse yet, lead to complications. And this is exactly what is alleged to have happened with Zoetis’s medications!
Zoetis has faced strong criticism for failing to provide sufficient warnings about the side effects of Librela and Solensia. These side effects reportedly led, in some cases, to severe side effects in the animals. Furthermore, shareholders have filed lawsuits because management communicated the loss of market share too late and not thoroughly enough. In addition, the world’s leading regulatory agencies (the FDA and EMA) have tightened their oversight—anyone familiar with the pharmaceutical sector knows that this signals trouble.
The consequences are clearly felt—veterinarians are prescribing the affected medications much more cautiously, which is hindering growth and benefiting competitors such as $ELAN (+0,75%) , $MRK (-0,35%) and Boehringer Ingelheim.
Compounding these problems is persistent inflation, which means that consumers can no longer afford—or are unwilling to pay for—expensive premium drugs and are turning to cheaper generics.
Opportunity/Risk:
Zoetis remains an absolute heavyweight in the animal health industry and the undisputed number one.
In the past, the company has not only outperformed the MSCI World but has even outperformed the Nasdaq at times.
In a long-term comparison, however, the stock price is currently even below the growth rate of the Euro Stoxx 50. This is also reflected in the P/E ratio—where a value of 30–35 used to be the norm for years, it now stands at 12, making it an absolute outlier. At the same time, Zoetis’s other business operations are actually very robust. Zoetis’s payout ratio currently stands at about 33%, which means the company still has more than enough cash available for research, dividend increases, and potential reserves for lost lawsuits.
One factor, however, weighs heavily—the loss of customer trust!
This is one of the most critical issues in the pharmaceutical sector that can become a long-term problem.
Consider, for instance, the stories surrounding Purdue Pharma (the OxyContin scandal), Mallinckrodt & Endo International, $BAYN (-1,34%) (the glyphosate/Monsanto acquisition or the Lipobay scandal), $MRK (-0,35%) (the Vioxx scandal), and worst of all: Thomae with its product Contergan.
Although these examples come from human medicine, I would like to remind you once again of the humanization of pets and the share of Zoetis’s revenue that this market represents.
Conclusion:
A current investment in Zoetis is weighed down by many potential future problems, but could also pay off due to the enormous discount if $ZTS (+2,98%) it can ward off the lawsuits and manage to regain the trust of shareholders and, above all, customers. A turnaround bet, so to speak.
Note:
I am not personally invested in this stock and do not intend to be—but that’s more because I’m currently quite satisfied with how my portfolio looks than for any of the reasons mentioned above.
Yours, FinanzMechanik

1111
10 Comentários
Well, I like these dividends just as much as our dog 🐕 likes Rimadyl.
I only have 100 shares, but I'm comfortable with that and am looking forward to a nice increase in the dividend…
I only have 100 shares, but I'm comfortable with that and am looking forward to a nice increase in the dividend…
•
88
•1Mês·
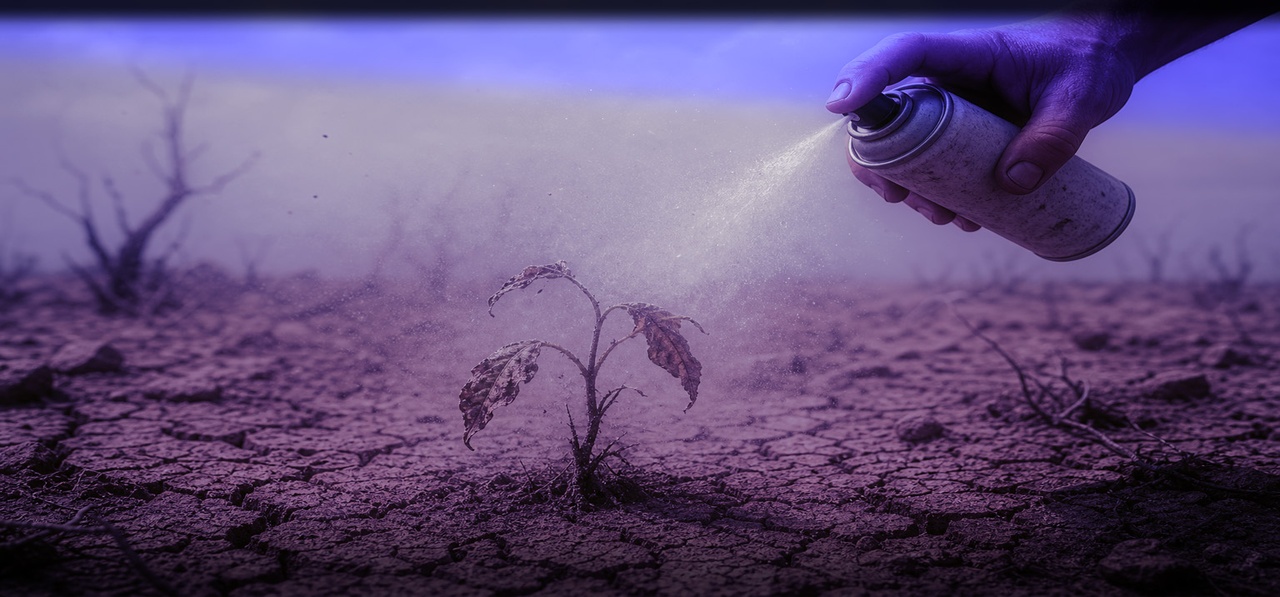
Bayer – A New Start
$BAYN (-1,34%) - What can I say? I’m just an incorrigible stubborn fool, which is why I’ve increased my disastrous Bayer position—one that has left me down as much as 70% at times over the past few years.
Is this a good investment? Is it morally justifiable? Honestly, I don’t know—I’ll probably end up in pesticide hell for it.
(Illustration created with lovart.ai, modified in Photoshop)
1818
10 ComentáriosYou could always switch to cigarettes 😆
•
22
•
2Mês·
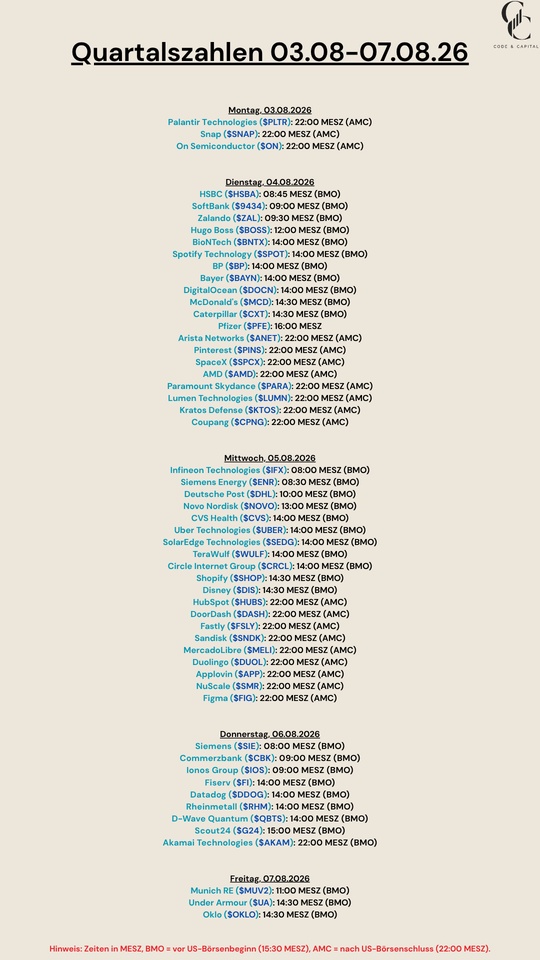
Quarterly Results August 3–7, 2026
$PLTR (-2,52%)
$SNAP (-2,16%)
$HSBA (-2,34%)
$9434 (+0,22%)
$ZAL (+2,03%)
$BOSS (+0,22%)
$BNTX (-2,35%)
$SPOT (+11,1%)
$BP. (+0,32%)
$BAYN (-1,34%)
$DOCN (-10,31%)
$MCD (+2,56%)
$CAT (-4,87%)
$PFE (+2,01%)
$ANET (-7,71%)
$PINS (-0,49%)
$SPCX (-8,52%)
$AMD (-8,5%)
$PARA (+0,93%)
$LUMN (+0,19%)
$KTOS (-2,12%)
$CPNG (+1,07%)
$IFX (-6,52%)
$ENR (-8,4%)
$DHL (-1,18%)
$NOVO B (+1%)
$CVS (+1,19%)
$UBER (+1,87%)
$SEDG (-0,68%)
$WULF (-12,48%)
$CRCL (-5,45%)
$SHOP (-5,16%)
$DIS (+1,08%)
$HUBS (+6,97%)
$DASH (+1,02%)
$FSLY (-4,5%)
$SNDK (-10,61%)
$MELI (-1,66%)
$DUOL
$APP (-1,5%)
$SMR
$FIG (+4,52%)
$SIE (-3,48%)
$CBK (-4,18%)
$IOS (-0,88%)
$FI (+5,18%)
$DDOG (-6,23%)
$RHM (-0,13%)
$QBTS (-4,32%)
$G24 (+2,91%)
$AKAM (+0,35%)
$MUV2 (+1,22%)
$UA (+3,46%)
$OKLO
1313

3Mês·
Top News Stories from the Past Week
Monday:
Because of the new competitor $SPCX (-8,52%) SpaceX, $DTE (+2,65%) Deutsche Telekom is apparently planning a merger with Telekom US. The new holding company could be headquartered in Ireland or Switzerland, similar to what we’ve already seen with Linde. A move that seems somewhat absurd, considering that we’re talking about Deutsche Telekom. In any case, the plans aren’t going over well on the stock market—or rather, the assessment that competition from SpaceX will be so fierce.
Tuesday:
Partly due to the fuel rebate, which is set to expire on Wednesday, inflation in Germany stood at just 2.3%. This puts it only slightly above the ECB’s 2.0% inflation target.
Nike exceeded expectations for quarterly revenue and posted higher quarterly earnings. This was due, in part, to $NKE (+1,59%) Nike is receiving refunds for overpaid customs duties.
Wednesday:
It was revealed that Donald Trump earned more than $1 billion from crypto projects alone during his first year in office. These included meme coins that have lost significant value. Trump’s earnings have also multiplied compared to 2024.
https://www.bbc.com/news/articles/cvgmv98ez3zo
Thursday:
$BAYN (-1,34%) Bayer is taking the next step to finally distance itself from the glyphosate lawsuits. Glyphosate is being spun off into the new business unit Ruveon.
www.wiwo.deSpekulation um Fusion: Arbeiten Telekom und T-Mobile an einem geheimen Mega-Projekt?
22
3Mês·
Bayer
$BAYN (-1,34%) - Bayer has seen its stock price rise by nearly 100% over the past year. Much of this is due to the court rulings on glyphosate in the U.S.
For me, that means I’m now only down about 38%. 😅 💥💥I think I’ll crack open half a beer tonight to celebrate.
3Mês·
Top News Stories from the Past Week
As we do every Sunday, here are the top news stories from the past week:
Monday:
Elon Musk may have raked in billions from SpaceX’s $SPCX (-8,52%) SpaceX, but apparently the money isn’t enough for his AI ambitions, so he’s launching a $20 billion bond program. This isn’t going over well with SpaceX investors. The bonds are expected to yield about 5–6% interest.
Tuesday:
DB has once again outdone itself and hit an all-time low. For hours overnight, no trains ran in Germany. Other former state-owned corporations, such as $DHLGY (-1,04%) Deutsche Post (DHL) or $DTE (+2,65%) Deutsche Telekom, do not face comparable problems. Perhaps we should consider further privatization of DB or follow the Swiss model (where local municipalities also have a say at the regional level).
https://www.tagesschau.de/wirtschaft/unternehmen/deutsche-bahn-stoerung-zugfunk-100.html
Wednesday:
$ADS (-1,23%) Adidas is reportedly selling three times as many DFB jerseys as it did in Qatar in 2022. This may be partly because people can now actually wear the DFB jersey. The switch to $NKE (+1,59%) Nike could also be a factor.
$VOW3 (+0,13%) Volkswagen is selling a majority stake in Everllance to Bain, reaping billions in the process. Everllance has so far been carried on the balance sheet at a value significantly below its market value, which is likely to result in an extraordinary profit of several billion.
Thursday:
$BAYN (-1,34%) Bayer appears to have pulled off a major victory. The agricultural and pharmaceutical company won its case before the U.S. Supreme Court. The court ruled that regulations set by federal agencies take precedence over state laws. As a result, thousands of lawsuits alleging insufficient cancer warnings have lost their legal basis.

www.manager-magazin.deSpaceX: Raumfahrtfirma plant Anleiheemission über 20 Milliarden Dollar
77
Títulos em alta
Principais criadores desta semana
Dados tempo real da LSX · Dados financeiros e EOD da FactSet