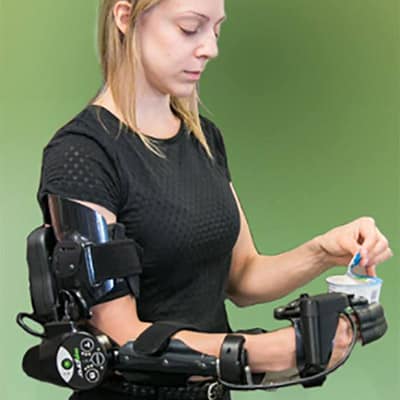


Myomo Inc. $MYO (-1,25 %) reported a 21% year-over-year increase in revenue for the second quarter, exceeding Wall Street expectations. At the same time, the company’s loss narrowed, and its gross margin expanded significantly. The manufacturer of wearable roboticorthoses reported a net loss of $0.09 per share on revenue of $11.7 million, beating analysts’ estimates, which had projected a loss of $0.10 per share on revenue of $10.29 million.
The stock rose 4.72% to $1.11 in after-hours trading, having closed regular trading at $1.06. This suggests that investors reacted positively to the unexpectedly strong quarter and the raised full-year revenue outlook.
According to Myomo, the quarter demonstrated further progress toward profitability, as revenue growth outpaced cost growth. Operating expenses rose by less than 1% quarter-over-quarter to $10.7 million, while revenue increased by 21% year-over-year. This helped reduce the operating loss from $4.6 million in the second quarter of 2025 to $2.3 million.
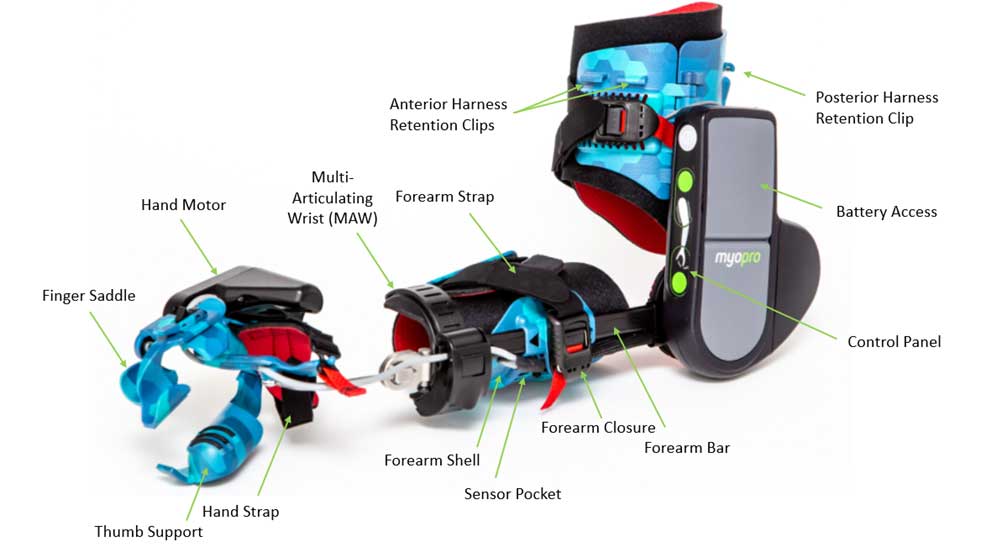
The company, which manufactures wearable robotic orthoses for people with arm and hand paralysis, shipped 211 MyoPro devices during the quarter, representing a 19% increase over the previous year. The average selling price rose by about 2% to approximately $55,500.
Management emphasized that, despite having shipped more than 3,000 devices to date, the business is still in an early stage of market penetration. It pointed to a large pool of potential patients and a growing number of referral centers, including rehabilitation clinics as well as orthopedic and prosthetics providers.
Financial Highlights
Revenue: $11.7 million, up 21% year-over-year.
Revenue for the last twelve months: $41.21 million, representing annual growth of 6.7%.
Current Ratio (third-degree liquidity): 2.73, indicating that cash and cash equivalents comfortably exceed current liabilities.
Net loss: $4.0 million, or $0.09 per share, compared to $4.6 million, or $0.11 per share, in the prior year.
Adjusted EBITDA loss: $800,000, compared to a loss of $4 million in the prior year.
Operating loss: $2.3 million, compared to $4.6 million in the prior-year period.
Gross margin: 72.1%, compared to 62.7%.
Order intake: 255 MyoPro units, up 23% year-over-year.
Units sold: 211 devices, an increase of 19%.
Cash outflow from operating activities: $1.9 million, compared to $8.9 million in the prior year.
Cash, cash equivalents, and short-term investments: $13.5 million as of June 30.
Repeat patient sources: 53% of total revenue, compared to 26% in the prior year.
Results Compared to Forecasts
Myomo exceeded expectations in both earnings and revenue. The company reported a loss of $0.09 per share, which was $0.01, or 10.0%, better than the forecast of a $0.10 loss per share. Revenue of $11.7 million exceeded the consensus estimate of $10.29 million by $1.41 million, or 13.7%.
The positive revenue surprise was the decisive factor. It was accompanied by record orders, higher margins, and improved operating leverage, suggesting that the quarter was not driven by a one-time effect. The company also reduced its net loss compared to the same period last year, which supports the view that operating performance is improving.
Compared to recent quarters, the results fit more into a broader trend of gradual improvement than a sudden turnaround. While Myomo continues to post losses, the pace of progress appears to be accelerating, as revenue is growing faster than costs.
The immediate reaction appears to reflect relief over the revenue beat, the margin improvement, and the raised outlook. Since no volume data was available, it is impossible to say whether the price movement was accompanied by unusually high trading volume.
Outlook and Forecast
Myomo raised its revenue forecast for the full year 2026 from the previous range of $43 million to $46 million to $45 million to $47 million. The new midpoint implies a slightly stronger second half of the year, supported by continued growth in referral-based sales and international demand.
For the third quarter, the company expects revenue of $11.5 million to $12 million. Management also stated that operating costs are likely to rise moderately in the third quarter, while expenses in the fourth quarter are expected to remain at the third-quarter level.
According to the company, the gross margin is expected to remain at current levels or improve further, supported by efficiency gains in manufacturing, reductions in material costs, and the launch of the mobile app. Cash burn in the second half of 2026 is expected to be less than $2 million.
Strategically, Myomo is advancing several initiatives:
Expansion of the MyoConnect referral program,
Growth in the orthopedics and prosthetics sales channels,
Continued international expansion, particularly in Europe,
Progress in the University of Utah clinical trial,
Development of the next generation, MyoPro 3,
and work on a handheld device, starting in Germany.
Management Comments
CEO Paul Gudonis stated that the company’s mission remains to “restore function and independence to people living with chronic arm and hand paralysis.” He said the quarter demonstrated that Myomo is building a “more resilient and scalable business” through its shift toward recurring patient referrals and tighter operational control.
Gudonis also pointed to the growing base of referring physicians and noted that Myomo has now expanded MyoConnect to approximately 300 locations. He emphasized that, despite having shipped more than 3,000 devices, the company is still in an early stage of market penetration.
Chief Financial Officer Dave Henry said the company’s adjusted EBITDA loss had improved from $4 million in the prior year to $800,000, and cash outflow from operating activities had decreased from $8.9 million to $1.9 million. He added that the company continues to expect revenue growth to outpace cost growth.
Source: Investing