

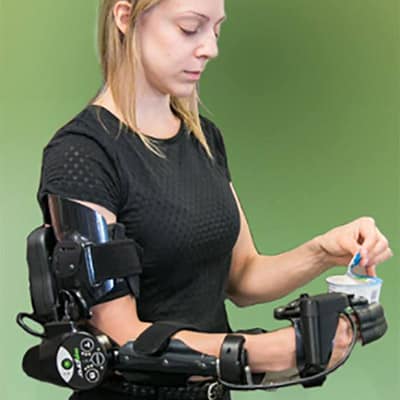
Imagine your arm is "numb" or paralyzed after a stroke. The brain sends commands, but the muscles in the arm no longer respond. This is exactly where Myomo technology (MyoPro) comes into play. It is not just a "support splint", it is active mechatronics.
Unfortunately, the statistics are merciless. Worldwide, almost 94 million people with the consequences of a stroke. Every year there are around 12 million new cases are added. One in four adults over the age of 25 will suffer a stroke in their lifetime.
- The demographic pressure: Our societies are ageing and risk factors such as high blood pressure, diabetes and lack of exercise are increasing globally. This means that the need for effective rehabilitation solutions for paralyzed limbs that are suitable for everyday use is not decreasing - it is growing dramatically.
A brief clarification: I've been invested since today because I think the story is cool and this is a gamble with potential.
1. what the company does
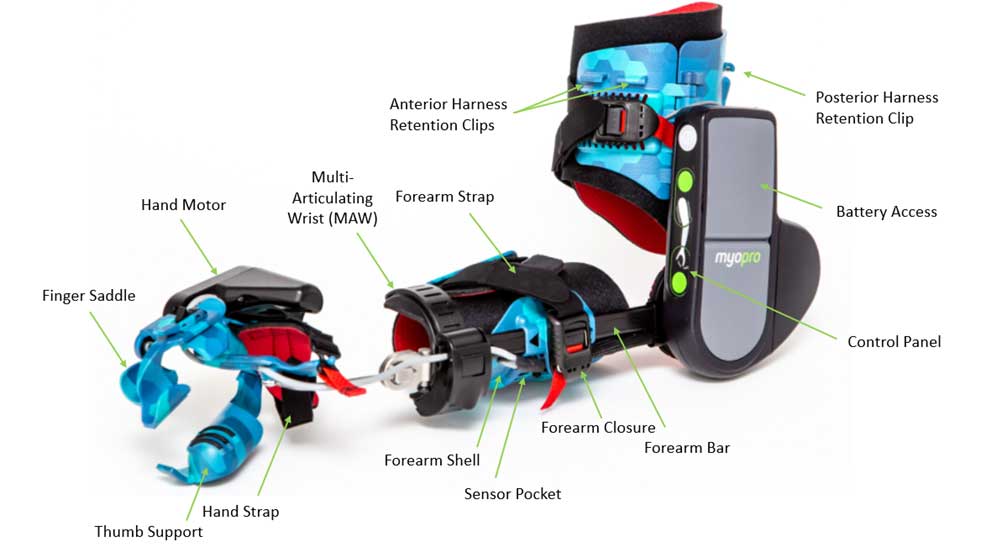
Myomo $MYO (-0,89 %) builds medical robotics, specializing in the upper extremities. Its main product is the "MyoPro" splint - a wearable exoskeleton. When patients can no longer control their arm due to a stroke, MS or nerve injury, the MyoPro reads the remaining, extremely weak electrical signals on the skin (EMG). The finest CNC-milled joints and tiny servomotors then take over the mechanical movement. This is not just theory, this thing literally brings patients out of paralysis.
- The highlight: Sensors recognize the patient's intention - does he want to open his hand, bend his elbow or grasp something? - and tiny, high-precision motors and gears support this exact movement. The patient controls the robotic arm with his own will. It is literally a neural bridge between what the patient wants and what they can physically do.
2. key figures, data & facts (real-time)
- Current share price: ~ 1.03 $* Market capitalization: ~ 35 Mio.$ (An absolute micro-cap!)
- Price-earnings ratio (P/E ratio): Negative (currently no profits yet)
- Price-to-sales ratio (P/S ratio): ~ 1,8
- Price-to-book ratio (P/B ratio): ~ 2,5
- Dividend yield: 0,0 %
In other recent news, Myomo Inc. presented its results for the first quarter of 2026, beating expectations for both earnings per share (EPS) and revenue. The company achieved EPS of -$0.07, which was above the forecast of -$0.12. Myomo also reported revenue of $10.1 million, exceeding the expected $9.24 million. These figures reflect a positive business development for the company in the quarter.
3. check against our established formulas
- Core quality formula: Sales growth is currently picking up steeply (well over 30%), but the operating margin is still deep red. Score < 15. *
- Conclusion on the AOK filter: Fails mercilessly as a core investment. This is a pure B-side satellite for the gambler's corner. We are buying the expectation that the extreme sales growth will turn the red margin into positive territory in the next 24 months.
4 ROIC (Return on Invested Capital)
Currently negative. The development of medical technology and the expensive battle for approvals have tied up a lot of capital. Now the phase begins in which this invested capital must finally yield a return.
5. stock-based compensation (SBC) ratio & dilution
Dilution is always the biggest risk for micro-caps in the medical sector. In the past, Myomo often had to issue new shares to ensure its survival. However, due to its new status with the health insurance companies (more on this in point 7), hard dollars are now flowing into the company's coffers. The risk of dilution has fallen massively.
6. net debt / EBITDA ratio
EBITDA is still negative, which is why this key figure does not traditionally apply. However, Myomo has recently raised fresh capital and currently has a solid enough balance sheet to scale production without an overwhelming debt burden.
7. future prospects & competition
The game changer: The US Department of Health and Human Services (Medicare) has officially included the MyoPro in the Part B category and is now paying for the device.
In the past, Myomo had to laboriously find private patients; now the state pays.
Competition: Other companies also build exoskeletons, but focus almost exclusively on the legs (paraplegia). When it comes to arms and hands, Myomo has a truly unique selling point, almost a moat.
8. chart analysis (last months)
Typical penny stock roller coaster. Over the last 12 months, the share has often fluctuated wildly between $0.60 and $2.50, driven by the news surrounding Medicare approval. It is currently consolidating just above the important 1 dollar mark. It must hold this level to avoid being warned by the NASDAQ.
9 Management & CEO statements
CEO Paul Gudonis has proven that he has staying power. He has navigated the company through years of brutal FDA and Medicare approvals. The management is now completely focused on expanding production capacity in order to work through the waiting lists of patients.
Addendum Thanks to @jkb92, there was recent insider buying: https://m.de.investing.com/news/insider-trading-news/myomodirektor-kirk-thomas-f-kauft-aktien-im-wert-von-68242--93CH-3488408?ampMode=1
10th analyst consensus
Micro-caps like $MYO (-0,89 %) are ignored by the big Wall Street banks. The few small boutique analysts (such as H.C. Wainwright) who cover the stock are currently shouting "Strong Buy" with price targets between $3.00 and $5.00.
11. bargain hunter list (entry zones)
- Current (~$1.03): Perfect speculative entry for play money. The fundamentally most important knot (payment by health insurance companies) has burst.
- Support zone: There is a hard floor at $0.80. If it falls below this level on a sustained basis, the story will be ruined for the time being.
12 Possible replacements (alternatives)
If you believe in the robotics trend in medicine but would rather invest in legs than arms, take a look at Lifeward (LFWD) IL0011331076.
Also quoted in the single-dollar range.
13. detailed report (my conclusion)
Myomo is a smart hardware gamble. The company has successfully survived the "death zone" for small medtech companies - the quest for regulatory reimbursement. Now it's time for implementation. The demand for mechatronic aids for stroke patients is huge.
We have a technology here that alleviates real human suffering, has a huge and growing target group and has finally made the leap into state reimbursement. This is not a "story without substance" - this is medical robotics that is now making the leap to scale. A highly exciting gamble that has the fundamental potential to grow from a penny stock to a real MedTech giant.
An absolute top candidate for a limited play money budget on the B-side.
- State-Funded Recovery: With US Medicare approval, Myomo has risen from "niche gadget for the rich" to recognized standard medical product for home use.
- Cost-effectiveness: This is even profitable for health insurance companies. A patient who can eat, wash or grasp simple things independently again with MyoPro needs fewer expensive nursing staff and is less dependent on external help.
and of course everyone else :)


