€441.22 in dividends in October. Five companies, five payments, and two I wouldn’t add to my portfolio today.
The numbers come from my portfolio and the spreadsheets in my investment model, so here’s the full breakdown—including the caveats.
• $DG (-1.31%) Vinci €157.30 🟢 Optimal
•$SAN (-0.57%) Santander €135.26 🟣 Watch
• $T (-1%) AT&T €86.05 🟢 Optimal
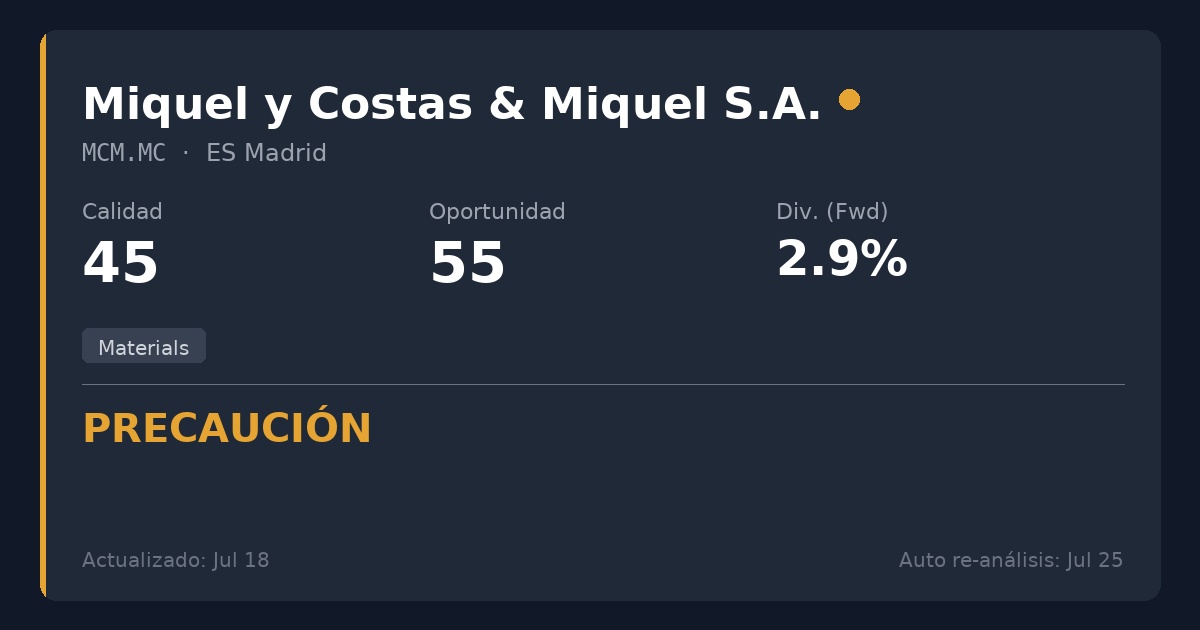
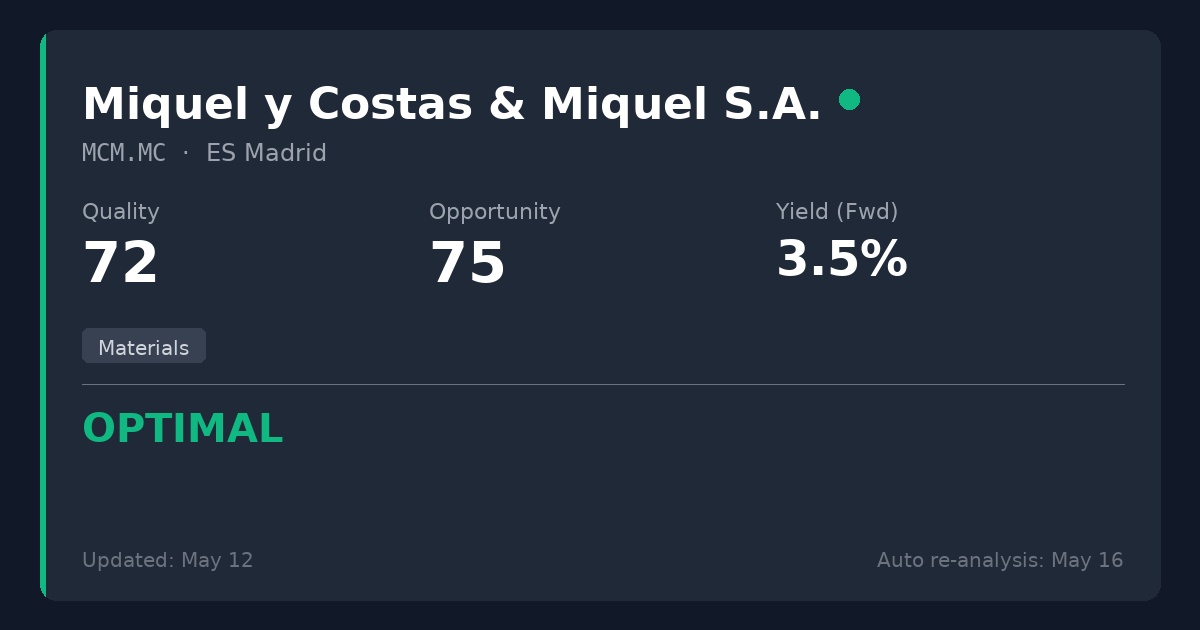
•$MCM (+0.4%) Miquel y Costas €32.50 🟠 Caution
• $MKC (-1.56%) McCormick €30.11 🟢 Optimal
🟢 Vinci: 4.66% yield and a 12.09x P/E ratio for the highway and airport operator. The downside: France’s plans to raise taxes on concessions and the expiration of French highway concessions between 2032 and 2036.
🟣 Banco Santander: 10.88x P/E ratio, 23.69% payout ratio, and a 6.87% total return to shareholders including share buybacks. The downside: it distributes only 2.44% in cash, so a large portion of the return comes from share buybacks rather than cash dividends. The 65% cut in 2021 remains on its track record.
🟢 AT&T: 5.36% yield, 11.38x P/E ratio, and 2.25x cash coverage. The downside: It cut the dividend by 35% in 2022, has frozen it until 2028, and carries a debt-to-EBITDA ratio of 3.66x.
🟠 Miquel y Costas: 8.35x P/E ratio and positive net cash, but 60% of its revenue comes from cigarette paper, and the dividend’s cash coverage is 0.65x. My system rates it at 25/100 for quality. I’ll collect my €32.50, but I won’t increase my position until I see results from the €130M plan.
🟢 McCormick: 4.10% yield, 8.50x P/E ratio, and 40 consecutive years of dividend increases. The downside: strikes and a current P/E ratio of 8.5x versus a forward P/E of 13.87x, which usually means that recent earnings included one-time items.