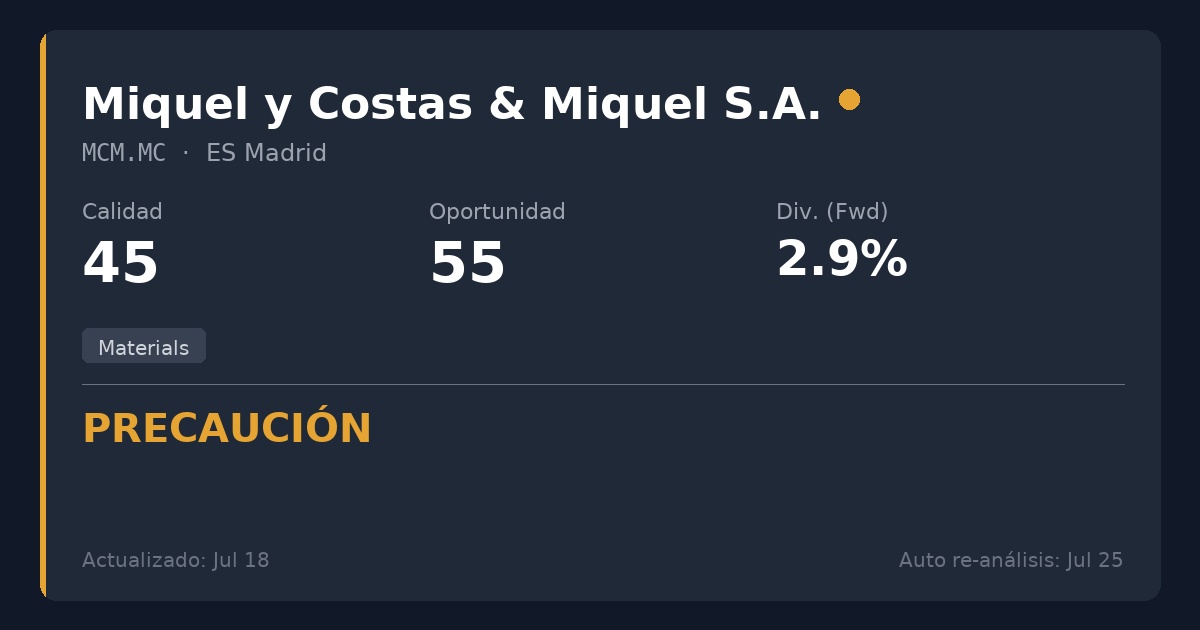
Miquel y Costas $MCM (+0.05%) is a highly profitable specialty paper manufacturer with an impeccable net cash balance sheet, but its high exposure to the tobacco market—which is in secular decline—creates a long-term strategic mismatch for conservative dividend investors. The current valuation (P/E ratio of 11.7) appears attractive, but the ongoing capital expenditure cycle of 130 million euros is squeezing free cash flow, and the dividend yield of 2.88% falls below our target thresholds.
It is in our “caution” quadrant, which means you need to fully understand the situation before investing in the stock. I’m holding onto it for now.
Since I bought it in 2020, it has risen 30%, and I’ve received 17% in dividends—about a 3.7% yield.