- Markets
- ETFs
- Xtrackers MSCI World ETF
- Forum Discussion
Xtrackers MSCI World ETF
Price
Discussion about XDWD
Posts
135


MSCI OUT -> FTSE ALL WORLD IN
$XDWD (-0.72%) -> $VWRL (-0.82%)
Why?
*VWRL offers true global exposure, including both developed and emerging markets, while XDWD only covers developed markets.
*VWRL is a complete one-fund solution, giving me exposure to the entire global stock market without needing additional ETFs.
*VWRL pays a cash dividend, which I enjoy receiving and can reinvest, while XDWD is focused more on accumulation than income.

My Portfolio
Hi everyone,
What do you think of my portfolio? First, a little background info:
About me: I’m in my mid-30s and have been actively trading on the stock market for over 12 years now. So I’ve experienced several market booms and crashes from an investor’s perspective :D
About the portfolio: I follow a core-satellite strategy with additional “income satellites.” The income satellites are used to generate income with the goal of creating a monthly cash flow, which I mainly use for additional purchases to keep the portfolio balanced.
Core: $XDWD (-0.72%) World ETF, $IMEU (-0.04%) EU ETF, $XMME (-1.78%) Emerging Markets ETF, $TDIV (+0.41%) VanEck TDIV
Satellites: $NVDA (-3.04%) NVIDIA, $MSFT (-1.43%) Microsoft, $GOOGL (-1.46%) Alphabet, $AMZN (-1.44%) Amazon, $HO (+0.99%) Thales // NVIDIA and Alphabet are currently being built up. The positions will both be doubled.
Income satellites: $D05 (-1.37%) DBS Group Holding, $KO (+2.23%) Coca-Cola, $BATS (+1.55%) BATs, $O (+0.67%) Realty Income, $VICI (+0.73%) VICI Properties
Others: Small positions for shorting and speculation. (Amgen, Vertex, SpaceX, BTC, Ethereum, ...)
Feel free to share your thoughts :)
The real question is whether this diversification in your core holdings actually makes a difference. At least if you’re taking a long-term view, the simple $IWDA is probably sufficient.
If you want to somewhat mitigate the US and tech concentration risk in these indices (which I think makes sense with a long-term horizon), then perhaps something like this as a core:
https://gerd-kommer.de/etf/vergleich/
Disclaimer: No, I don’t profit from this fund and have nothing to do with it. But that doesn’t change the fact that this is a good approach for people who want to build wealth over the long term while maximizing safety.
Incidentally, Stiftung Warentest also takes this view in its November 2025 ETF issue (I highly recommend reading it—it’s really well done).
Investment strategy/depot allocation. Your opinion?
Hello everyone,
What do you think of the following investment strategy?
Global core (30% portfolio share)
$XDWD (-0.72%) Xtrackers MSCI World UCITS
Europe share (15% portfolio share)
$SMEA (-0.11%) iShares Core MSCI Europe ETF
Emerging markets (10% portfolio share)
$XMME (-1.78%) Xtrackers MSCI Emerging Markets ETF
Distributions (15% of the portfolio)
$TDIV (+0.41%) VanEck Morningstar DM Dividend Leaders ETF
The remaining 30% consists of 20% individual stocks (old market / tech) and 10% cash reserve.
Strategy: Growth focus with a small dividend component to generate additional capital for new investments, speculation and additional purchases while at the same time realizing the tax-free allowance.

Inspiration/help wanted!
Dear getquin community,
I've been quietly reading along here for some time now and have really taken a lot from many of the posts. I am now facing a major decision myself and am really hoping for your opinions and experiences.
Briefly about me and my situation: I am in my mid-20s and have been investing privately for around ten years. Up to now, I have mainly bought individual shares or commodity ETCs when the right opportunities arose and held them for the long term. During my studies, investing was rather irregular, but this was perfectly sufficient for my goals at the time.
For some years now, I have been running a small company in the e-commerce sector together with a colleague. In the meantime, profits have accumulated there, most of which are currently sitting unused in accounts and losing value due to inflation. This is exactly what I want to change now.
My aim is to invest this capital sensibly in order to maintain purchasing power and, in the best case, achieve a solid return. To start with, we would like to invest around 200,000 euros.
My thoughts on the allocation so far are as follows:
- 30% in $XMME (-1.78%) (Emerging Markets ETF)
- 30% in $XDWD (-0.72%) (MSCI World)
- 20% in $XAD6 (-5.47%) (Physical Silver ETC)
- 20% in $XAD1 (-1.77%) (Physical Gold ETC)
As I have no experience with larger one-off investments within short periods of time, I would be very pleased to receive your feedback. I am particularly interested in the following points:
- What do you think of the basic allocation?
- Would you rather invest everything at once or take a staggered approach?
- Do you think a proportion of gold or silver makes sense at the current price level?
I would be grateful for any advice, criticism or suggestions for improvement. Thank you very much in advance for your time and input.
Love Grüße✌🏻


Strategy presentation, feedback welcome
Hello everyone,
I have been following this forum for some time now and have decided to present my experiments and current strategies.
On the one hand, because I want to avoid losing track of things, and on the other hand, to prepare my thoughts for myself and also to get other perspectives and opinions.
Briefly about myself
I am 22 years old and graduated last year with a Bachelor of Engineering in Energy Technology.
I am currently working in a medium-sized company in the energy industry in Germany.
I have been rather frugal with money since I was a child. As I got older, my interest in increasing money wisely grew.
I was also lucky that my uncle opened a junior custody account for me when I was born. As a result, at the age of 18 I already had a small starting portfolio worth around 3,000 euros.
At the beginning, I focused intensively on precious metals and also invested in them. I don't plan to touch these holdings in the long term. If I don't need them, I see them more as a legacy for the next generation. I will buy more from time to time.
Basic start
As a first step, and I am aware that this will be assessed differently, I have taken out a unit-linked pension plan with the savings bank, which I save 150 euros per month.
I also took out a building society savings plan, as I basically want to buy my own home in the long term. I am currently renting.
The building society saver is also 150 euros per month per month.
At the same time, I have been working with neobrokers, from which my current portfolio has gradually developed.
Yes, there are still quite a few stocks in it at the moment. I will probably clean that up in the long term.
1st approach, accumulating ETFs
My first approach was to invest in classic accumulating ETFs.
- World, $XDWD (-0.72%)
- Emerging markets, $EIMI (-1.48%)
- AI and big data, $XAIX (-2.61%)
Smaller side bets were added later.
- Armaments, $DFEN (-0.09%)
- uranium, $U3O8 (-4.53%)
- batteries, $BATG (-2.61%)
I also bought my first individual shares to gain experience. Among other things, I had success with $RHM (+2.56%) . At the same time, I learned how quickly losses can occur if you are not sufficiently diversified, for example with $ABR (+9.78%) ,$1SXP (+2.4%) and other stocks.
This ultimately led me to my second approach.
2nd approach, dividend strategy
As I already have a pension plan through LBS and don't want to be the richest man in the cemetery, I focused more on a dividend strategy.
The first attempt consisted of the following combination
The idea came from a business magazine and was aimed at making monthly distributions as even as possible. I also added $QYLE (-0.16%) to gain initial experience with option strategies.
However, as this combination is only diversified to a limited extent and I deliberately wanted to move away from the USA, I adapted my strategy further.
Current strategy
Fixed savings rates
- LBS, retirement provision, 150 euros per month
- Building society, residual debt for future home ownership, 150 euros per month
Dividend strategy with 115.24 euros per month
- $XDWL (-0.71%) , 34 percent
- $IEEM (-1.72%) , 26 percent
- $XAIX (-2.61%) , 13 percent
- $EXSH (-0.13%) , 26 percent
Side bets with 81 euros per month
- $DFEN (-0.09%) , 62 percent
- $BATG (-2.61%) , 10 percent
- $QYLE (-0.16%) , 25 percent
Trading 212 experiment with 100 euros per month
Here I am pursuing the goal of bundling individual shares in a common pot, partially saving them and automatically reinvesting distributions in order to benefit from the compound interest effect in the long term.
I welcome tips and constructive criticism so that I can continue to improve my strategy.
Best regards
Mister Kimo
Perhaps it would make sense to think about liquidating all small positions (for example < 1%) and investing in a closed position
In itself, however, there is little wrong with the individual positions

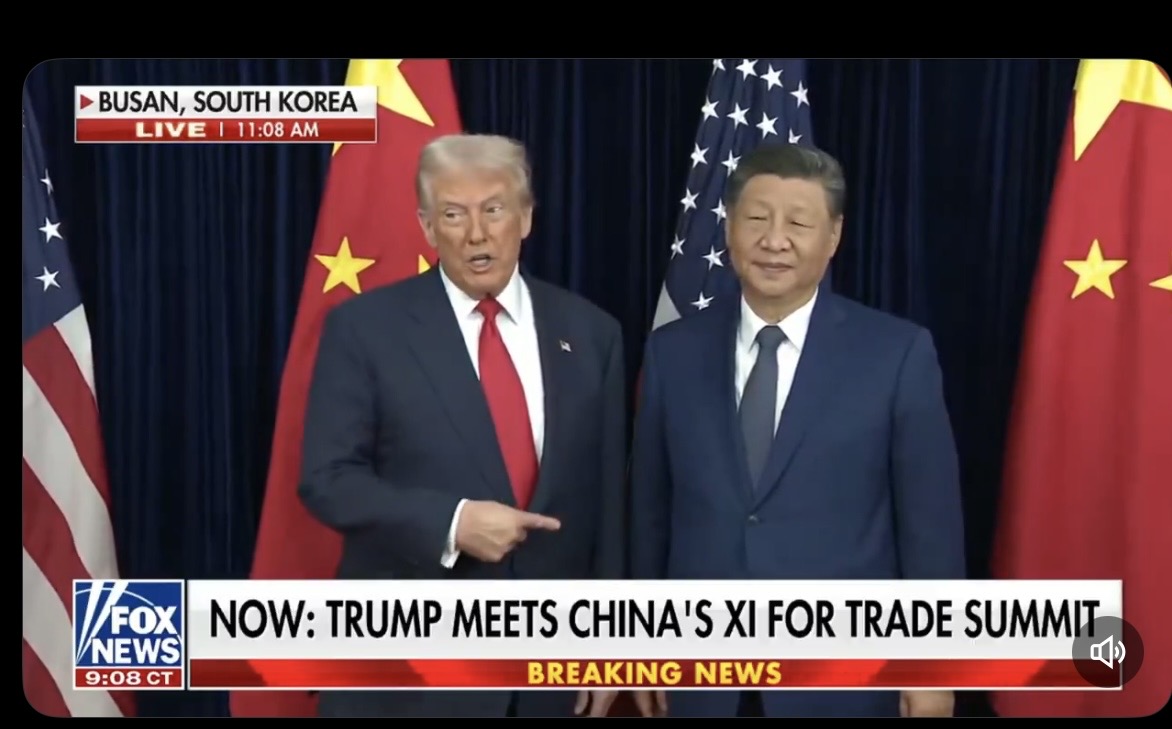
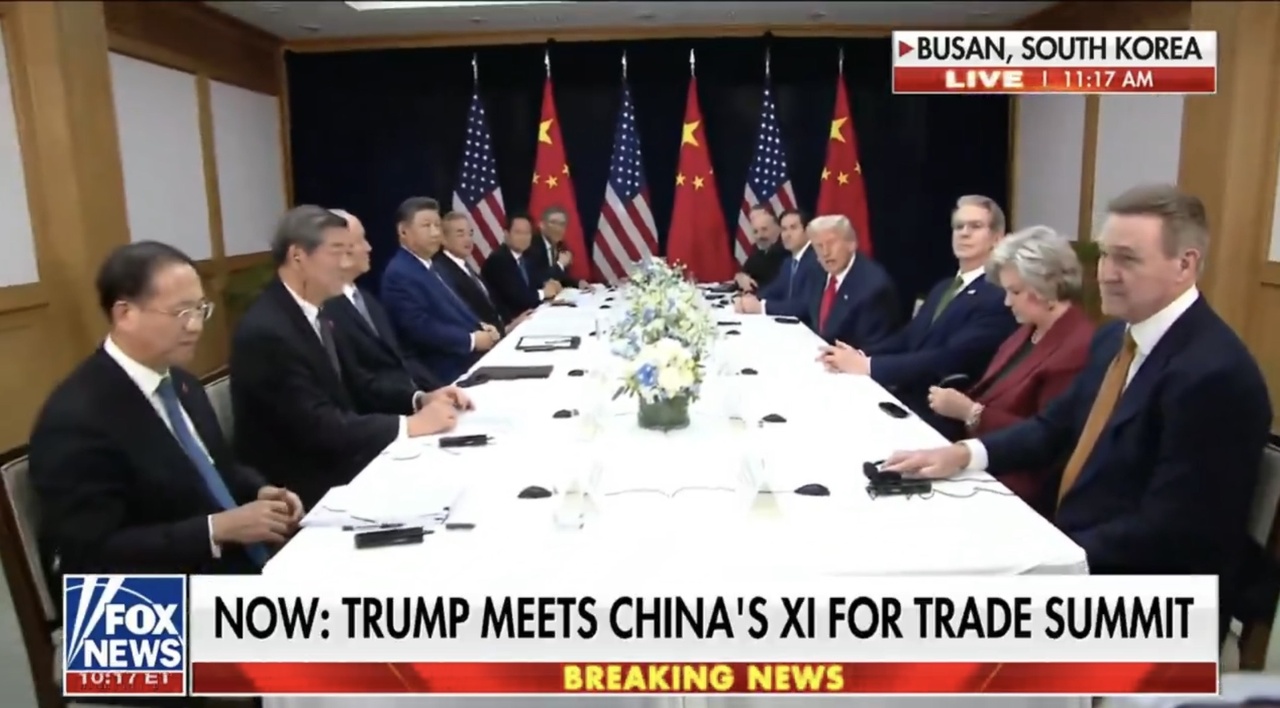
🇺🇸🇨🇳 President Trump meets officially with Chinese President Xi Jinping to discuss a trade agreement.
$IWDA (-0.69%)
$CSPX (-0.73%)
$EIMI (-1.48%)
$CSNDX (-1.64%)
$ISAC (-0.84%)
$VUSA (-0.76%)
$HMWO (-0.7%)
$XDWD (-0.72%)
$SPPW (-0.76%)
$WSML (-0.93%)
President Trump shakes hands with Chinese President Xi Jinping.
"He is a VERY tough negotiator. That's not good!" 🤣
"Nice to see you again!"
"We're going to have a very successful meeting!"
"We have ALWAYS had a great relationship."
Chinese President Xi Jinping says he is happy to finally meet President Trump.
"It's very nice to see you again! It's been many years. Since your re-election, we have spoken on the phone three times, exchanged several letters and stayed in close contact."
"Given our different national circumstances, we don't always see eye to eye. It's normal for there to be friction between the world's two leading economies."
"In the face of winds, waves and challenges, you and I, who are at the helm of Sino-US relations, should stay the right course and ensure the steady progress of these relations."
Chinese President Xi Jinping declares President Trump the PEACE PRESIDENT of the whole world!
"Mr. President, you care deeply about world peace! You are deeply committed to resolving regional conflicts. I greatly appreciate your significant contribution to the ceasefire in Gaza."
"During your visit to Malaysia, you witnessed the signing of the joint peace declaration along the Cambodian-Thai border, to which you also contributed."

Basic knowledge: Think long-term, invest globally - The world ETF as a basic building block in the core portfolio
Reading time: approx. 10 minutes
The last article was about leveraged daily ETFs - in other words, about momentum, short-term market movements and strategies where timing is crucial. Today it will be much quieter. It's about what remains when markets fluctuate and hypes fade: the fundamentals.
This article is aimed primarily at beginners and is intended to help them find their way through the ETF jungle - to understand which products are truly global, how they differ and how to build a stable core portfolio.
After all, long-term wealth accumulation does not start with the search for the highest return, but with a solid core. In my case, this core consists of three pillars:
- $ISAC (-0.84%) (iShares MSCI ACWI UCITS ETF) - as a global equity building block
- $BTC (-0.41%) (Bitcoin) - as a diversifying, asymmetric building block with its own risk profile
- $SEGA (+0.15%) (iShares Core Euro Government Bond ETF) - as a defensive counterbalance on the bond side
These three positions form the backbone of my portfolio. The rest - i.e. rotation strategies, thematic investments or leveraged products - complement the foundation.
Why an ETF comparison is important
"World ETF" sounds like global diversification. In practice, however, many of these funds only cover industrialized countries. The difference between $XDWD (-0.72%) (iShares MSCI World UCITS ETF), $ISAC (-0.84%) (iShares MSCI ACWI UCITS ETF) and $VWCE (-0.8%) (Vanguard FTSE All-World UCITS ETF) is not a marginal detail, but crucial for your own investment strategy.
Anyone who understands these differences quickly realizes how much the selection of the index determines the actual distribution in the portfolio - and how much "world" is actually in your own ETF.
The $ISAC (-0.84%)
(iShares MSCI ACWI UCITS ETF)
The $ISAC (-0.84%) tracks the MSCI All Country World Index - around 2,800 stocks from 47 countries, covering around 85% of global market capitalization.
Regional breakdown (as at October 2025):
- USA: approx. 65 %
- Europe: approx. 15 %
- Asia (incl. Japan & China): approx. 10%
- Emerging markets: approx. 10 %
This combines the $ISAC (-0.84%) industrialized and emerging markets in one product - exactly what many investors replicate themselves with two ETFs (MSCI World + MSCI Emerging Markets).
The total expense ratio (TER) is currently 0.20% p.a. - extremely favorable for a global fund of this breadth.
I use it as a core building block because it combines global diversification with simplicity: one ETF, one decision, global participation.
$ISAC (-0.84%)
vs. $XDWD (-0.72%)
(iShares MSCI World)
The $XDWD (-0.72%) (iShares MSCI World UCITS ETF) only tracks 23 industrialized countries - no emerging markets, no China, no India. It contains around 1,500 stocks and is heavily dominated by the USA.
The $ISAC (-0.84%) (iShares MSCI ACWI UCITS ETF) expands this base to include 24 emerging markets and thus has around 2,800 stocks. This means:
- $XDWD (-0.72%) is more focused, somewhat more stable, but limited to mature markets.
- $ISAC (-0.84%) is broader, more future-oriented and contains more growth markets.
In recent years, the MSCI World has been slightly ahead because the emerging markets have underperformed. In the long term, these phases tend to even out - and this is precisely where the ACWI shows its strength: It automatically grows with the global economy, even if the regional focus changes.
$ISAC (-0.84%)
vs. $VWCE (-0.8%)
(Vanguard FTSE All-World)
The $VWCE (-0.8%) (Vanguard FTSE All-World UCITS ETF) is the best-known alternative to the $ISAC (-0.84%) . It also combines industrialized and emerging markets, but according to the FTSE index methodology and with around 4,000 shares - i.e. somewhat broader.
Both funds fulfill the same purpose: global coverage in a single product. The differences lie in the details - for example in the country classification (e.g. South Korea is listed as an industrialized country in FTSE, but as an emerging country in MSCI).
The performance is also almost identical. The TER of the $VWCE (-0.8%) at 0.19% p.a. is even slightly lower than that of the $ISAC (-0.84%) . Both funds therefore offer an almost equivalent opportunity to invest globally over the long term.
Concentration in the $ISAC (-0.84%)
Despite its breadth, the ACWI is also concentrated on a few heavyweights. The top 5 positions account for around 18% of the fund (as at October 2025):
- $NVDA (-3.04%) (NVIDIA)
- $AAPL (+1.04%) (Apple)
- $MSFT (-1.43%) (Microsoft)
- $GOOG (-1.46%) & $GOOGL (-1.46%) (Alphabet)
- $AMZN (-1.44%) (Amazon)
This shows how strongly the US technology sector shapes the global markets. This weighting is not a disadvantage, but a true reflection of global market capitalization. I consciously accept this structure, but balance it out with my other core components: $BTC (-0.41%) (Bitcoin) as an uncorrelated asset and $SEGA (+0.15%) (iShares Core Euro Government Bond ETF) as an anchor of stability.
Five-year performance (as at October 2025)
- $XDWD (-0.72%) (MSCI World): + 90 %
- $ISAC (-0.84%) (MSCI ACWI): + 84 %
- $VWCE (-0.8%) (FTSE All-World): + 83 %
The differences are manageable. The MSCI World benefited more from the dominance of the USA, while $ISAC (-0.84%) and $VWCE (-0.8%) are more broadly based. This global diversification can lead to more stable returns in the long term because it is less dependent on individual markets.
What newcomers can take away from this
In my opinion, an ETF is often sufficient. A global fund like the $ISAC (-0.84%) covers almost all markets - ideal for getting started.
Keep an eye on costs. A TER of 0.20 % is very favorable for this breadth.
Global means USA-dominated. Around two thirds of the fund comes from the United States - and that is currently the market reality.
Simplicity is an advantage. Those who manage fewer products remain more consistent in the long term.
Time beats actionism. The compound interest effect unfolds its power over years - not months.
The $ISAC (-0.84%) (iShares MSCI ACWI UCITS ETF) is the centerpiece of my portfolio. It stands for breadth, simplicity and global participation - and realistically reflects the global economy.
Together with the $BTC (-0.41%) (Bitcoin) - which not only brings potential returns but also diversification to the portfolio - and the $SEGA (+0.15%) (iShares Core Euro Government Bond ETF) as a defensive counterpart, a robust core setup is created that covers all dimensions: Growth, stability and risk diversification.
The rest - thematic or individual investments, rotation strategies or leveraged ideas - completes the foundation.
Questions at the end:
- How do you structure your core?
- Do you use an all-in-one ETF like the $ISAC (-0.84%) or do you prefer to combine your own with $XDWD (-0.72%) and emerging markets?
- And what role does $BTC (-0.41%) diversification, return or both play for you?

Otherwise, I'm with you all the way.
However, I form my core with solid, fundamental individual stocks.
Trending Securities
Top creators this week