
Hallo meine Lieben,
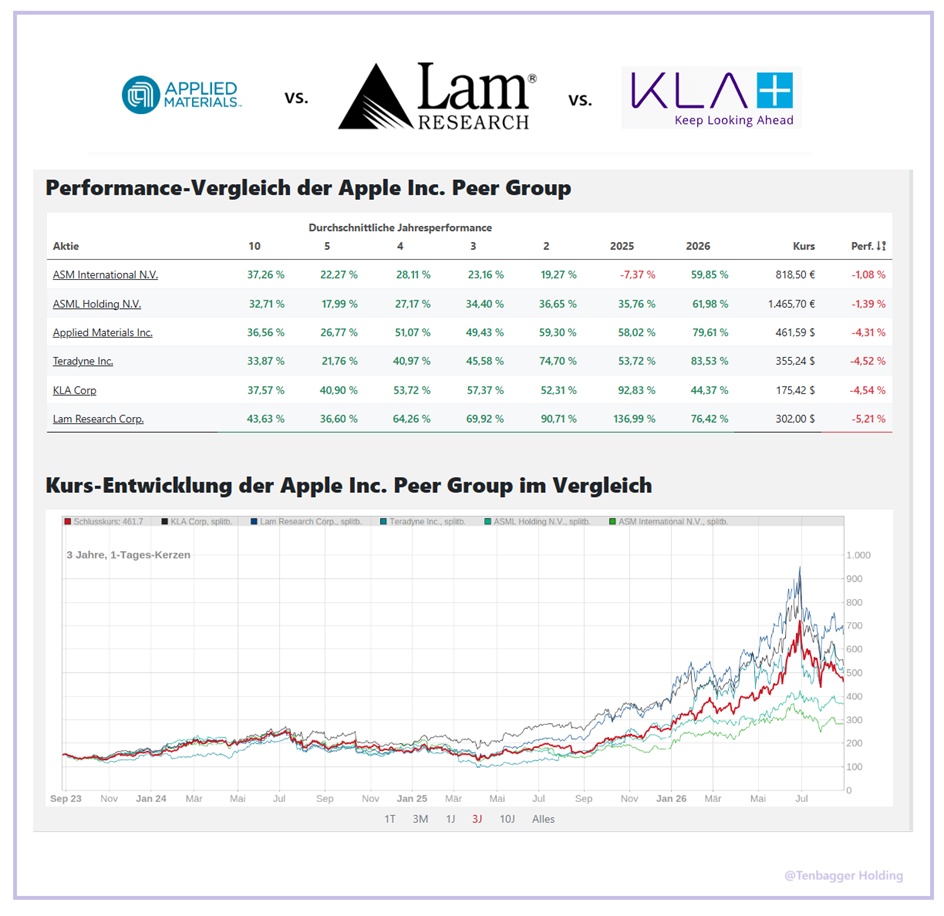
seit Wochen beobachte ich schon die Korrektur bei den Halbleiter Maschinenbauern.
Und eine nagelneue Analyse der Agenten von @Raketentoni hat diese Werte als momentane langfristige Picks hervorgebracht.
Ein weiterer Vertrauensbeweis ist, dass unser Starinvestor @Simpson hier schon seit Jahren investiert ist.
Deshalb meine Lieben gibt es für euch zum Wochenende einen von mir erarbeiteten Vergleich.
Lasst mich gerne in den Kommentaren wissen, wie euch diese Art des Vergleichs gefällt, und ob ihr euch noch mehr davon wünscht.
In einem erneuten Post gibt es eine Abstimmung. Hier dürft ihr gerne euren TOP Pick auswählen.
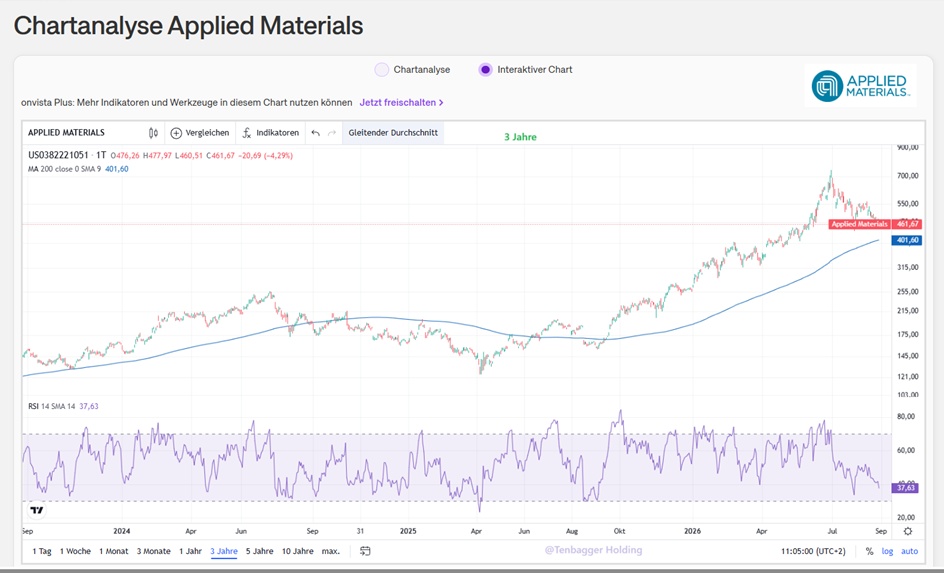
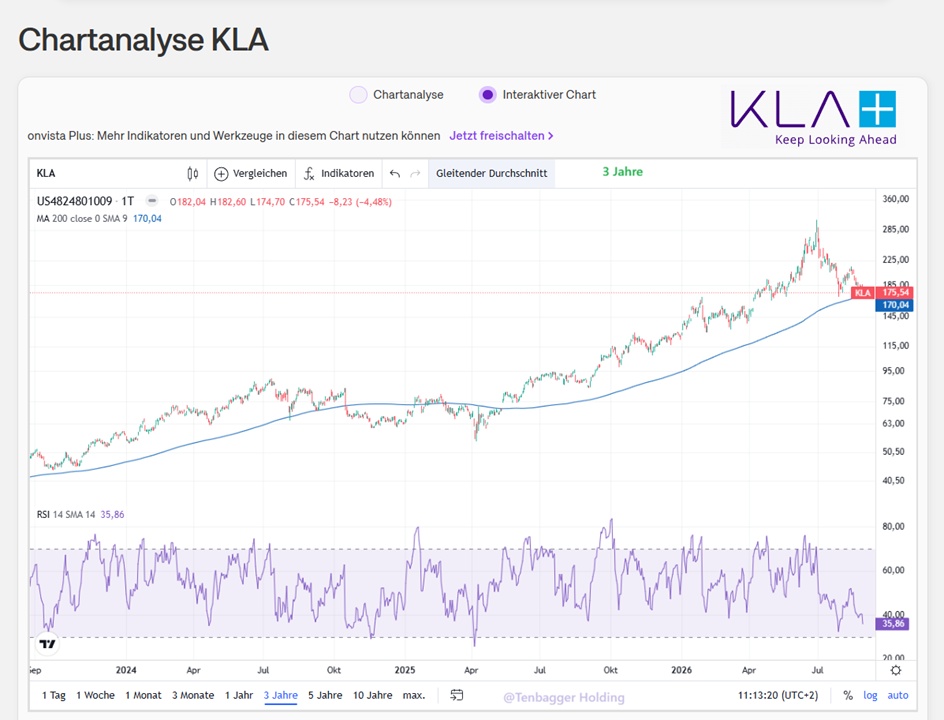
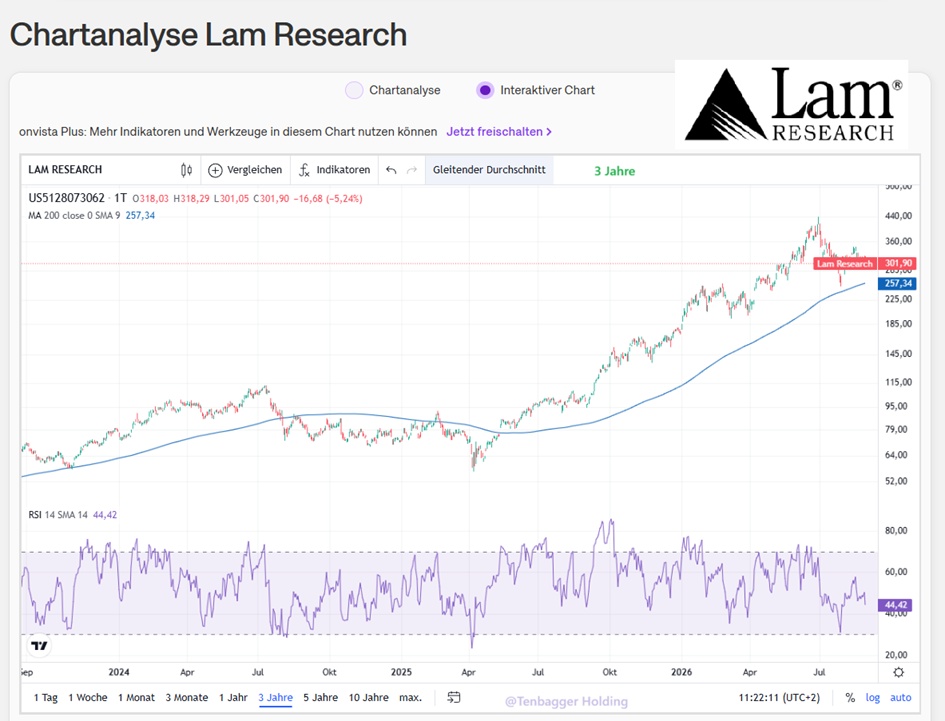
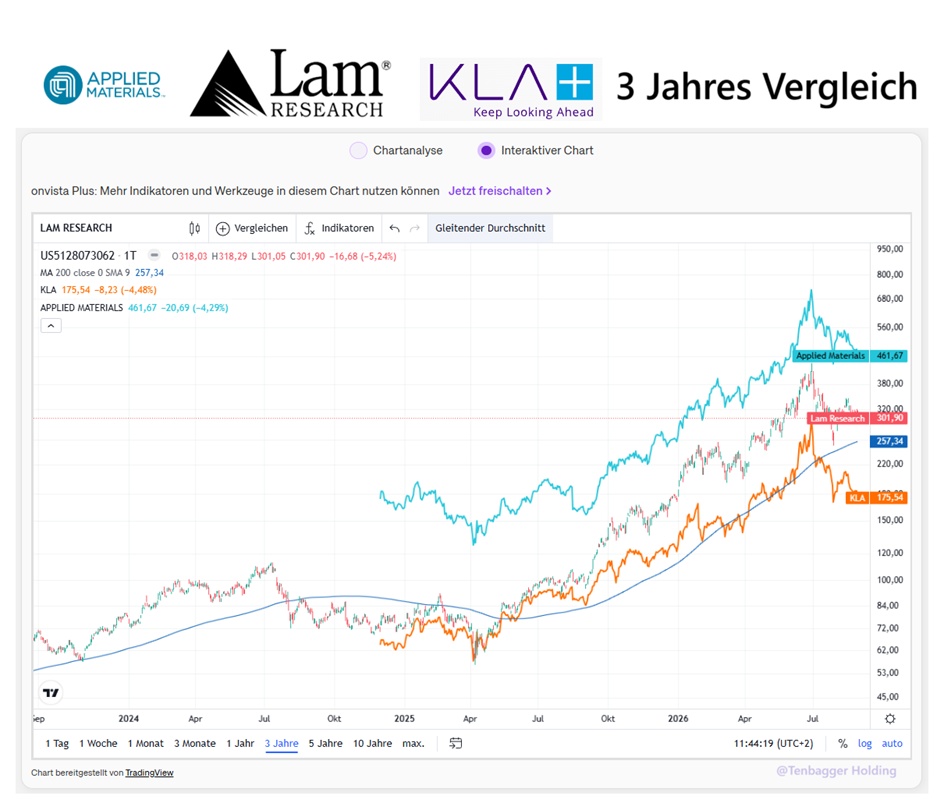
🏆 Meine Einordnung der drei Unternehmen
🥇 1. Applied Materials – attraktivstes Bewertungsprofil
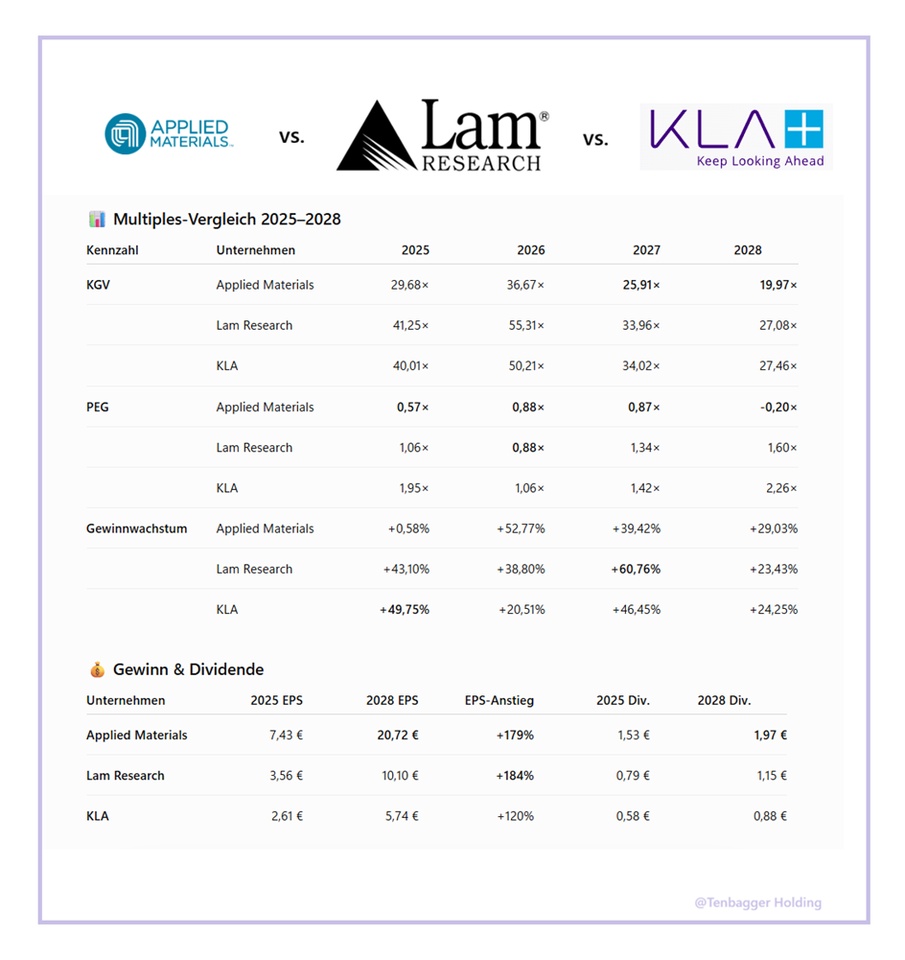
- 2028 nur 19,97× KGV
- PEG fällt auf 0,87× 2027
- 2028 sogar -0,20× PEG nach deinen Daten
- EPS steigt von 7,43 € auf 20,72 €
- Gewinnwachstum bleibt 2027/28 mit 39,42% / 29,03% stark
- Gleichzeitig höchste Dividende der drei
➡️ Für mich klar das beste Verhältnis aus Wachstum + Bewertung.
🥈 2. Lam Research – stärkstes Wachstum, aber teurer
- Höchstes Gewinnwachstum 2027: +60,76%
- EPS steigt um rund 184% von 2025 bis 2028
- KGV sinkt zwar von 55,31× auf 27,08×
- PEG steigt aber bis 2028 auf 1,60×
➡️ Operativ extrem stark, aber der Markt verlangt dafür weiterhin eine hohe Bewertung.
🥉 3. KLA – hervorragendes Unternehmen, aber teuerstes PEG
- Starkes Gewinnwachstum
- 2027 noch +46,45%
- KGV fällt auf 27,46×
- PEG steigt jedoch auf 2,26× in 2028
➡️ Qualitativ sehr interessant, aber anhand der Multiples aktuell die anspruchsvollste Bewertung.
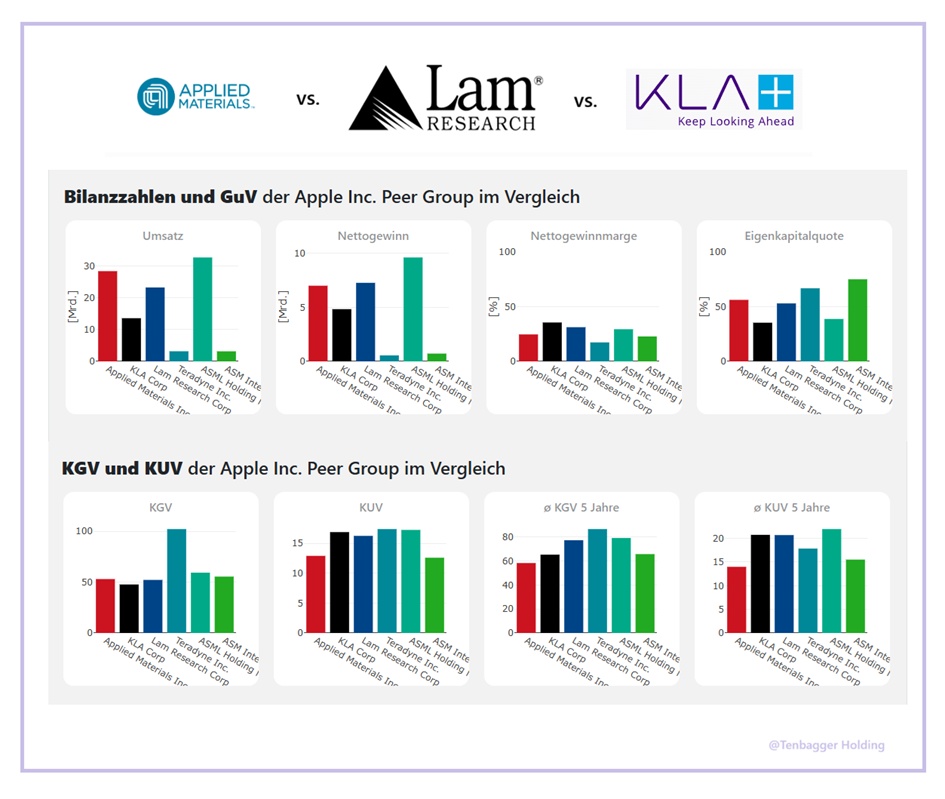
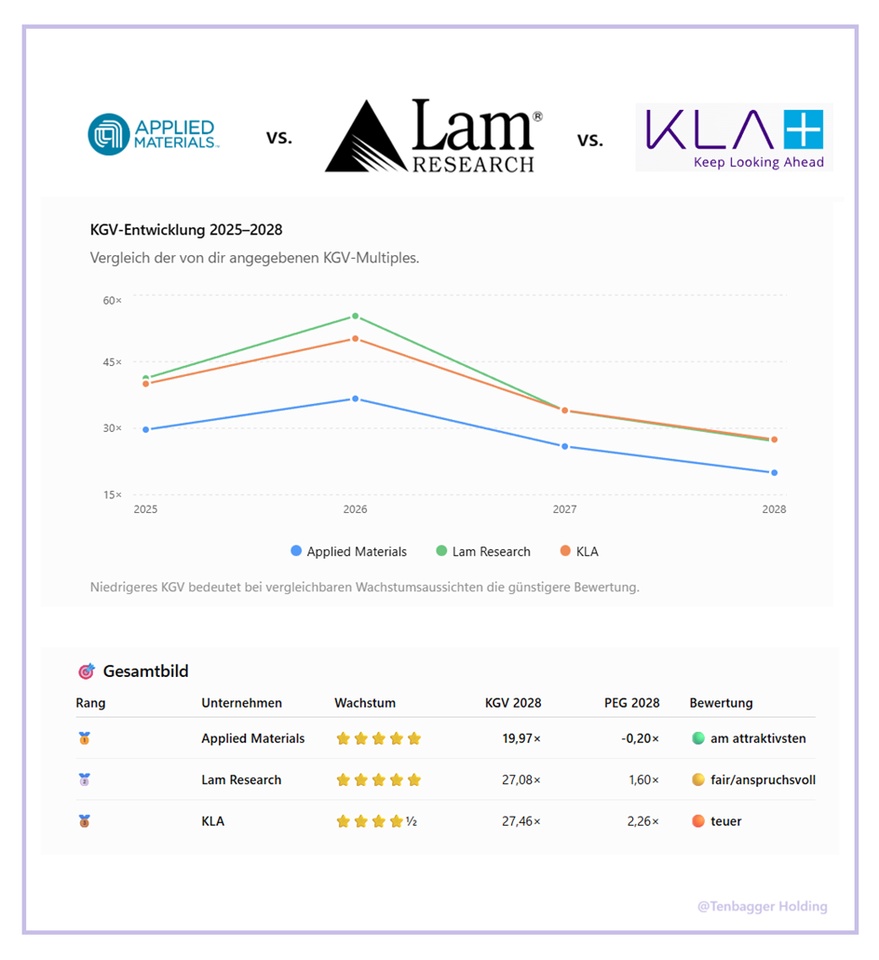
Mein Fazit: Wenn ich die von onVista gelieferten Multiples und Gewinnprognosen betrachte, ist Applied Materials momentan der klare Favorit. Lam Research hat das beeindruckendste Wachstum, aber dieses Wachstum ist stärker im Kurs bzw. Multiple berücksichtigt. KLA erscheint im Verhältnis von KGV zu Wachstum am anspruchsvollsten.
Hinweis: Das negative PEG von Applied Materials 2028 ist auffällig und sollte vor einer Investmententscheidung noch einmal gegen die ursprüngliche MarketScreener-Tabelle geprüft werden.

