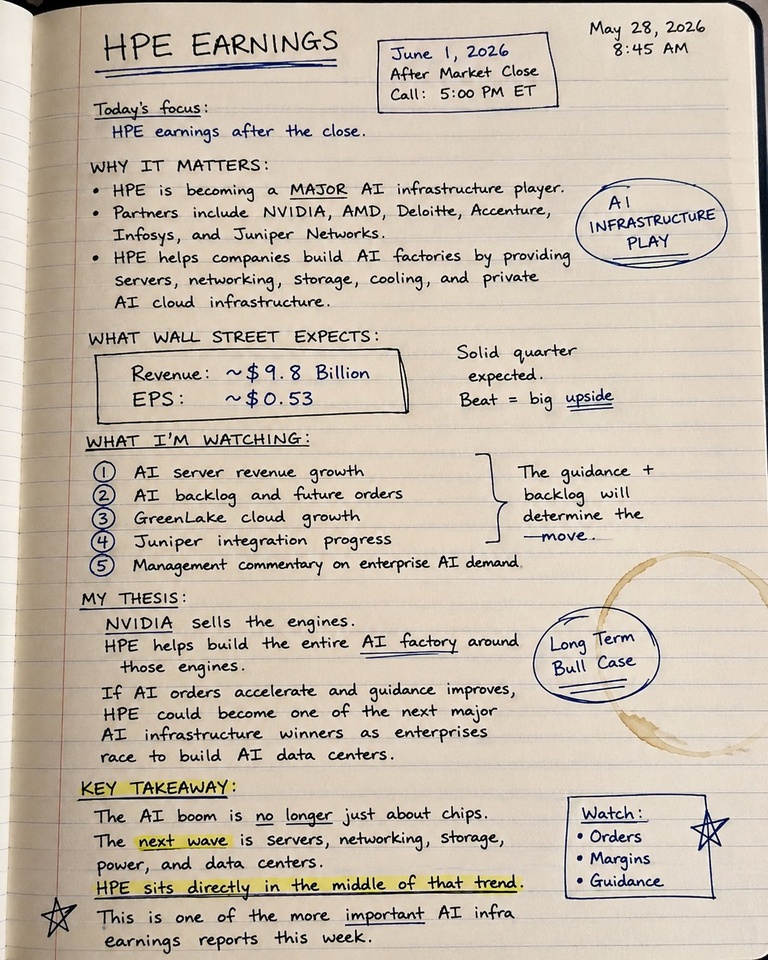
Noone is focused on $HPE (+0,27%) earnings this week.
In 1 month, $HPE spiked 125% from $20 → $45.
Earnings is exactly like $DELL (+0,96%) :
• Revenue expected to surge 28% YoY to $9.77B one of the biggest growth quarters in HPE's history
• Networking revenue already exploded 152% YoY in Q1 Juniper acquisition turned HPE into an AI networking powerhouse
• Data center networking revenue specifically up 382.6% the AI buildout has found its backbone
AI backlog crossed $5B and 64% of orders are enterprise/sovereign, NOT hyperscalers. That's durable, diversified demand
• HPE raised full-year EPS guidance to $2.30–$2.50 and lifted networking revenue growth target to 68–73%
• Networking operating margins hit 23.7% in Q1 if that holds tonight, this stock re-rates immediately
• Q3 is expected to be the biggest AI revenue quarter tonight's print is just the setup, not the peak
• HPE has beaten EPS estimates 88% of the time and revenue 75% of the time the base rate is on the bull's side