As promised, the next stock I want to discuss also operates in emerging market e-commerce. And it actually has quite a few similarities with MercadoLibre: I doubled down last week after earnings, Stanley Druckenmiller is also very bullish on the company, and the valuation is more than attractive.
So let’s address the elephant in the room, the reason I even got the chance to buy more. Why did the stock plunge 20% after earnings?
I think what Sea reported was a very strong quarter on the top-line side. But the key problem remains the same as in recent years: profitability concerns. The company missed EPS expectations by around 15%, and that’s not exactly a one-off. The stock is down more than 55% since last September and has now missed EPS in four out of the last five quarters. Add to that macro pressure, recession fears driven by tariffs and rising oil prices, which hit Southeast Asia particularly hard, and you get the perfect setup for a selloff.
But if you take a step back, the core business actually looks very strong. Sea, similar to MercadoLibre, operates a multi-segment ecosystem where e-commerce through Shopee and fintech form the backbone. Together they account for almost 90% of total revenue and are driving 36% YoY top-line growth alongside roughly 10% free cash flow growth. Garena, the gaming division, is clearly the laggard now, still growing, but only in the single digits and no longer the main story.
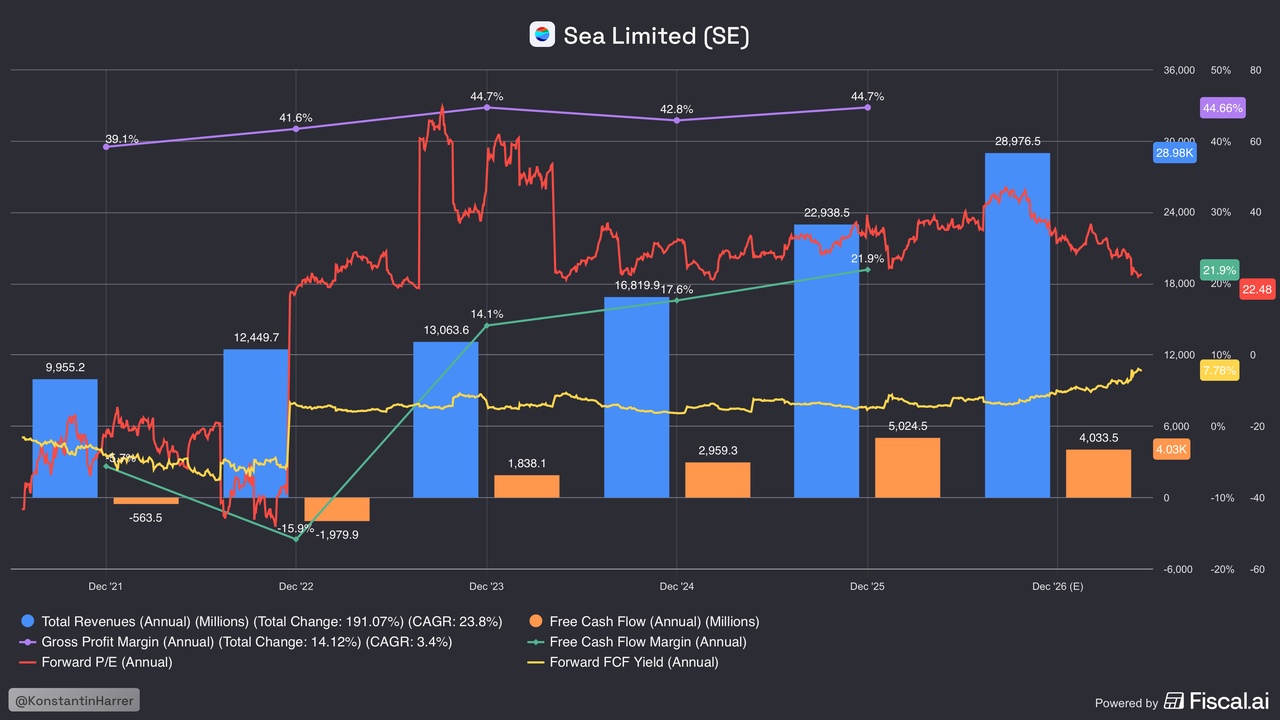
The real story is expansion. Analysts expect mid-20% annual revenue growth through 2027, and based on those estimates, EPS is also supposed to roughly double over that period, although that is obviously the biggest variable. And I think that is exactly where the market gets it wrong.
Just like with MercadoLibre, Sea is not optimising for peak margins right now. The focus is clearly on growth and market penetration, whether that is scaling Shopee across Southeast Asia or pushing further into Latin America. Profitability, which is already improving, comes later. That is the playbook.
Instead, the market sees a 15% EPS miss, ignores the strong revenue growth, and sends the stock down 20%, on top of an already brutal multi-month downtrend. To me, that looks like a clear misunderstanding of the phase the company is currently in.
I’m very bullish here. Profitability absolutely needs to be monitored, no question, but at around a 8% forward free cash flow yield and roughly 22x forward P/E, for a company with this kind of growth profile, I am more than comfortable staying confident.