4D·

Gas Station with a Data Center

$AKER (-3,8%) - I added my first position in Aker to my portfolio today.
attachment

Aker is a Norwegian industrial holding company with deep roots in offshore oil production; however, after various forays into wind power, hydrogen, and CO2 capture (most of these businesses have since been divested or spun off into joint ventures), it is now also a data center operator.


First, the current figures, which sound very promising to me: P/E ratio = approx. 3.5 (!), dividend yield = approx. 4%.

The stock price just experienced a slight dip, which I see as a buying opportunity to finally move the company from my “watchlist” to my “portfolio.”


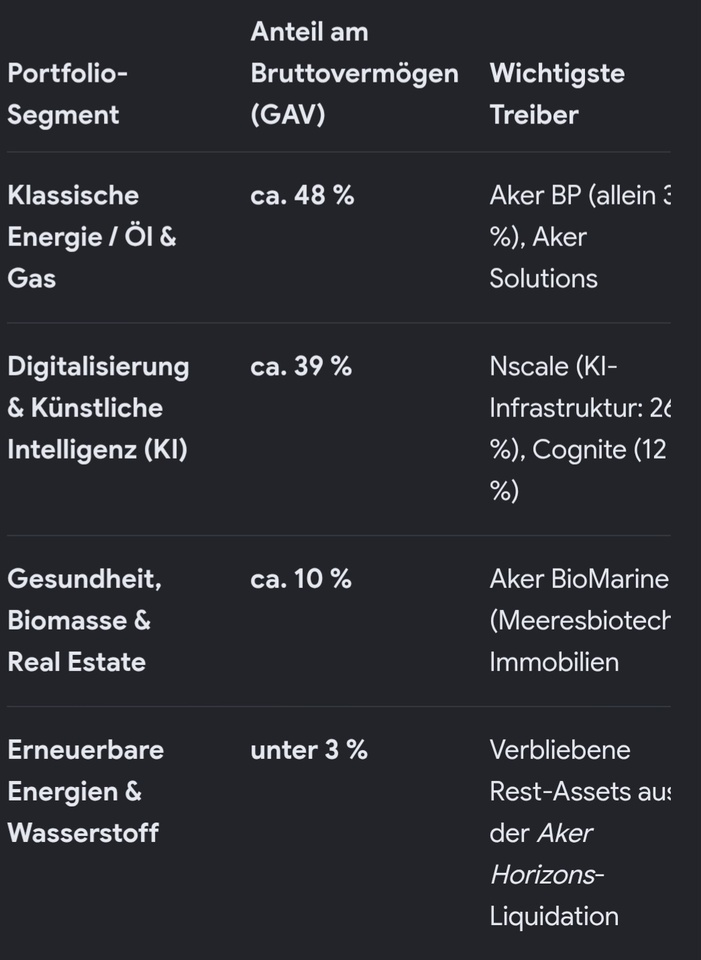
Here is a table showing the breakdown of the business segments:
attachment
15.10
Aker logo
Comprado x15 em € 115,60
€ 1.734,00
17
7 Comentários

imagem de perfil
Aker ASA, a Norwegian industrial holding company with stakes in Aker BP, Aker Solutions, Cognite, Aker BioMarine, and others, is currently very attractively valued on a fundamental basis, but the stock price is technically overheated following an extreme rally. I would be cautious about new purchases; for existing shareholders, there are strong arguments for partial sales or, at the very least, adding to positions only during a correction.

Aker is not a traditional oil company, but rather an actively managed investment company focused on energy, offshore, green technologies, industrial software, and marine biotechnology. Valuation should therefore be based primarily on NAV, dividends, and portfolio performance—the traditional P/E ratio is of limited use here.

NAV Valuation
This is the most important valuation benchmark:
NAV at the end of 2025: 67.26 billion NOK, or 905 NOK per share.

NAV for H1 2026: approximately 106 billion NOK after dividends, an increase of nearly 40 billion NOK.

Current share price: approx. 1,290 NOK.

Price-to-NAV ratio: around 1.43 based on the H1 2026 NAV, assuming the NAV is roughly divided by the number of shares.

This means that Aker is no longer trading at a traditional holding company discount, but rather at a premium to NAV. This is only justified if investors continue to expect strong value growth from companies such as Nscale, Cognite, Aker BP, or other portfolio companies.
•
3
•
imagem de perfil
@Smudeo Thanks for the detailed answer. Do you hold this stock in your portfolio?

Yes, the stock has already performed well, but I think that’s simply because it’s a good company. It would have been nice to have gotten in earlier, but after the recent minor pullback, I felt the time was right for my first purchase. I like its broad, solid portfolio combined with a dash of future-oriented technologies. 🙂
••
imagem de perfil
Sounds like an exciting title. GW—buy it!
•
2
•
imagem de perfil
As for the P/E ratio of 3.5, I would be cautious. Both the 2025 and 2026 figures are skewed upward by one-time effects. In 2025, the deconsolidation of Nscale resulted in a one-time gain of 4.8 billion NOK. And in Q4, the company will most likely recognize another profit of around 7 billion NOK from the sale of Cognite (rough estimate).

So the P/E ratio alone doesn’t really tell us anything about whether the stock is currently undervalued or overvalued. Depending on the source, a P/E ratio of 11–17 is also expected for 2027. 😉
•
1
•
imagem de perfil
@Part_Time_Joe That's true—it's a one-time effect. But the sale of Cognite will also bring in a nice chunk of money, which can then be reinvested in new or existing activities. To me, it all looks relatively solid—so I have few concerns about being invested there for the long term.
You’ve done some detailed research—are you perhaps invested as well?
••
imagem de perfil
@NichtRelevant No, no... I'm not invested. I just saw your post and thought the company was interesting. But I haven't really looked into it in great detail yet. So I don’t feel confident saying whether it’s cheap or expensive right now. I just wanted to point out the P/E ratio issue. That could be misleading 👍🏼
•
1
•
imagem de perfil
@Part_Time_Joe Okay. Thanks anyway for thinking it through and doing the research. 🙂
•
1
•
Participar na conversa