
I have found another exciting company that I really like. 🫡
First of all, they are not yet profitable and two exciting pieces of information:
- Fred Moll, co-founder of Intuitive Surgical $ISRG (+3,58%) and proverbial "father of robotic surgery", is on the board of directors and recently bought shares 👌
- New CEO, Larry Wood (formerly Edwards Lifesciences) - his message right from the start: it's not about breaking even two quarters early, it's about building a sustainable company that can scale for decades by educating patients, expanding awareness and aggressively investing in long-term success.
What does Procept BioRobotics do?
The company makes robotic tools for urologists - high-tech devices to treat enlarged prostates without interfering with sexual or bladder function. The main device, AquaBeam, uses ultrasound and AI-controlled water jets to target and remove the damaged tissue. Highly precise, without lasers or steam as with older methods. Fast, safe and patients recover quickly - a welcome change from conventional procedures.
1/9 The technology advantage: AI meets robotic surgery
The HYDROS robotic system from $PRCT represents the next evolutionary step in surgical robotics. It is the only FDA-approved, AI-powered, image-guided, robotic and heat-free waterjet system for prostate tissue resection. This is not an incremental innovation, but a paradigm shift in precision medicine.
2/9 FirstAssist AI: groundbreaking differentiator
FirstAssist AI is based on a library of over 50,000 real-world aquablation procedures and uses advanced image recognition to automatically identify critical anatomical areas in ultrasound and suggest optimal treatment plans for each patient. This AI-driven treatment planning ensures consistency for prostate conditions of all shapes and sizes and standardizes outcomes regardless of surgeon experience.
3/9 HYDROS: AI and robotics
The HYDROS system combines three groundbreaking components: (1) AI-powered treatment planning via FirstAssist AI (2) Advanced image guidance that integrates next-generation ultrasound with digital cystoscopy on two HD touchscreens (3) Robotic resection with heatless waterjet that executes surgeon-defined plans while protecting critical anatomy.
4/9 Clinical superiority and conservation advantage
Unlike traditional TURP or laser therapies, aquablation preserves sexual function and continence. Clinical studies show a 16-point improvement in IPSS with a 5-year durability. Radical prostatectomy causes erectile dysfunction in 20-55% of patients and incontinence in about 20%. Aquablation has an improvement rate in the low single-digit range to 0%.
5/9 The financial dynamics are undeniable
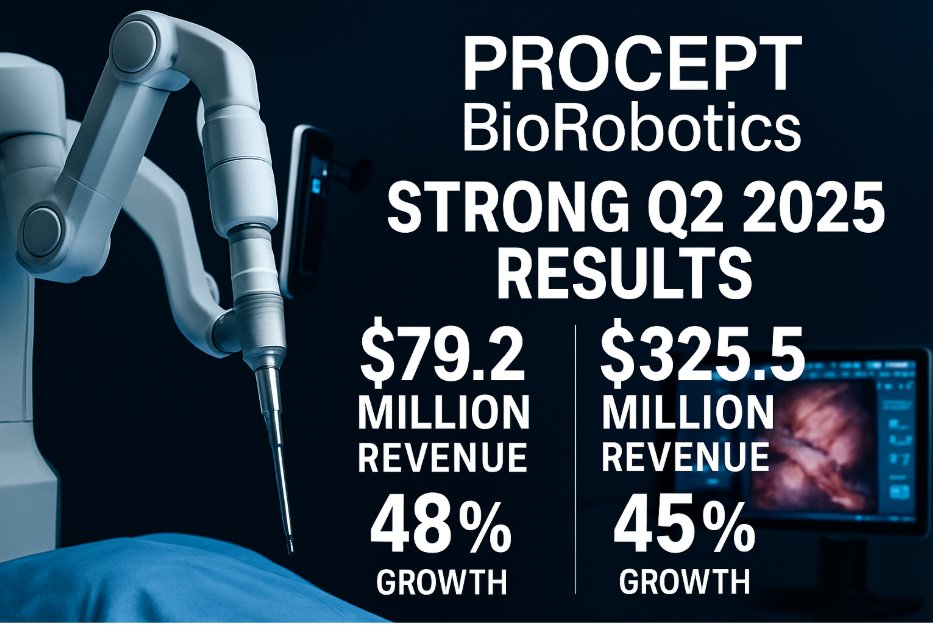
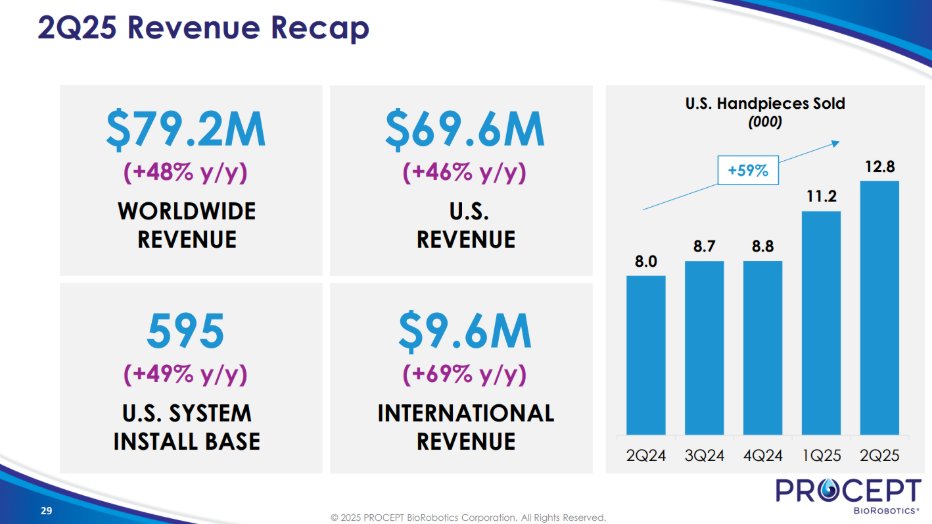
- Q2 2025: USD 79.2 million in sales (+48% year-on-year)
- Sales of handpieces/consumables: USD 43.1 million (+58% year-on-year)
- Gross margin: 65% (compared to 59%)
- 51 new US systems sold, 595 total installed base
- International sales: USD 9.6 million (+69% year-on-year)
- Cash on hand: USD 306 million, no significant debt
The forecast for financial year 2025 has been raised to USD 325.5 million (+45 % growth)
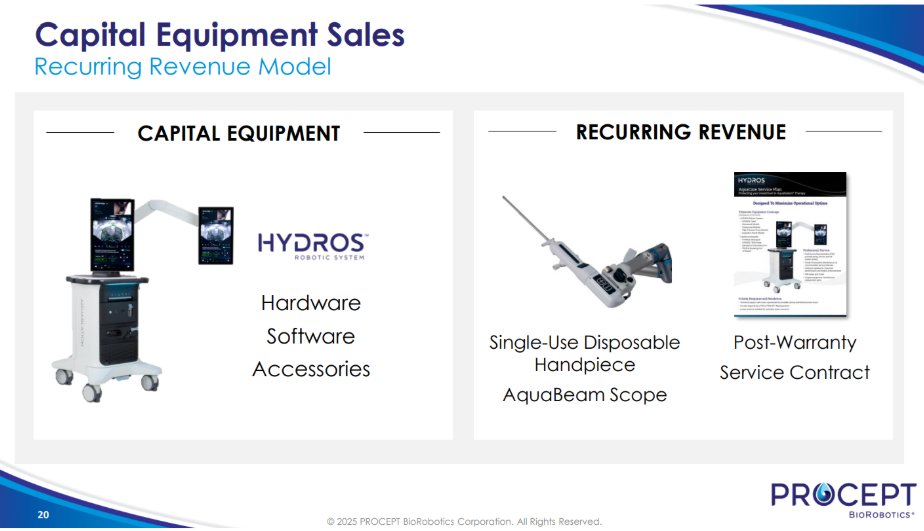
The installed base is accelerating - each system generates around USD 150,000 per year in recurring consumables revenue. With 595 systems in use, this equates to annual revenue of around USD 89 million from consumables alone, which corresponds to growth of 58% compared to the previous year.
6/9 International expansion: first steps towards a global launch
International sales increased by 69 % in the second quarter, driven primarily by the UK, Japan and Korea (approx. 70 % of international sales). The UK market is experiencing particularly strong demand. The global installed base is 762 systems. The BPH market is global - over 50 million men are affected worldwide and market penetration is less than 1%. So there is still a lot of potential ahead of us.
7/9 The catalyst for prostate cancer: a multi-billion dollar opportunity
October 2024: FDA grants IDE approval + breakthrough device status for the WATER IV PCa trial comparing aquablation to radical prostatectomy for localized grade 1-3 prostate cancer. This is huge . No other energy-based treatment has a prostate cancer-specific indication.
The WATER IV PCa trial involves 280 patients in 50 centers. The primary endpoints are after six months (incontinence/erectile dysfunction) and oncological follow-up after ten years. The primary study is expected to be completed in July 2027. Analysts predict a possible FDA approval in 2026-2027, which will open up a market worth over 500 million US dollars. Three procedures in the ASC setting have already been performed and discharged on the same day.
8/9 Intuitive Surgical ($ISRG (+3,58%) ) connection
Fred Moll, co-founder of Intuitive Surgical ($ISRG (+3,58%) ) and proverbial "father of robotic surgery", sits on the board of $PRCT . He founded $ISRG (+3,58%) in 1995, pioneered the da Vinci system (over 9,200 systems generating billions annually) and sold Auris Health in 2019 for 5.75 billion dollars to $JNJ (+4,08%)
On August 13, 2025, Moll bought 20,000 shares at USD 39.26 on the open market, increasing his holdings to 863,159 shares. When the architect of robotic surgery buys your stock during a 66 percent drop in the open market, that's a signal. His track record speaks for itself - he knows what groundbreaking surgical robotics looks like.
9/9 The surgical robotics playbook
- First-mover advantage in AI-powered BPH robotics with over 10 years of R&D and patent protection into the 2030s; and clinical superiority with functional preservation.
- Recurring revenue model (consumables growing 58%) , expanded margin profile (65% gross margin) and strong balance sheet ($306 million in cash)
- New CEO Larry Wood from Edwards Lifesciences (TAVR division with over USD 5 billion)
- BPH market: over USD 21 billion by 2033, current market penetration <1%; 400,000 BPH surgeries annually in the US alone
- International expansion accelerating (69% growth)
- Catalyst for prostate cancer trials (data from 2027, potential approval 2026-2028)
- ASP increasing (average USD 460,000 2024), targeting profitability (Q4 approaching EBITDA breakeven)
In summary, despite improving fundamentals, the stock is down 66% from its highs and I made my first buy on NASDAQ today. ✌️
PROCEPT BioRobotics Reports Third Quarter 2025 Financial Results and Issues 2026 Revenue Guidance - PRCT - BioPharmCatalyst
Recent Highlights
- Total revenue of $83.3 million for the third quarter of 2025, an increase of 43% compared to the prior year period in 2024
- U.S. handpiece and consumables revenue of $44.4 million for the third quarter of 2025, an increase of 50% compared to the prior year period in 2024
- The installed base in the U.S. increased by 58 robotic systems in the third quarter of 2025
- U.S. system and rental revenue of $24.7 million for the third quarter of 2025, an increase of 26% compared to the prior year period in 2024
- International revenue of $9.4 million for the third quarter of 2025, an increase of 53% compared to the prior year period in 2024
- Maintained fiscal year 2025 total revenue guidance of approximately $325.5 million, an increase of 45% compared to the prior year period in 2024
- Issued fiscal year 2026 total revenue guidance in the range of $410 to $430 million, representing growth of 26% to 32% compared to fiscal 2025 revenue guidance of $325.5 million.
"In my initial weeks as CEO, I am pleased to report we delivered a strong performance. We accelerated U.S. system placements, demonstrating strong demand for the HYDROS® Robotic System, and achieved 43% year over year global revenue growth," said Larry Wood, chief executive officer. "This quarter's results underscore the strength of our business and the growing adoption of Aquablation therapy. My first two months at PROCEPT have only deepened my confidence in our significant growth potential. We remain focused on expanding awareness of Aquablation® therapy, driving patient activation and advancing our mission."
Third Quarter 2025 Financial Results
Total revenue for the third quarter of 2025 was $83.3 million, an increase of 43% compared to the prior year period. U.S. revenue was $73.9 million, representing growth of 42% compared to the prior year period. The increase was primarily driven by system sales to new hospital customers and increased handpiece revenue. U.S. handpiece and consumable revenue for the third quarter of 2025 was $44.4 million, an increase of 50% compared to the prior year period. U.S. system revenue for the third quarter of 2025 was $24.7 million, an increase of 26% compared to the prior year period. As of September 30, 2025, the install base of robotic systems in the U.S. was 653 systems. International revenue was $9.4 million for the quarter, an increase of 53% compared to the prior year period.
Gross margin for the third quarter 2025 was 65% compared to 63% in the prior year period. Gross margin expansion in the third quarter was due to improved operational efficiencies and overhead absorption, modestly offset by increased tariff expenses.
Operating expenses in the third quarter of 2025 were $77.2 million, compared with $59.3 million in the prior year period. The increase in operating expenses was primarily due to expenses to expand the commercial organization, increased research and development expenses, increased general and administrative expenses, and one-time expenses associated with the executive leadership transition.
Net loss was $21.4 million for the third quarter of 2025, compared to a loss of $21.0 million in the prior year period. Adjusted EBITDA was a loss of $7.4 million for the third quarter of 2025, compared to a loss of $12.4 million in the prior year period.
Cash, cash equivalents and restricted cash balances as of September 30, 2025, totaled $297.3 million.
Full Year 2025 Financial Guidance
- The Company reiterates revenue for the full year 2025 to be approximately $325.5 million, which represents 45% growth over the Company's prior year revenue.
- The Company expects full year 2025 gross margins in the range of 64.0% to 64.5%. The Company expects a gross margin headwind of approximately $2.0 million in the fourth quarter, attributable to tariff-related costs.
- The Company reiterates full year 2025 total operating expense of approximately $302.0 million.
- The Company reiterates full year 2025 Adjusted EBITDA loss to be approximately ($35.0) million.
Full Year 2026 Financial Guidance
- The Company projects revenue for the full year 2026 to be in the range of $410 to $430 million, which represents growth of 26% to 32% over the Company's 2025 revenue guidance range.
Adjusted EBITDA is a financial measure that is not prepared in accordance with generally accepted accounting principles in the United States (GAAP). For more information about the Company's use of non-GAAP financial measures, please see the section below titled "Use of Non-GAAP Financial Measures (Unaudited).


