

TJX Companies is the world's largest off-price retailer of fashion, home goods, and everyday products for people and pets.
$TJX (-1,15%) purchases surplus inventory, excess inventory etc. directly from brand manufacturers and designers at affordable prices. Often because these companies don’t
sell
sell in time. The manufacturers and designers have to constantly bring out new collections and don’t always have time to sell everything…
and that’s when TJX steps in.
Through bulk purchases and flexible contracts , TJX gets these brand-name products at a discounted
prices.
The savings are $TJX (-1,15%) to the customers . In most cases, the products are 20% to 60% cheaper than the regular comparable prices.
That’s why TJX is always so affordable… and yes, the brand-name products there are genuine… you wouldn’t always think so given the prices, would you? 😄
The selection at $TJX (-1,15%) is constantly changing. So always something new on offer.
The Treasure Hunt principle.
The Treasure Hunters keep coming back to check for a product to discover and snagbefore someone else snatches it up.
The early bird catches the worm.
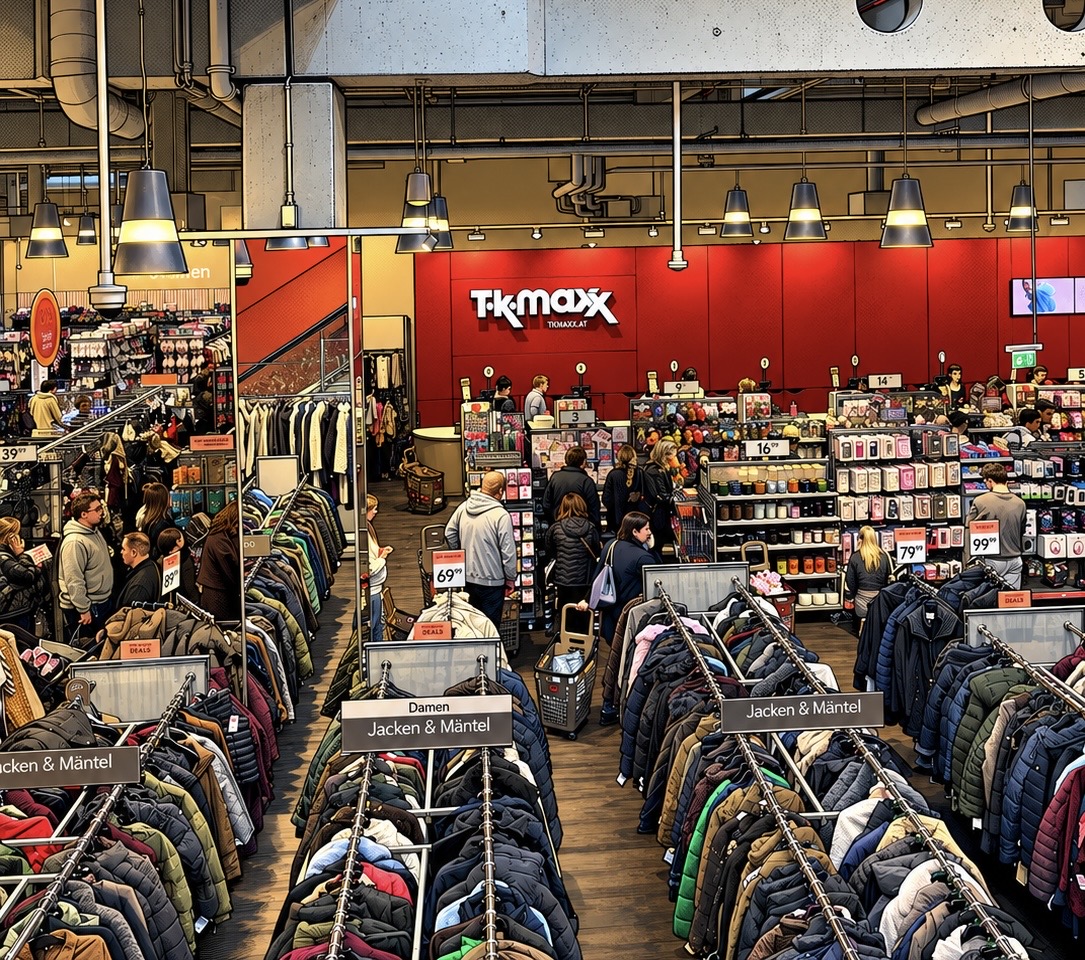
I took this photo at TK Maxx myself yesterday and used AI to turn it into a comic to show how crowded it is there and how long the line at the register is.
Crazy
That’s business model works well in times of high inflation, because customers want to , and in times of low inflation, because consumers are once again are willing to spend more and still prefer to shop .
Win-win, right?
- Revenue growth: Approx. 6% to 8% annual average. Steadily rising
- Gross margin: on average 35% to 37%.
- Profit growth (net income): Approx. 10% to 15% on average, supported by operational efficiency.
- Return on equity is usually between 30% and over 50%. Very efficient.
- The dividend was in 2020 due to COVID-19 in 24 years of steady increases cut, as revenue has plummeted … which makes sense. Let’s briefly recall the FFP2 masks😷 Personally, I’m turning a blind eye to this because, after 2020, the dividend returned to the its previous level and has been steadily increased
- The average annual dividend growth over the last 20 years has been over 15%! Over the past 10 years, it has been approximately 15% to 16%. A true dividend compounder.
- The payout ratio is approximately 32% to 35%. Very healthy.
My thoughts on TJX:
Every time I walk through the stores, I’d love to buy everything , which means I want to buy the company. Which means I want to own the stock. 😋
$TJX (-1,15%) It felt like never had the problem of customers rarely stopping by.
It’s always packed! Somehow, it always is!
There’s literally a traffic jam at the checkout counters. No matter where I look… the behavior of the customers. They don’t just shop and leave. They go to pass the time , spend their time there, and talk to each other, look at the products… and then buy something because they find something interesting at a good price. Or simply out of boredom?
Just brilliant.
From brand-name clothing to kitchen products, toys, furniture and household goods to electronics… simply everything.
Many would say that the stock is overvalued. But you could have seen that coming over the past 15 years time and again. Whenever people thought they’d suffered a drawdown was finally cheap , it was back well above the low.
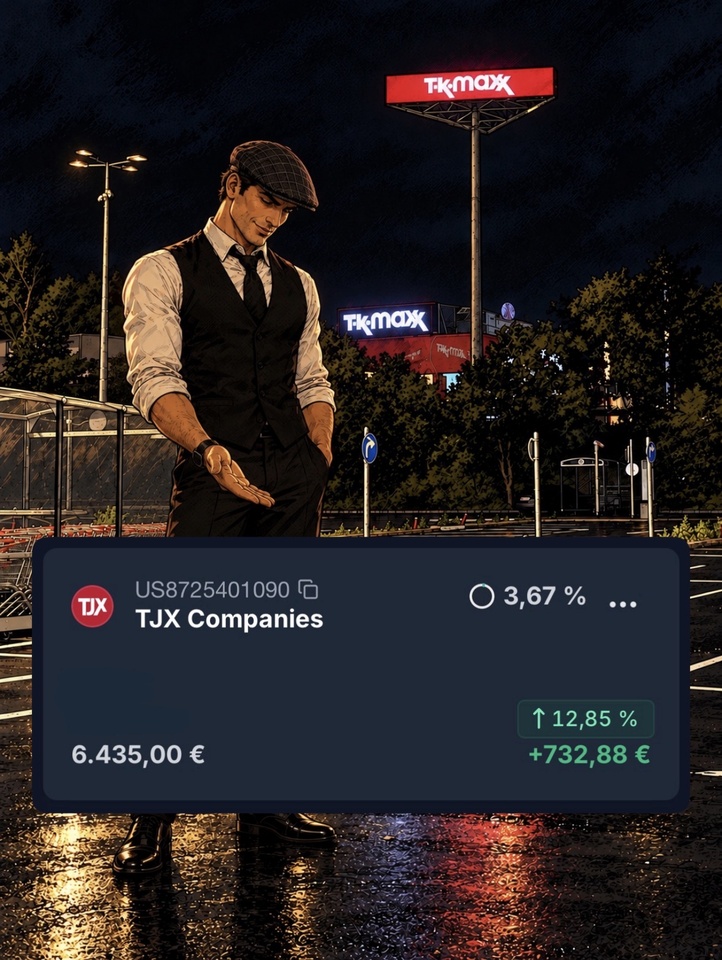
So I figured I’d just jump in instead of just just watching…
You hear so little about $TJX (-1,15%) and I think that’s a good thing. The company can deliver at a relaxed pace without constant fuss, headlines and anxiety.
By now, my opinion… when there’s there’s too much talking , one should be … aka $MCD (-1,58%) recently. First, there’s a lot of talk, then comes the panic.
The P/E ratio for the stock is currently around 28. The average over the past few years is roughly >30.
My entry point was $TJX (-1,15%) was around €109, at a P/E ratio of about 26.
Yes, for me, this is actually a bargain
Are you an investor in TJX? Are you thinking about becoming one? Or do you steer clear of the company? Let me know! 😄💪🏽
❗️Not a buy recommendation❗️


