
I have looked at many different REITs, for example Realty Income $O (+0,16%) Omega Healthcare Investors $OHI (+0,19%) , NNN REIT $NNN (+0,41%) , Agree Realty $ADC (+1,19%) Alexandria Real Estate Equities $ARE (+0,73%) and of course Simon Property Group $SPG (+1,37%) . In my opinion, there is little or very little equity research on Simon Property Group.
Therefore, for today's analysis, I have chosen for Simon Property Group.
Why Simon Property?
Simon Property is market leader in large shopping centers and premium outlets.
The company doesn't just own buildings.
It owns high-quality properties in very good locations.
And it is precisely these locations that are particularly important for strong brands and luxury companies.
The portfolio
Simon Property owns a total of 254 properties:
- 92 large shopping centers
- 70 premium outlets
- 14 mills centers
The properties are located in 37 US states and additionally in 14 countries worldwide.
The occupancy rate is currently 96,5 %.
This is the highest value for 8 years.
The so-called Mills-Center even had an occupancy rate of 98,8 %.
This shows quite clearly:
The spaces are in great demand.
Focus on luxury
Many well-known luxury brands have opened new stores in 2024.
- Gucci, Louis Vuitton, Chanel: In outlets such as Woodbury Common (NY).
- Tiffany & Co, Rolex, Hermès: Focus on watches and jewelry in lifestyle centers.
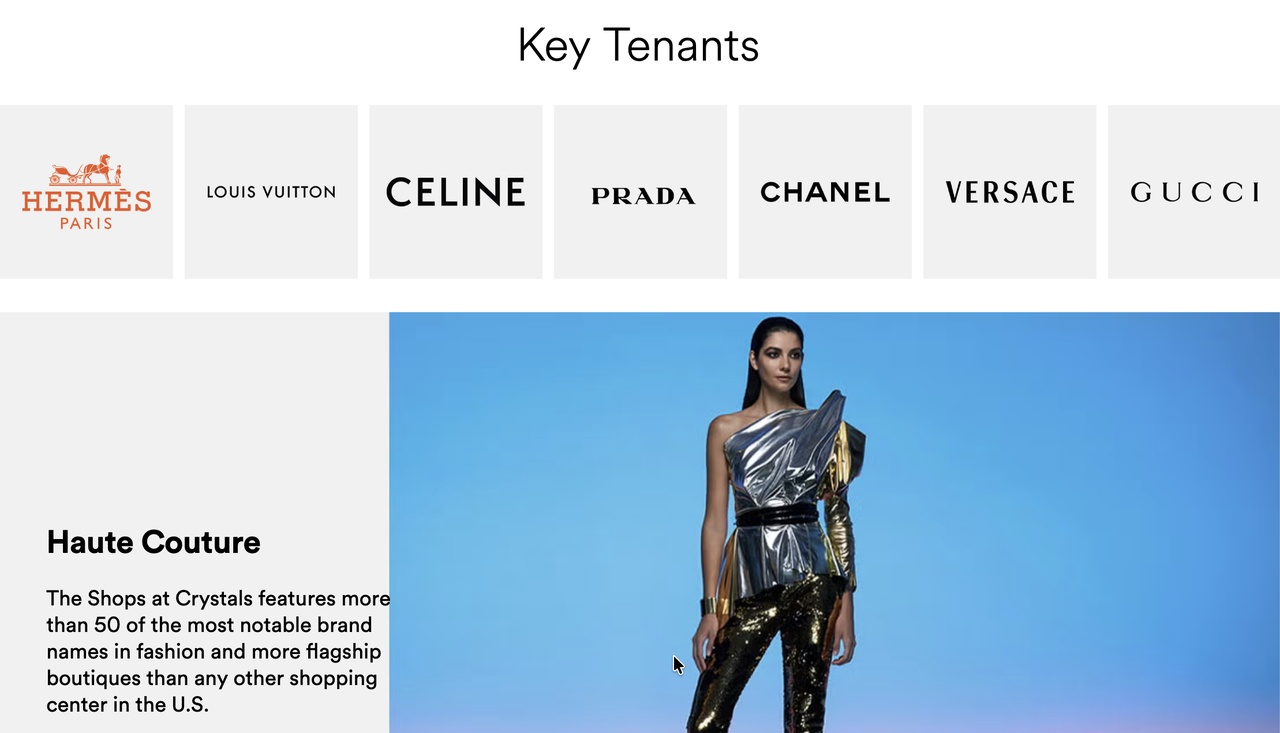
- Hermès, Louis Vuitton, Céline, Prada, Chanel, Versace and Gucci are classic tenants
Why is this important?
Luxury products often work better in better in a real store than online.
People want to see to see, touch and experience them.
And that's exactly what Simon Property benefits from.
Strong regions
A large proportion of the income comes from economically very strong regions:
- Florida
- California
- Texas
These are regions with a lot of tourism, high purchasing power and a strong economy.
Let us now turn to one of the most important key figures for REITs: FFO.
With REITs, you don't look at not look at the normal profit.
Instead, you look at FFO or AFFO.
Why is that so?
REITs have very high depreciation on their real estate.
This depreciation pushes the profit on paper down sharply on paperalthough the company actually earns good money.
This is why the normal profit of REITs not very meaningful.
There is also a special feature:
A REIT must distribute at least 90 % of its profits as dividends.
Therefore, classic key figures such as the P/E RATIOor the payout ratio measured by the EPS or free cash flowfor REITs do not really make sense.
Instead, investors mainly look at FFO and AFFO.
Or the payout ratio based on FFO or AFFO
These key figures show better how much money the company really earns.
Valuation of the share
Let us now turn to the valuation of the share.
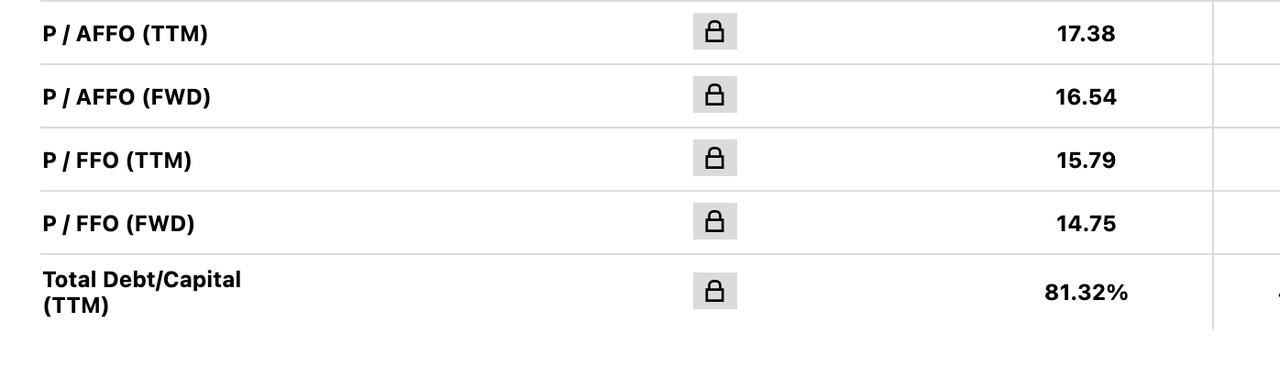
The share is currently valued at a price-to-AFFO ratio of 17.38 .
If we look into the future, the forward price-to-AFFO is around 16.54.
Put simply, this means that
If you buy the share today, you will pay around 16.5 times the expected profit.
For a high-quality REIT, that is not an expensive valuation.
Let's move on to dividend sustainability
Currently Simon Property Group at a price of approximately 194.83 dollars per share per share.
The company currently pays a dividend of dividend of 8.55 dollars per share.
This results in a dividend yield of approximately 4.40 %.
Let's now take a look at whether this dividend is also sustainable is sustainable.
Over the last 12 months, the company has generated an AFFO of 10.58 dollars per share per share.
If we compare the dividend with this figure, we arrive at an AFFO payout ratio of around 80.8%.
This means that around 80 % of the operating cash flow are paid out as dividends.
And for a REIT a solid valuebecause many REITs have a payout ratio of up to up to 90 % have.
In other words:
Simon Property's dividend currently looks well covered and relatively secure.
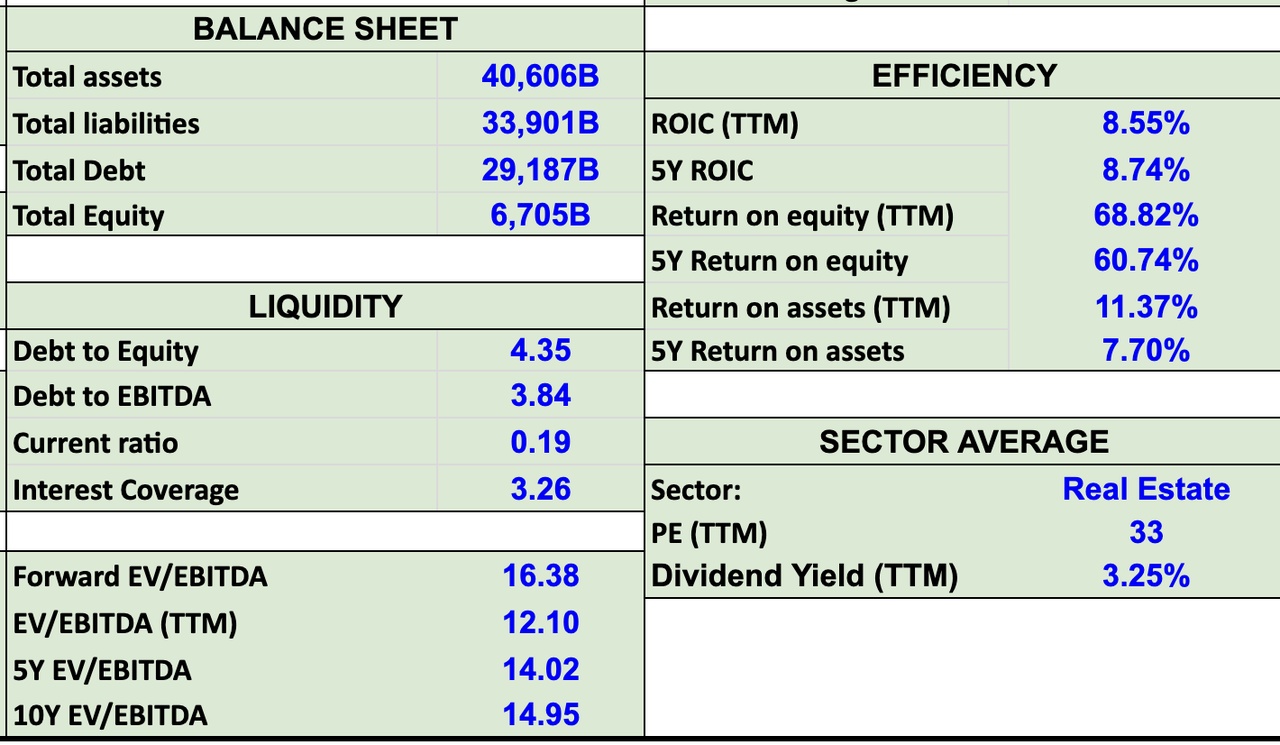
Now we come to a very important key figure for REITs: the leverage ratio.
Here we look at how much equity and how much debt capital a company uses.
This is particularly important because real estate companies often work heavily with borrowed capital.
The current gearing ratio is 3,26.
That means approximately:
- 23 % equity
- 77 % debt capital
That sounds relatively high at first. But if we look at the interest coverage ratio of 3.26 it becomes more reassuring again.
This means that the interest payments are well covered and there is still a safety buffer.
To categorize: Many analysts see values of above 2 to 3 are already considered solid.
My personal buy consideration
But now comes the crucial question: At what price would I buy myself or buy more?
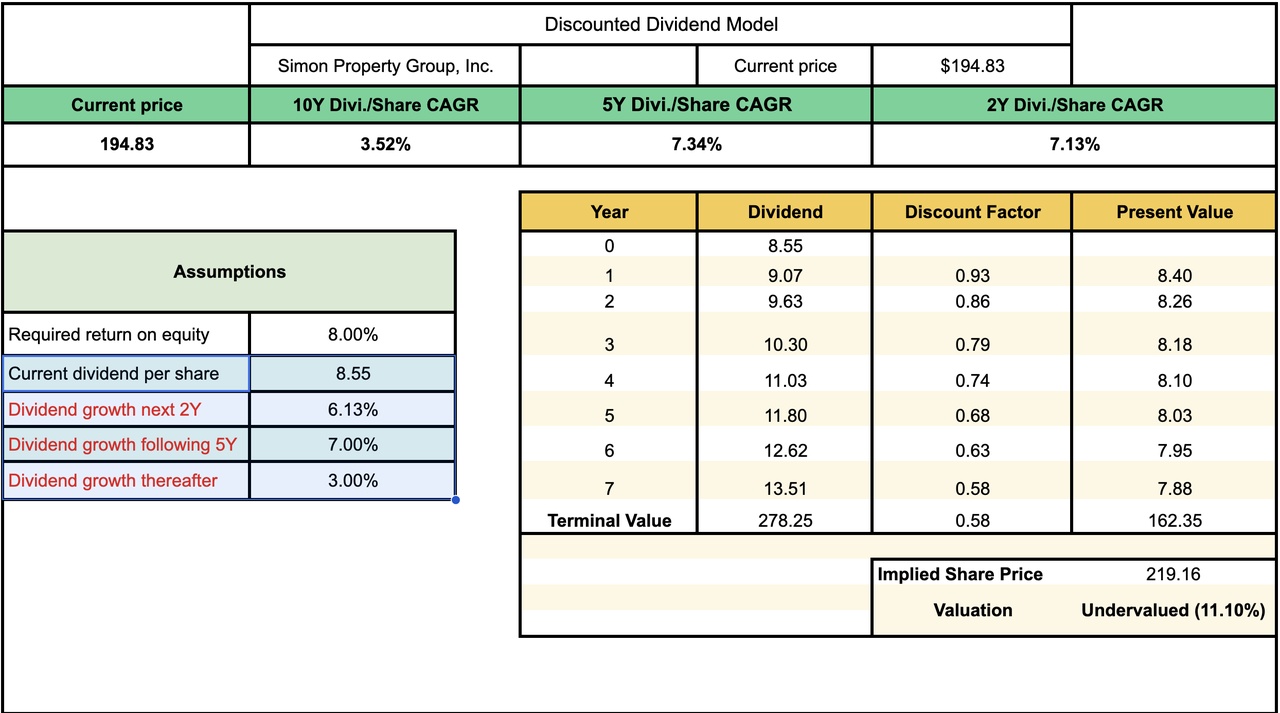
For this I use a dividend valuation method.
Simon Property's dividend has grown in recent years:
- 10-year growth: 3,52 %
- 2-year growth: 7,13 %
The current dividend is around 8.55 dollars per share.
For my calculation I take
- a discount rate of 8%
- dividend growth of
- 6.13 % in the next 2 years
- 7 % in the next 5 years
- thereafter in the long term 3 % growth
With these assumptions, I arrive at a result:
The share is currently approximately 11 % undervalued.
Conclusion
Simon Property offers:
- high-quality real estate
- very high occupancy rate
- stable income
- an attractive dividend
For me, Simon Property is an interesting opportunityfrom the trend towards shopping and genuine shopping experiences. shopping experiences.
For all those who want to delve even deeper into the world of shares https://www.youtube.com/@Verstehdieaktie/videos