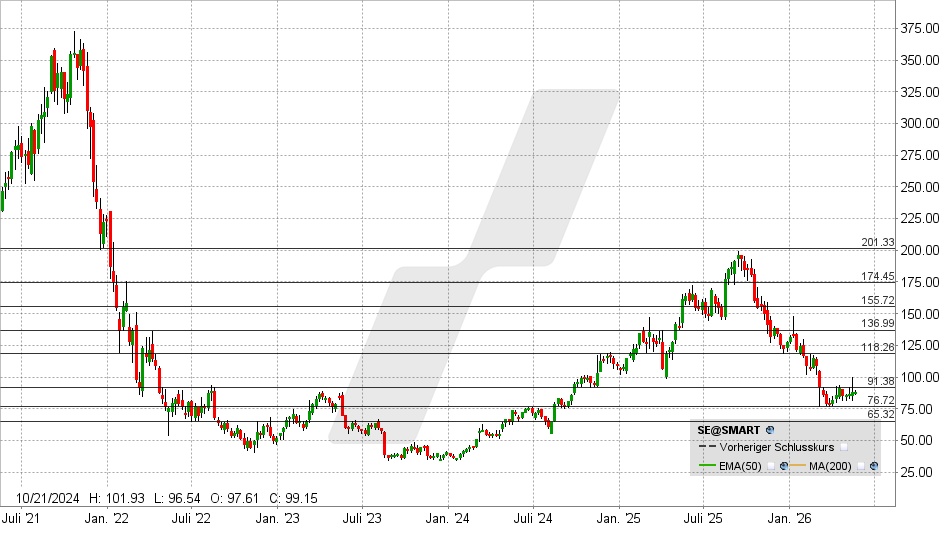
A share falls by 90 %, then rises by 400 % and then crashes again. But beneath the surface Sea just keeps on growing.
From stock market flop to digital superpower
Sea Ltd. is a prime example of how far stock market prices and corporate reality can diverge and how much the share price depends on investor perception.
In 2020, the company began an unparalleled rise. Sea's gaming business exploded and so did the share price. The share was perceived as a crisis winner.
However, when the gaming business collapsed, the company was labeled a loser and an unprofitable growth stock. The share lost around 90% of its value, only to rise by more than 400% and then plummet again.
Anyone looking for examples of extreme price fluctuations and short-term thinking on the Börse should have found it.
Gaming, shopping, fintech
The company was founded in 2009 by Forrest Li under the name Garena. Li is still the CEO and the largest single shareholder of Sea Ltd. Tencent invested heavily in Garena and granted the company preferential access to its gaming portfolio.
This strategic partnership positioned Garena as the leading gaming platform in Southeast Asia. Regional innovations such as AirPay, which allowed users to deposit cash at physical counters for online payments, further strengthened Garena's market position. AirPay later evolved into SeaMoney, the company's financial services arm.
SeaMoney (Monee) is a digital payment processor, supports the online commerce of the other business units and has developed into a fast-growing and profitable business in its own right.
Faced with the underdeveloped e-commerce market in Southeast Asia and inspired by the vision of creating a major internet company in the region, Garena founded the e-commerce division Shopee in 2015. Shopee, which is modeled on the likes of Alibaba and Amazon has developed into one of the largest e-commerce platforms in Southeast Asia and is now the most important business segment of Sea Ltd.
Three pillars
Sea thus consists of three business areas that are characterized by different dynamics.
From my point of view, the payment area could become a real cash cow in the long term, especially in a gigantic market. From a distance, it is easy to underestimate the upswing that the ASEAN countries, with their almost 700 million inhabitants, have experienced. Anyone who has not experienced cities like Kuala Lumpur or Singapore up close can hardly imagine it.
And while Sea's share price is going haywire, the company continues to grow unabated.
In the last five years, turnover has increased significantly from USD 9.96 billion to USD 22.94 billion. At the same time, profitability has improved significantly. The operating margin climbed from around -16% to +9%.
The company has been profitable since 2023. Earnings have increased from USD 0.25 to USD 3.50 per share in this short period. However, the focus is still on growth and not on maximizing profits. At the stage the company is at, given the penetration and size of the markets in which Sea is active, it would be a good MärkteSea is active in, this would not make sense.
The ASEAN countries have almost as many inhabitants as the EU and the USA combined.
What really matters?
The stock market currently takes a different view. Sea has missed profit expectations twice in the last four quarters, but has consistently exceeded them in terms of sales.
This has been enough to cause the share price to plummet from around USD 200 to below USD 100.
However, given the current growth, one could just as easily argue that the company does not need to be profitable at all to derive an investment case.
However, Sea is convincing at this point. It is a growth company with three divisions, each of which is profitable.
As we have known for a few days, earnings of USD 0.67 per share in the last quarter were below expectations of USD 0.74. However, with sales of USD 7.10 billion, analysts' estimates of USD 6.95 billion were clearly exceeded.
For the year as a whole, this corresponds to a 47% increase in sales and a 3% rise in profit.
The e-commerce segment Shopee recorded growth of 45.1% to USD 4.5 billion.
However, EBITDA declined from USD 264.4 million to USD 223.2 million.
Depending on the perspective
The payment business recorded a 57.8 % jump in sales to USD 1.2 billion. EBITDA climbed by 14% to USD 275.2 million.
The Gaming segment increased revenue by 40.6% to USD 696.6 million. EBITDA improved by 25.2% to USD 573.6 million.
Growth is significant in all three segments. Where it makes sense, i.e. in the Gaming segment, management is focusing on profitability, while Shopee and SeaMoney are focusing on growth.
According to consensus estimates, earnings are likely to stagnate in the current financial year. Sea therefore has a P/E ratio of 26, but the question arises as to whether earnings are the right benchmark for a company at this stage.
The P/E ratio currently stands at 2.2 and is likely to fall to 1.8 by the end of the year. Since the Börsengangalmost ten years ago, the P/E ratio has averaged 5.8.
Sea Ltd. share: chart from 19.05.2026, price: USD 88.29 - symbol: SE | source: TWS
If a breakout above USD 91 is now successful, a procyclical upward trend Kaufsignal with possible price targets at USD 100 - 104. Above this, the path towards USD 118 would be clear.
If, on the other hand, the share falls below USD 76, further price losses towards USD 65 must be expected.
Source