

Hello, everyone,
I've been monitoring the correction among semiconductor equipment manufacturers for weeks now.
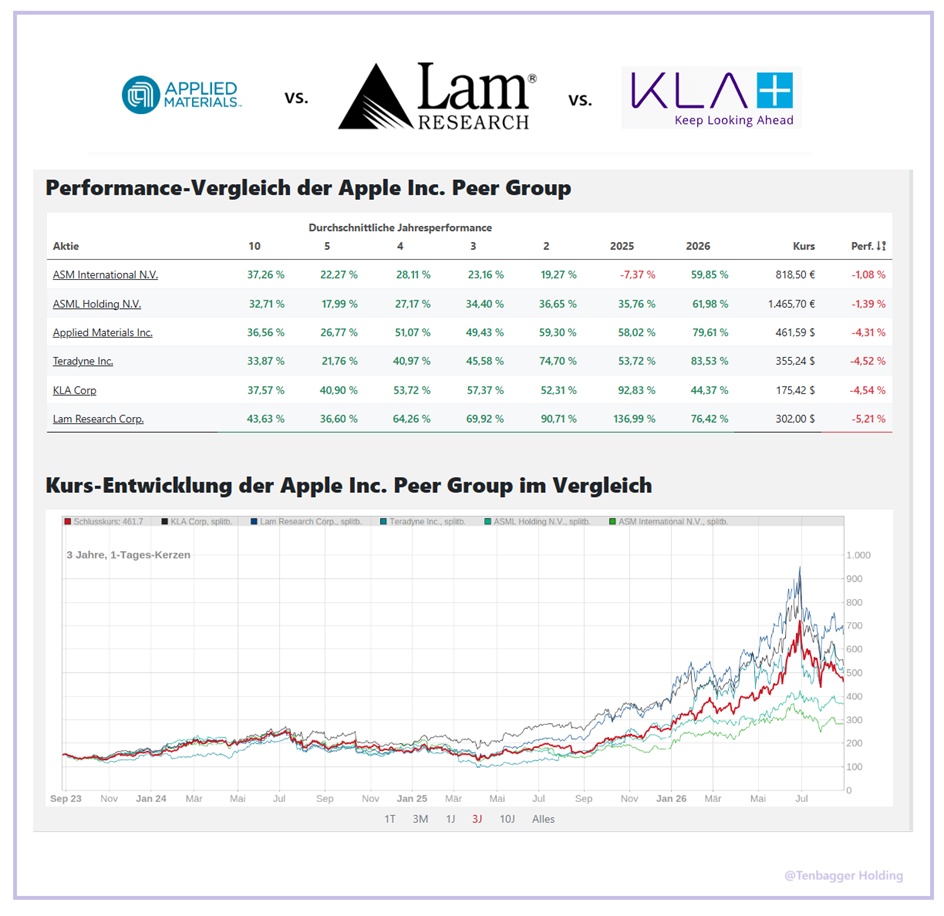
And a brand-new analysis by the agents at @Raketentoni has identified these stocks as current long-term picks.
Further proof of their reliability is that our star investor @Simpson has been invested here for years.
That’s why, my friends, I’ve put together a comparison for you this weekend.
Please let me know in the comments how you like this type of comparison and whether you’d like to see more of it.
In a future post, there will be a poll. Feel free to select your top pick there.
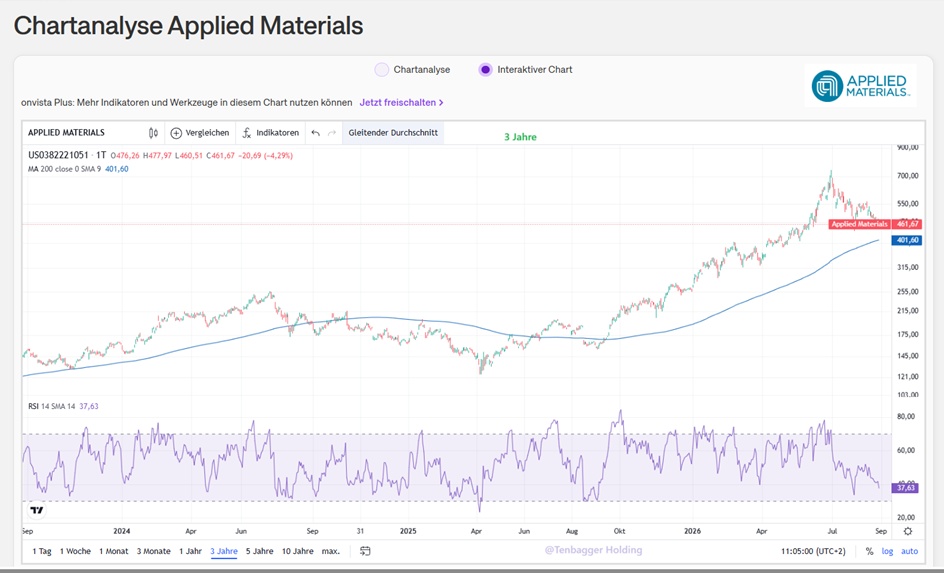
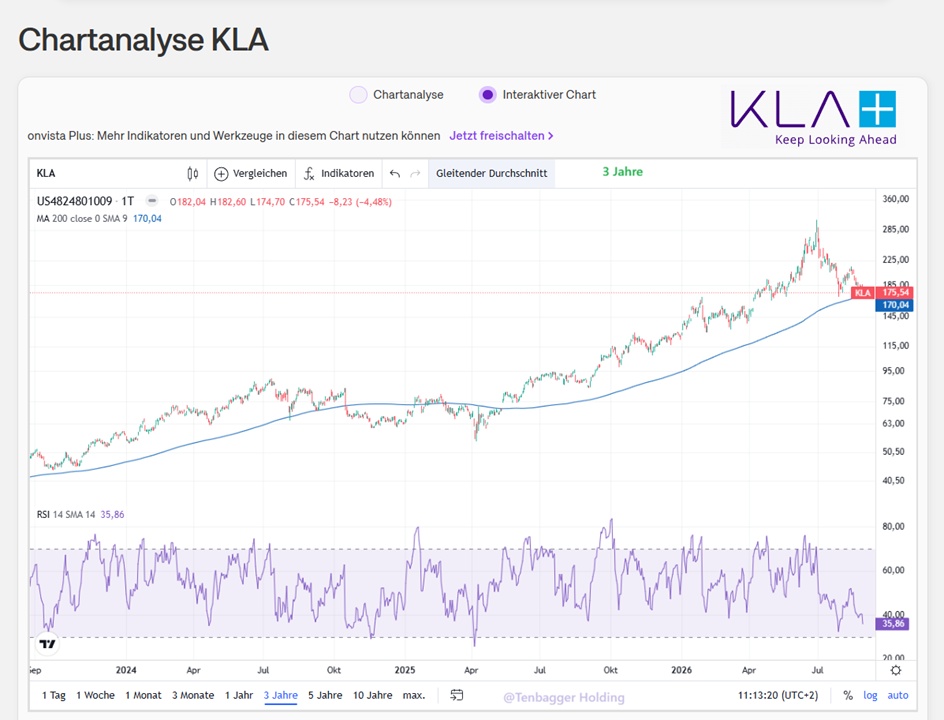
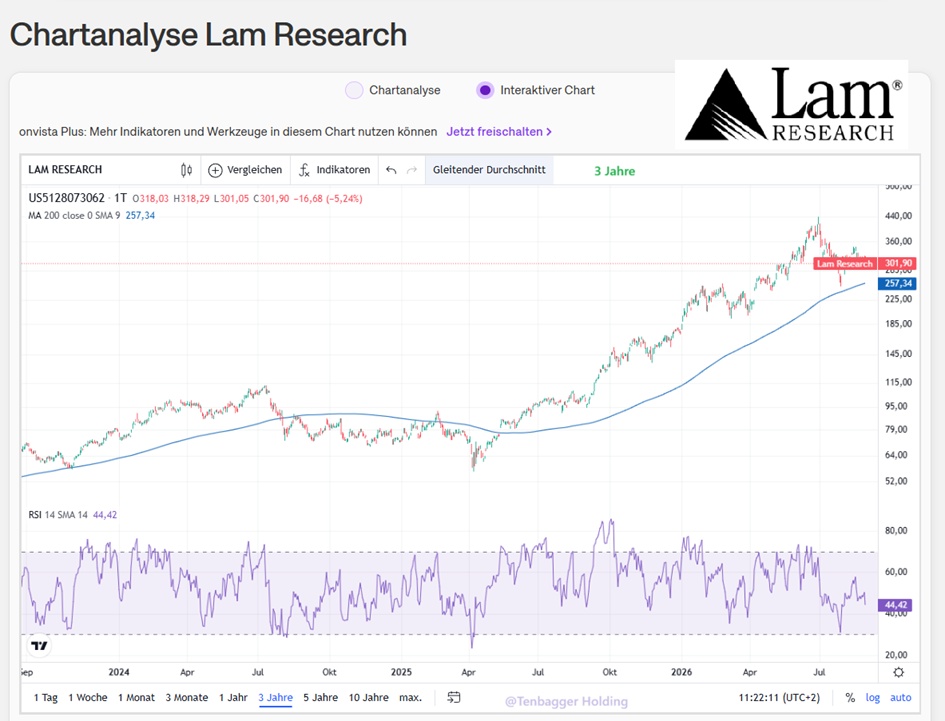
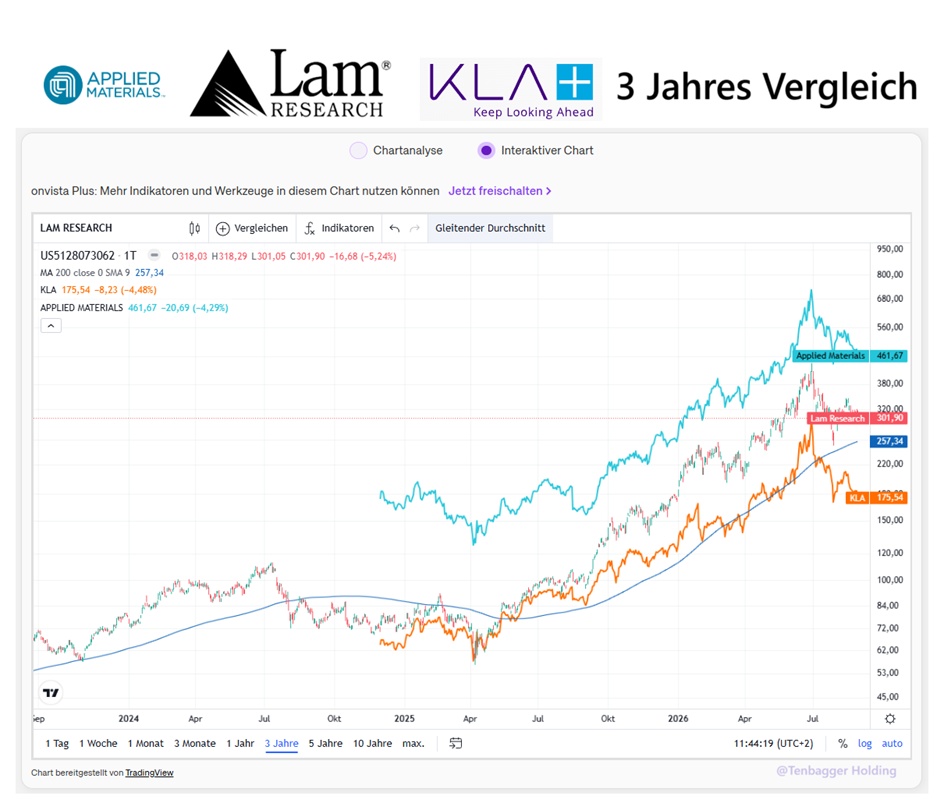
🏆 My ranking of the three companies
🥇 1. Applied Materials – most attractive valuation profile
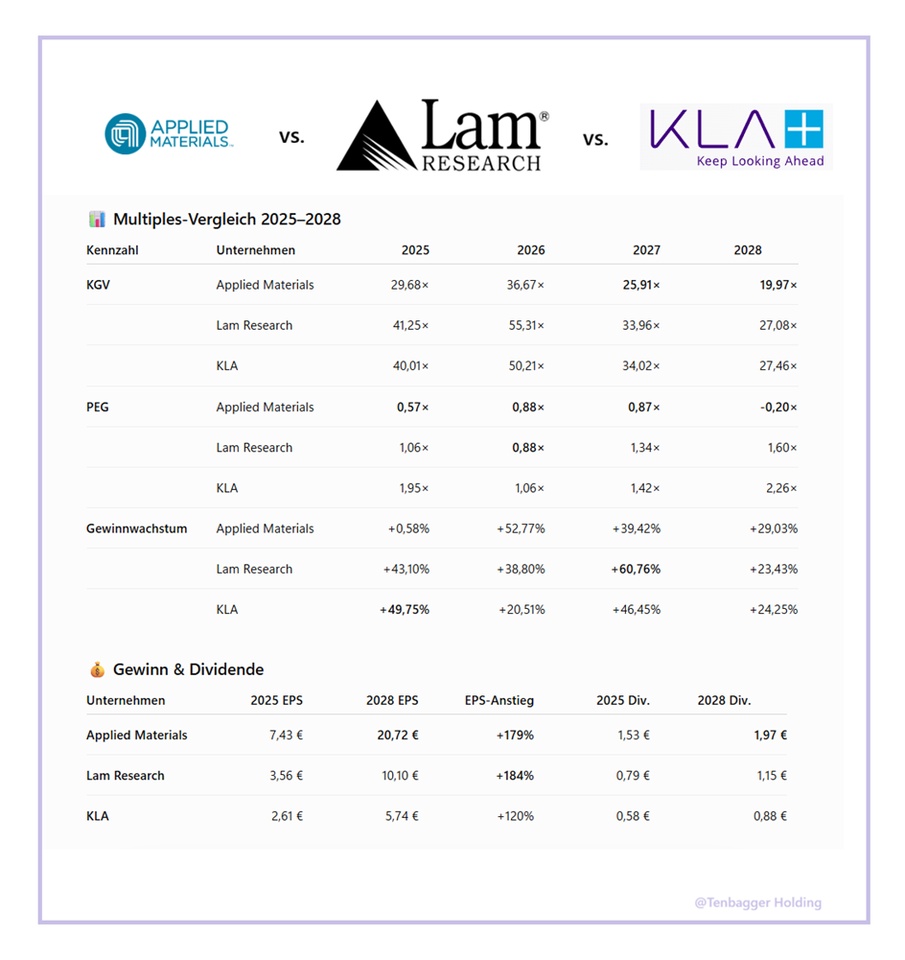
- In 2028, only 19.97× P/E
- PEG drops to 0.87× 2027
- 2028 even -0.20× PEG according to your data
- EPS rises from €7.43 to €20.72
- Earnings growth remains steady in 2027/28 at 39.42% / 29.03% strong
- At the same time, it has the highest dividend of the three
➡️ For me, clearly the best balance of growth and valuation.
🥈 2. Lam Research – strongest growth, but more expensive
- Highest earnings growth in 2027: +60.76%
- EPS rises by about 184% from 2025 to 2028
- Although the P/E ratio falls from 55.31× to 27.08×
- the PEG ratio will rise to 1.60×
➡️ Extremely strong operational performance, but the market continues to demand a high valuation for it.
🥉 3. KLA – an outstanding company, but the most expensive in terms of PEG
- Strong earnings growth
- Still +46.45%
- P/E ratio falls to 27.46×
- However, the PEG rises to 2.26× in 2028
➡️ Very interesting from a qualitative perspective, but currently the most challenging valuation based on the multiples.
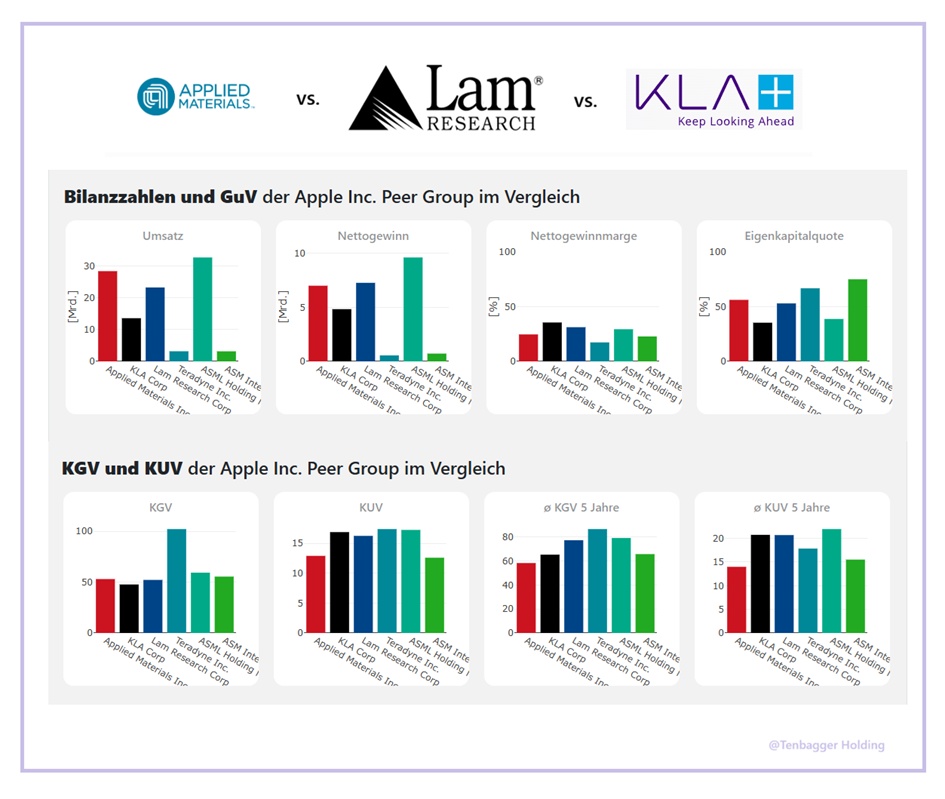
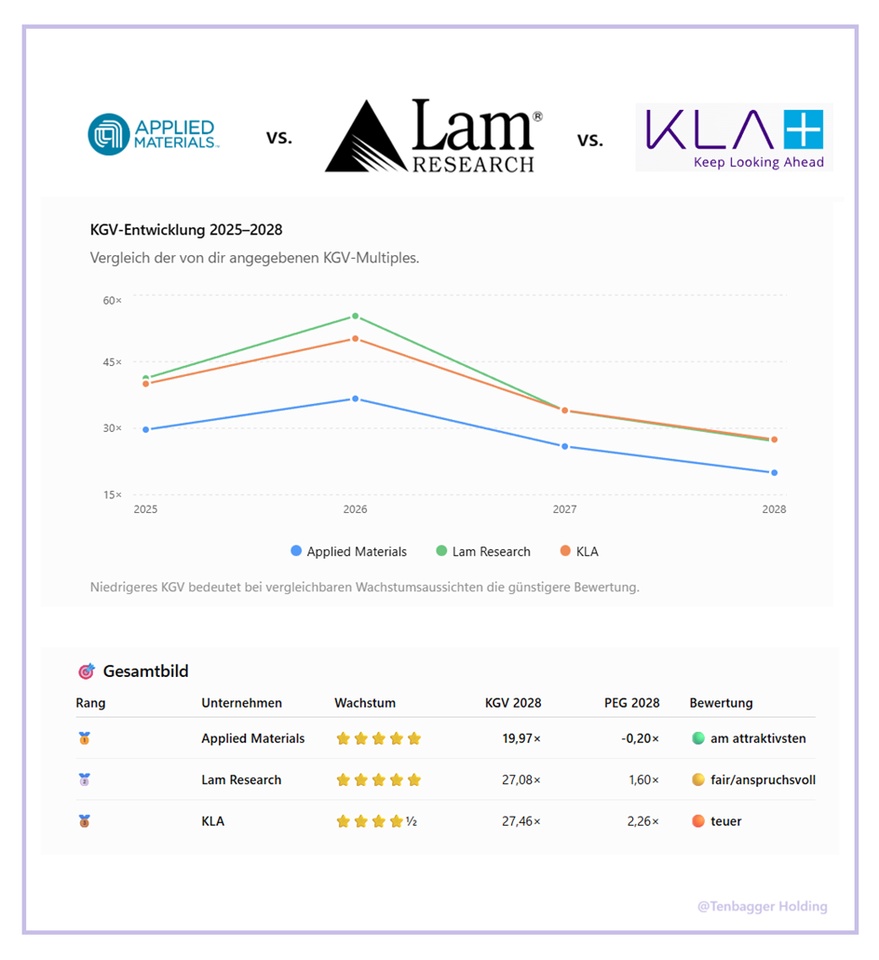
My conclusion: If I consider the multiples and earnings forecasts provided by onVista , Applied Materials is currently the clear favorite. Lam Research has the most impressive growth, but this growth is more heavily factored into the stock price and multiples. KLA appears to be the most expensive in terms of its P/E-to-growth ratio.
Note: Applied Materials’ negative PEG for 2028 is striking and should be cross-checked against the original MarketScreener table before making an investment decision.


