Hello my dears,
through the dear @7Trader after my post yesterday.
I was made aware of some important details about T1 (formerly Freyr).
Thank you for this, that's what makes our strong community.
It is very important to me to make you aware of this now.
I will also delete the company presentation next week.
🧭 Were investors "deceived"?
Legally: No. Emotionally/communicatively: Many feel that way.
Why?
- Freyr has communicated very ambitious timetables for years.
- The reality lags massively behind these plans.
- The delays were often communicated late.
- Capital requirements are increasing, although earlier statements suggested otherwise.
This is classic start-up riskbut many investors had perceived Freyr as "almost ready" - and then reality caught up with them.
📉 Why is T1 now "not recommended"?
A T1 rating usually means: high quality, clear visibility, good predictability.
Freyr currently fulfills the opposite:
- No reliable schedules
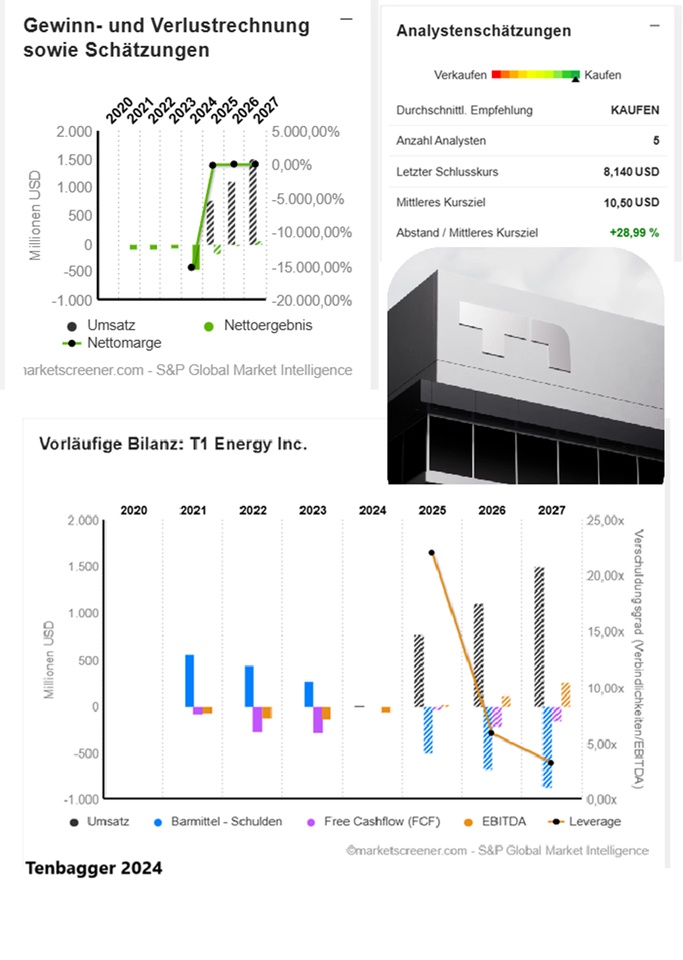
- High cash burn
- Uncertain financing
- Delayed technology validation
- Political dependency (subsidies)
- Loss of confidence in the market
This makes Freyr is not a top pickbut a highly speculative turnaround case.
💡 What does this mean for investors?
There are three realistic scenarios:
1) Turnaround succeeds
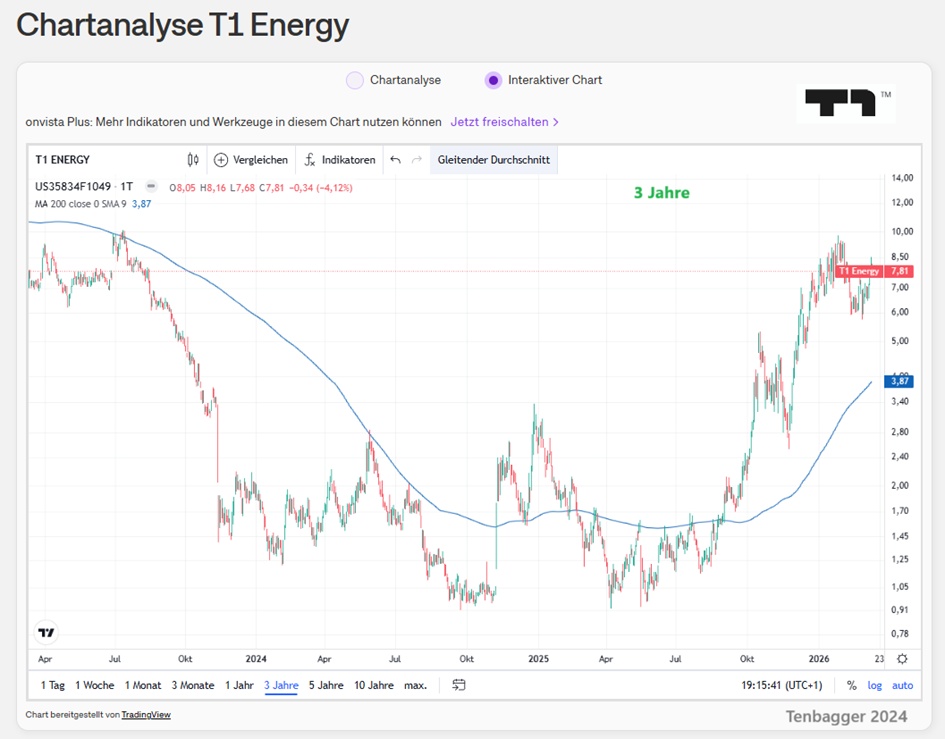
CQP is running, customers are coming, financing is in place. → Share price could multiply.
2) Slow dilution
New capital increases, delays, uncertainty. → Share price remains low or continues to fall.
3) Worst case: project abandonment / insolvency
If financing fails. → Total loss possible.
The market is currently pricing a high risk - and that is rational.