

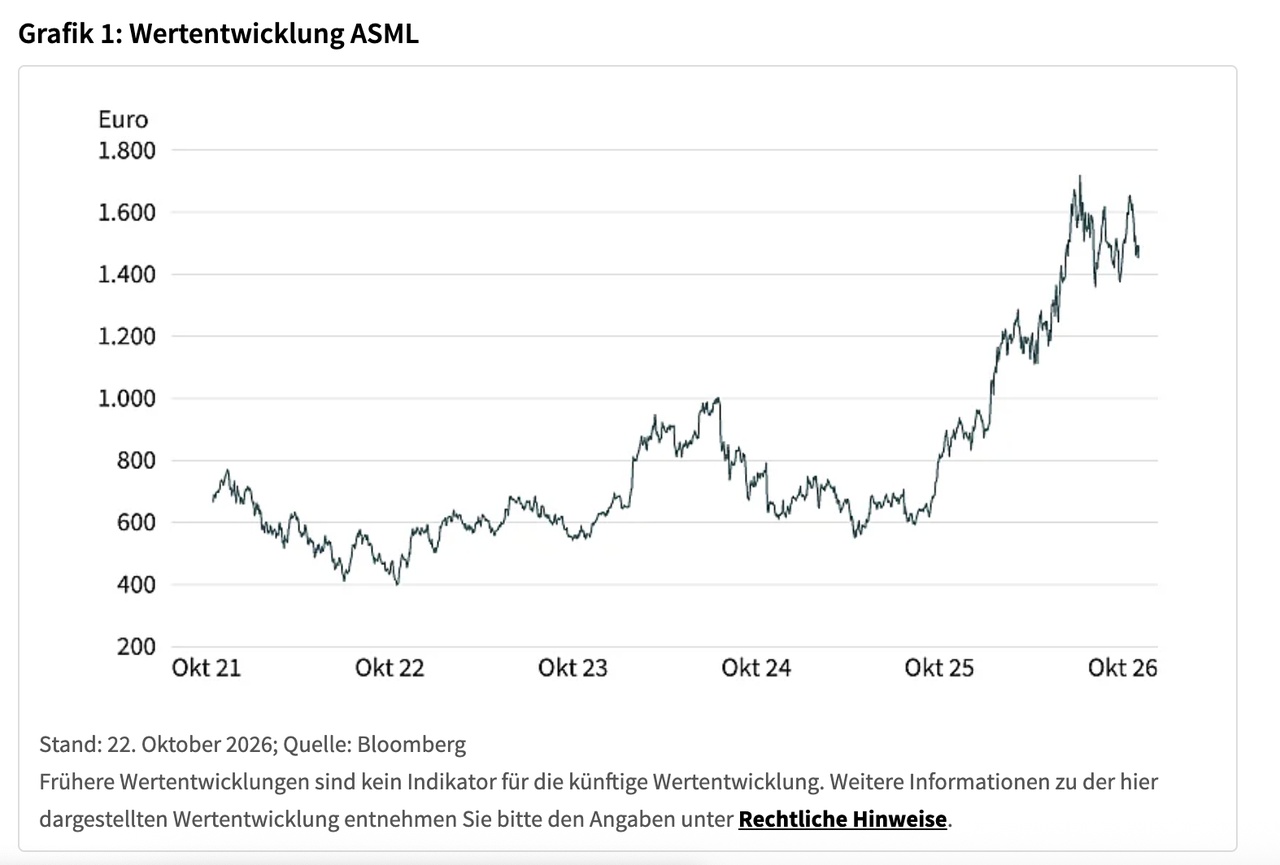
Whether it’s an AI application or the 2-nm processor in the iPhone 18: A critical production step requires a lithography system from $ASML (-1,62%) . With an estimated market share of around 90%, the Dutch company is effectively a monopoly and thus one of the more quiet beneficiaries of AI, the cloud, and digitalization.
The Q3 figures show just how well things are going right now. Revenue is up 55% from the previous year, operating profit has more than doubled, and the full-year forecast has been raised to €44 to 45 billion. Due to high demand, ASML also expects dynamic growth for 2027 and 2028, and the well-filled order book ensures a high degree of predictability.
However, the story isn’t entirely without its challenges;
about 70% of revenue comes from the ten largest customers, such as$2330 ,$SMSN (-4,8%) or $INTC (-1,84%) . China’s share of product revenue has fallen from about 41% to roughly 33%, and export restrictions have become increasingly stringent. Further tightening remains a real risk, as does the typical cyclicality of the semiconductor industry.
The question remains: Is the valuation premium for such a market position justified, or has much of it already been priced in?
👉 The complete analysis, including the business model, risks, and outlook, is available in the verlinkten Artikel.
This article is part of an advertising partnership with Société Générale


