Coupang ($CPNG (+2,09%)) is not a classic e-commerce tradebut a platform-based infrastructure group with a focus on logistics dominance, monetization per customer and operational economies of scale.
E-commerce is only the entry point. The real value comes from last-mile control, advertising, memberships & services.
Speed instead of price, infrastructure instead of marketplace, cash flow instead of growth at any price.
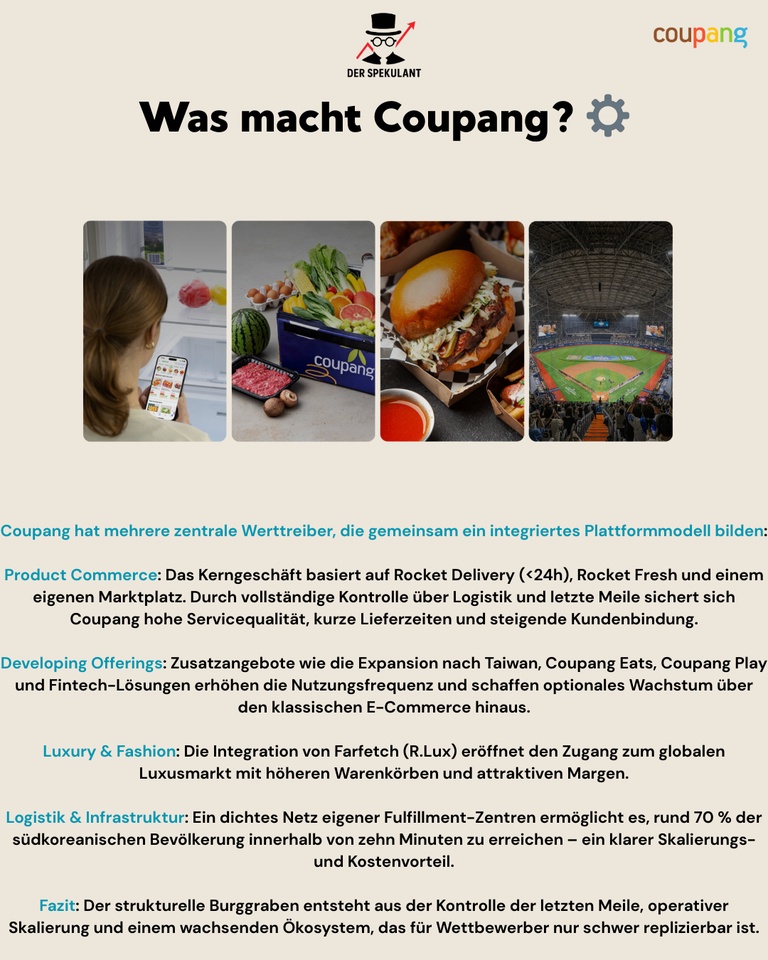
⚙️ What does Coupang do?
➡️ Product Commerce (Rocket Delivery): Own end-to-end model with Rocket Delivery (<24h), Rocket Fresh & controlled marketplace. Coupang owns the logistics - not just the app.
→ Service quality + data + repurchase rates.
➡️ Logistics & infrastructure: Dense network of own fulfillment centers. ~70 % of the Korean population can be reached within 10 minutes.
→ Structural moat by controlling the last mile.
➡️ Developing Offerings: Expansion into Taiwan, Coupang Eats, Coupang Play & Fintech.
Increase frequency of use and platform stickiness.
→ optional growth beyond traditional commerce.
➡️ Advertising: Performance-based advertising directly in the purchasing process. High purchase intent, growing retailer base, very attractive margins.
→ Highly scalable margins-leverage.
➡️ Luxury & Fashion (Farfetch / R.Lux): Integration of Farfetch opens up the global luxury market. Higher shopping baskets, better take rates, higher-margin segment.
→ Strategic upside-option.
👉 Coupang = integrated logistics & commerce platform.
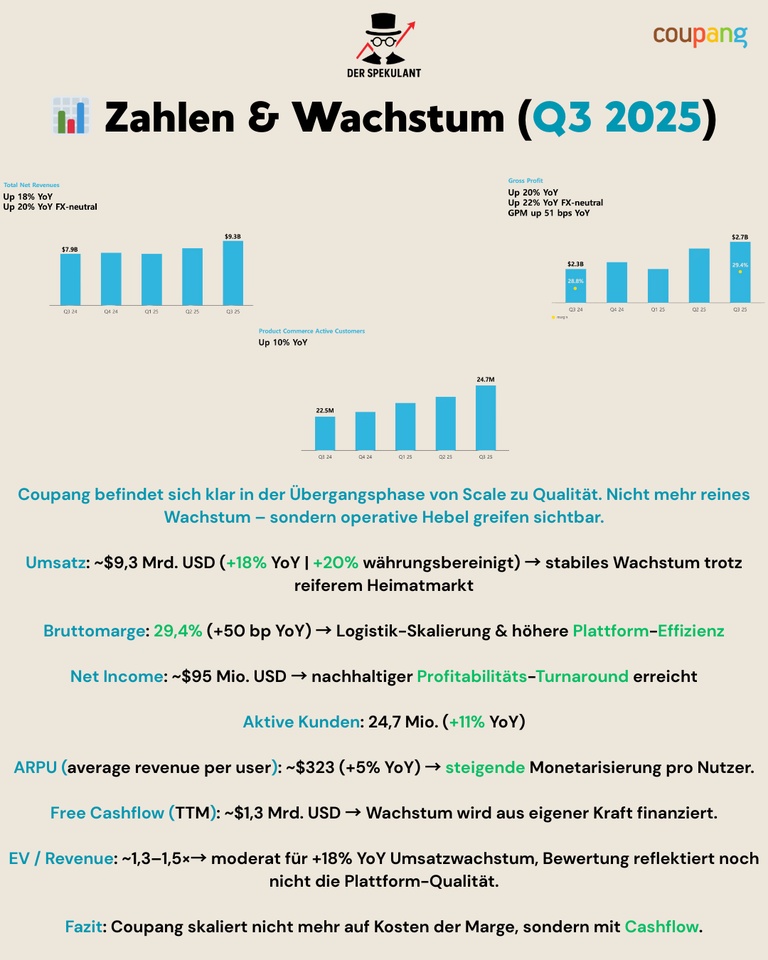
📊 Figures & growth (Q3 2025)
📈 Turnover: ~9.3 billion USD (+18 % YoY | +20 % FX-neutral)
→ Stable growth despite more mature domestic market.
📊 Gross profit: ~USD 2.7 billion (+20 % YoY)
📈 Gross margin: 29.4 (+50 bp YoY)
→ Logistics scaling & higher platform efficiency.
📈 Net Income: ~ 95 million USD
→ Sustainable profitability turnaround achieved.
👥 Active customers: 24.7 million (+11 % YoY)
💳 ARPU: ~323 USD (+5% YoY)
→ Increasing monetization per user.
💰 Free cash flow (TTM): ~USD 1.3 billion positive
→ Growth is financed from own resources.
🟢 The opportunities
🟢 Internationalization (Taiwan): Growing faster than Korea at a comparable stage of maturity. High transferability of the logistics model.
🟢 Advertising as a margin lever: High-margin platform business with direct buying intent. Scales disproportionately to GMV.
🟢 WOW-Membership & customer loyalty: High repurchase rates, increasing shopping baskets, low churn. Improves ARPU, predictability & lifetime value.
🟢 AI & automation: Intelligent fulfillment systems continuously reduce costs per parcel. Scaling is increasingly driving up margins.
🟢 Farfetch option: Luxury segment with structurally higher margins.
Long-term upside beyond classic e-commerce.
🔴 The risks
⚠️ Margin-sensitive business model: E-commerce remains structurally cost-intensive.
Wage, energy and transportation costs can dampen progress.
⚠️ High capital intensity: Logistics is moat - but CapEx-intensive.
Requires disciplined capital allocation.
⚠️ Competitive pressure: Intense competition in Korea (Naver, local players).
Internationally strong incumbents.
⚠️ Execution risk with expansion: Scaling of logistics, service & costs simultaneously challenging.
⚠️ Farfetch integration: Luxury is high-margin but cyclical.
Integration requires operational discipline.
💡 Conclusion & outlook
Coupang is not a short-term e-commerce trade,
but a structural infrastructure bet on digital consumption in Asia.
🔹 Short term:
Sensitive to margin trends, CapEx cycles & growth sentiment.
🔹 Long-term:
Platform with a deep logistics moat, increasing monetization per customer
and growing profitability from its own resources.
🎯 Investment case:
Leverage on Logistics dominance + ARPU growth + Advertising + Internationalization
→ structurally growing, operationally scalable, attractive long-term ROI.
💬 Community question:
👉 Asian platform champion with underestimated cash flow potential
or
👉 too capital intensive for a real core position?
I am curious about your assessment 👇