
Dear Qiners,
After I recently asked about the safest possible investment option for my parents, I received many interesting suggestions from you all. Thank you to everyone!
Based on the discussion, I’ve drawn the following conclusions for myself:
1. The options presented are already among the safest available on the market (if you don’t count deposit insurance per account).
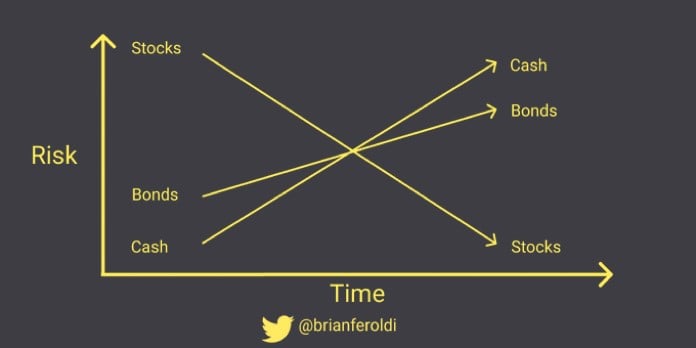
2. There is no such thing as absolute safety. The ETFs presented are primarily subject to inflation risk. Security varies over time; what’s safe in the short term isn’t necessarily safe in the long term. A relatively safe way to hold or invest money must diversify risk across different time horizons. However, a lot depends on an individual’s risk tolerance—and their life expectancy.
3. Ultimately, I recommended the following allocation to my parents, which is now being implemented step by step:
100k each in a money market account
400k $CSH (-0%)
400k $XG01 (+0,05%)
spread across 4 accounts (IngDiba, Zero, DKB, SNeo). At the moment, there are a total of 8 accounts, some of which are with rather risky local banks.
4. This allocation is intended to keep the money as safe, simple, and interest-bearing as possible for the time being, until they are psychologically ready to climb up the short-term risk ladder (and thus move down the long-term one). If you’re not ready, just stick with the (ultra-)short-term bonds. When you are ready, there will likely be higher-yielding bond ETFs and low-volatility dividend stock ETFs available.
Incidentally, this is also the kind of advice I’d give to anyone who’s supposed to provide financial guidance to their parents or other relatives. Tailor the portfolio’s risk to your psychological comfort level and level of knowledge! Anything else will just get you into deep trouble!
Yours, Epi