... and yet I am still invested in $LNTH (-0,45%) invested.
Why?
Because Lantheus was never a classic "just buy and leave for 20 years" share for me. But also not a blunt gamble.
For a long time now, I have tended to hold a mixture of: Core position + tactical management.
Meaning: I always hold a core position, but actively exploit extreme exaggerations.
When the share was completely dismantled and fell towards $50 in some cases, I added to my position rather than selling in panic. Many people wrote it off completely at the time.
Now - after the strong recovery towards $100 - I have recently sold a "tender" 5 shares and reallocated the capital to AST SpaceMobile 🛰️ because, in my opinion $ASTS (+2,46%) after the setback following the last Q1 earnings, I felt it had the better risk/reward ratio in the short term.
I (now) usually reinvest the profits from such movements directly instead of constantly injecting new capital. This works much better for me psychologically than always throwing in fresh, "hard-earned money".
I am currently still holding 70 shares $LNTH (-0,45%) and am keeping a very close eye on developments.
What I find exciting about Lantheus:
- Sales growth from approx. USD 339 million (2020) to over USD 1.5 billion (2025)
- EPS growth from USD 0.47 to USD 6.08
- Free cash flow now at around USD 367 million
- Gross margin now over 61%
- Profitable growth instead of pure hope
- Market leader in radiopharma / cancer diagnostics
- Current P/E ratio despite everything only around 15
And to be honest, I find the figures behind it quite impressive:
Sales have grown from ~USD 340m to over USD 1.5bn in just a few years. At the same time, the company has become massively more profitable and is now generating hundreds of millions of USD in free cash flow.
If you look at the fundamental data, the company appears $LNTH (-0,45%) is in a much stronger position today than it was a few years ago.
BUT: You should definitely not ignore the risks. ☝🏻😌
The stock remains brutally volatile and is heavily dependent on issues such as:
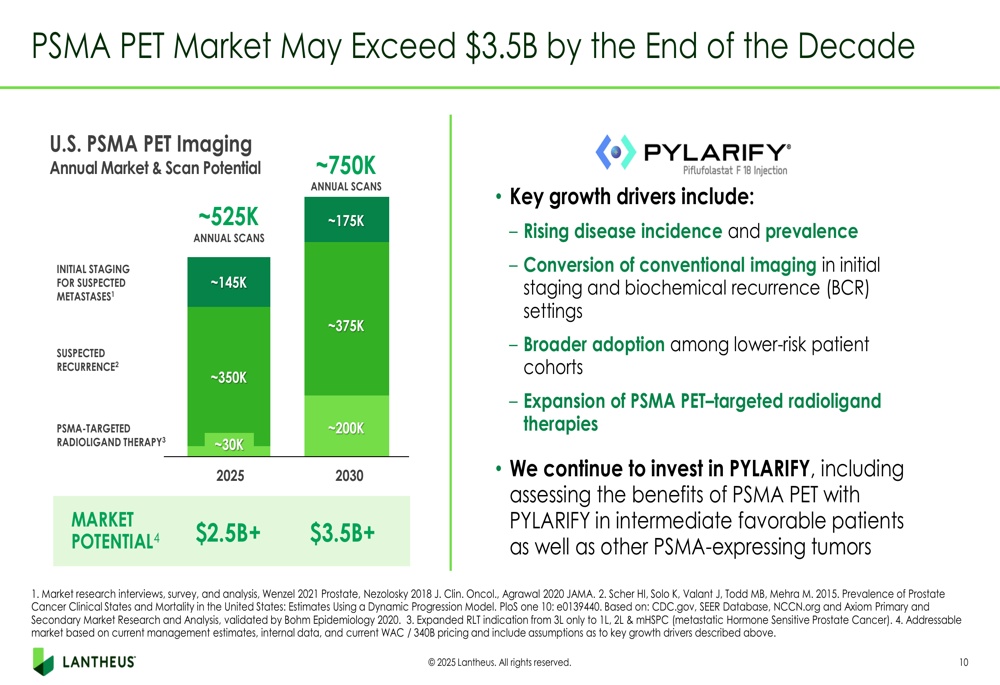
- Pylarify growth: Pylarify is currently Lantheus' most important product. If growth there is weaker than expected, the share will react extremely sensitively.
- Competition: The radiopharma market is becoming increasingly exciting and therefore more competitive. New providers or better solutions could put margins under pressure in the long term.
- Price development / reimbursement systems: In the healthcare sector in particular, many products are heavily dependent on reimbursements and pricing structures. Changes here can quickly impact sales and profitability.
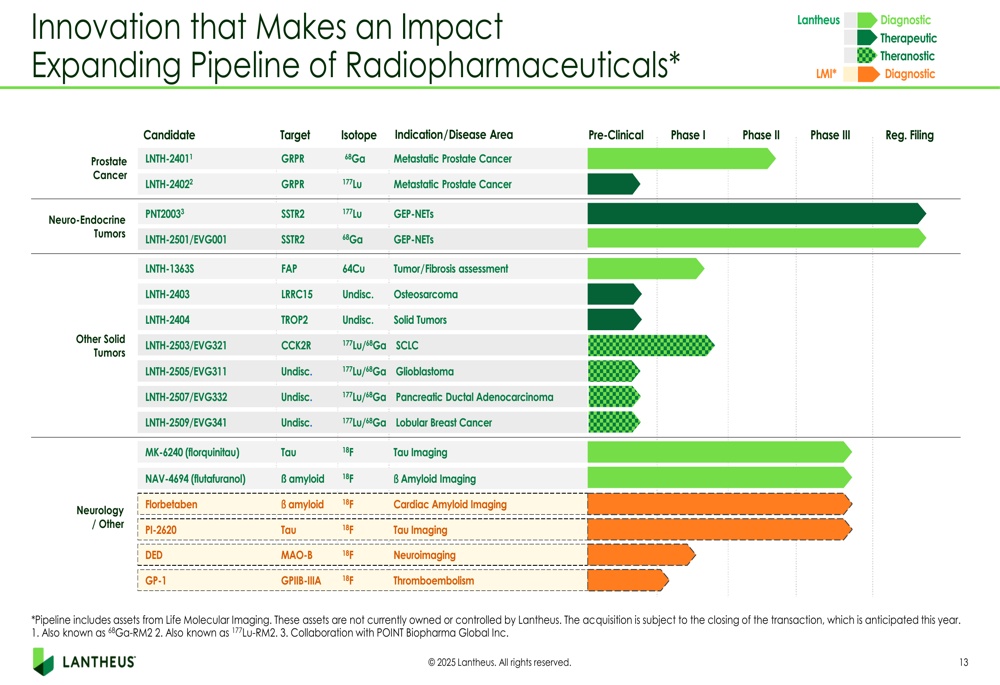
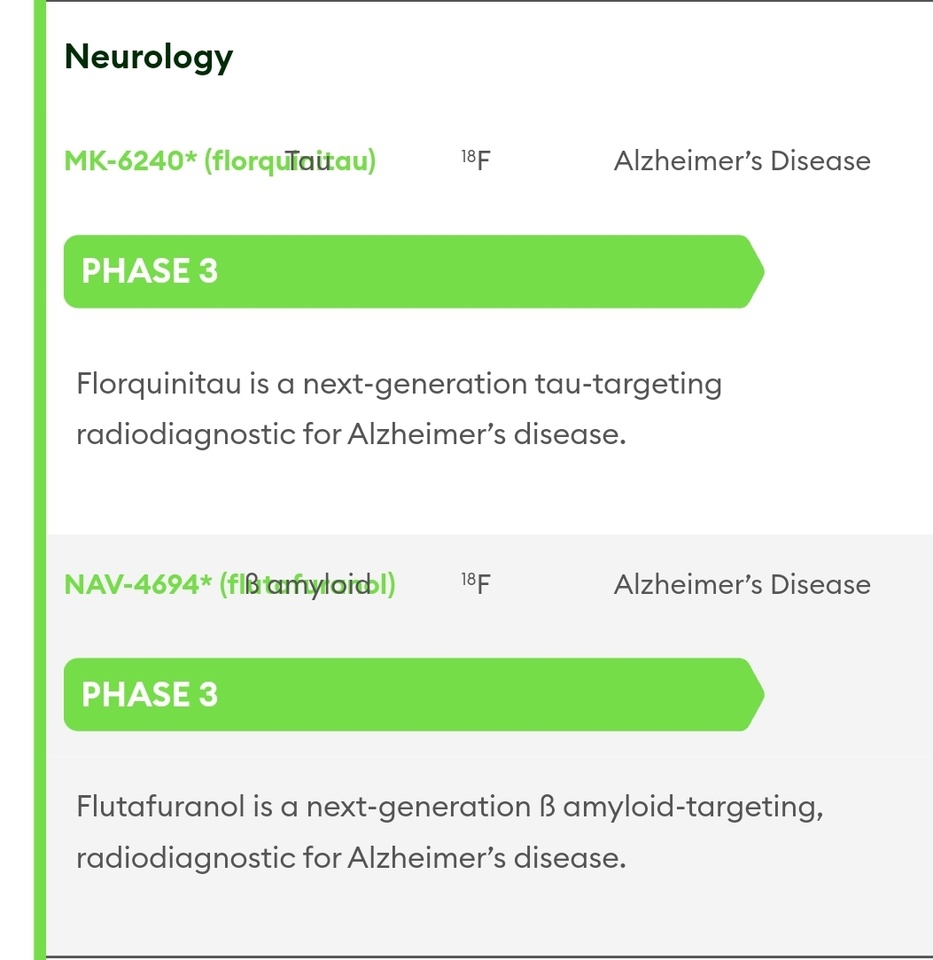
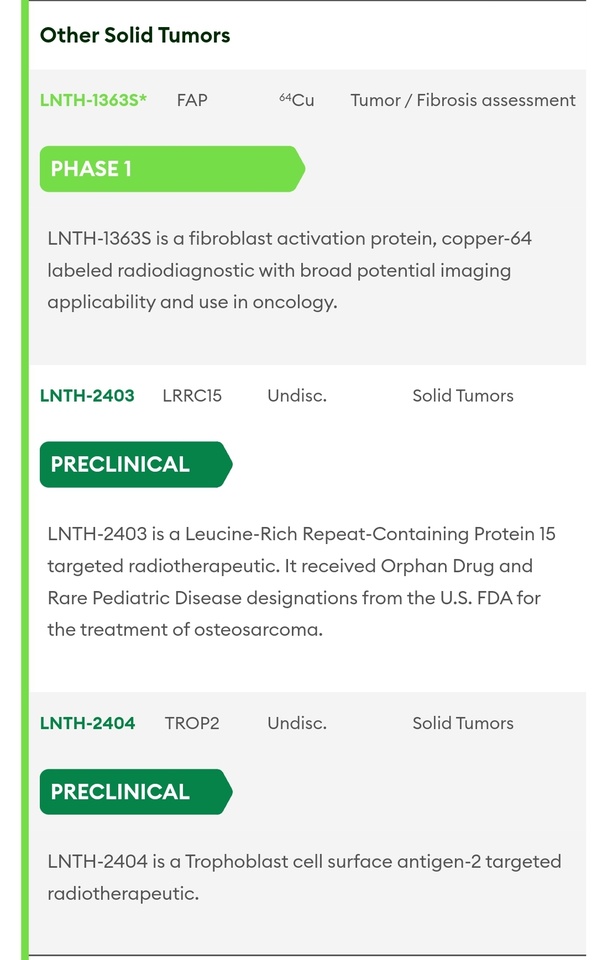
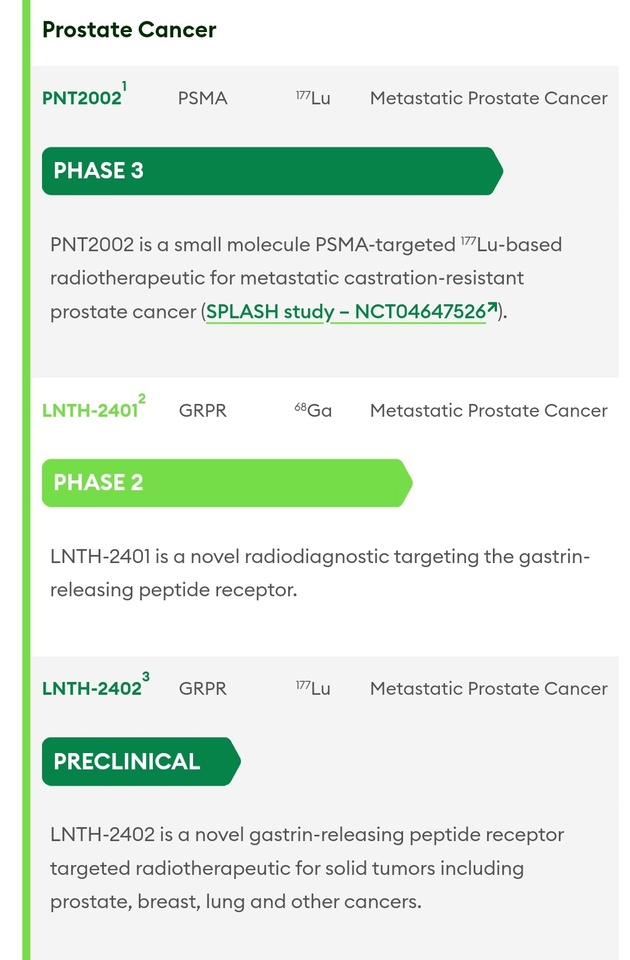
- Approvals / FDA: As with many healthcare and radiopharma companies, regulatory decisions can have a massive impact on valuation. At the same time, however, we are currently seeing how important positive developments can be here: For example, Lantheus recently received FDA approval for PYLARIFY TruVu a new formulation which, according to the company, could improve production, availability and margins. There has also been progress with other pipeline products such as PNT2003.
- Market psychology / volatility: LNTH shows extremely strong exaggerations to the upside and downside. The stock is definitely not for the faint-hearted.
This is precisely why I would $LNTH (-0,45%) personally neither as a blind buy & hold for decades nor as a pure trading stock.
Rather as an exciting long-term quality growth stock that can be actively managed.
I would be interested:
How do you deal with such shares? 🤔
Hold them completely?
Take partial profits?
Or strictly buy & hold no matter what happens 😅