Summary
Coinbase stock is facing its most important decision of the year. Following the Q3 earnings report, the stock price fell 12.7% in one week to $143.54 and briefly hit $136.89, its lowest level since February 2024. This puts the crypto giant trading nearly 68% below its all-time high and right at a support zone that has cushioned every sell-off since April 2025. Operationally, Coinbase is sending mixed signals: Revenue plummeted 35% to $1.22 billion, while adjusted earnings significantly beat expectations and prediction markets are growing rapidly. Analysts are lowering their price targets one after another, but on average they still see the stock at around $217. On the weekly chart, the stock is moving sideways in neutral territory—the trigger levels of $140 on the downside and $230 on the upside will determine the next major move.
Key Points
Closing price on Oct. 30, 2026: $143.54, weekly decline of 12.7%, intraday low of $136.89 Q3 2026: Revenue: $1.216 billion (−35%), adjusted EPS: $0.28 vs. expected −$0.16; Prediction Markets already project over $200 million in annualized revenue; Analysts: Average price target of $216.57, but price target cuts from Goldman, Barclays, and Mizuho; Technical analysis: Support at $140–150, upside trigger at $230, downside target at $115
What are Coinbase’s current key metrics?
Coinbase stock is trading at $143.54 (closing price as of Oct. 30, 2026), with a market capitalization of approximately $38 billion and an average analyst price target of $216.57. You know just how harshly high-momentum stocks are being punished right now from the D-Wave Quantum Aktie — at Coinbase, the disappointment following the earnings report runs just as deep.
MetricValueDate
Price (NASDAQ: COIN)
$143.54
October 30, 2026
52-week high
$342.80
November 3, 2025
52-Week Low (intraday)
$136.89
October 30, 2026
All-Time High (intraday)
$444.65
July 18, 2025
Distance from all-time high
−67.7%
October 30, 2026
Weekly performance
−12.7%
October 30, 2026
Market capitalization
approx. 38 billion USD
October 30, 2026
Revenue Q3 2026
$1.216 billion (−35% year-over-year)
October 29, 2026
Adjusted EBITDA Q3 2026
$332.9 million
October 29, 2026
Adjusted EPS for Q3 2026
$0.28 (expected: −$0.16)
October 29, 2026
Price-to-Sales Ratio (P/S)
8.8 (7-year average: 8.3)
October 31, 2026
Cash and Cash Equivalents / Long-Term Debt
$8.60 billion / $5.95 billion
September 30, 2026
Average Analyst Price Target
$216.57 (20 Buy / 13 Hold / 3 Sell)
October 30, 2026
Dividend
None
October 30, 2026
What news is currently driving Coinbase stock?
Coinbase stock is currently being driven by the Q3 earnings report released on October 29, 2026, and a wave of price target cuts. As seen with Bloom Energy Aktie , this shows that a single week of earnings can completely turn the price trend.
Date | News | Details | Assessment
October 30, 2026
Price slide to multi-year support
Weekly decline of 12.7% to $143.54, intraday low of $136.89—the lowest level since February 2024.
Bearish
Oct. 30, 2026
Wave of price target cuts
Goldman Sachs: $244 → $210 (Buy), Mizuho: $155 → $145 (Neutral), Barclays: $149 → $120 (Underweight), Wells Fargo: $174.
Bearish
October 29, 2026
Q3 2026 Results
Revenue: $1.216 billion (−35%), transaction revenue: $590 million (−44%), adjusted EPS: $0.28 vs. an expected −$0.16. GAAP profit of $718.7 million, of which $715 million were paper gains on crypto holdings.
Neutral
October 29, 2026
Prediction Markets as a Growth Driver
Over $200 million in annualized revenue; 2026 cost forecast lowered to $4.15–4.30 billion; over $2 billion in share buybacks.
Bullish
October 29, 2026
Weak Start to the Fourth Quarter
Transaction revenue through October 25 totaled only about $165 million; Q4 subscription revenue expected to be $550–630 million.
Bearish
October 28, 2026
Bernstein and JPMorgan ahead of earnings
Bernstein lowers target price from $330 to $250 (Outperform); JPMorgan raises target price from $148 to $189 (Overweight).
Neutral
What does Coinbase do? — Who’s behind the crypto giant?
Company description
Coinbase Global Inc. (ISIN: US19260Q1076, WKN: A2QP7J) was founded in 2012 by Brian Armstrong and Fred Ehrsam in San Francisco and went public on the NASDAQ via direct listing in April 2021. The company is the largest regulated crypto exchange in the U.S., is listed on the S&P 500, and holds over $330 billion in crypto assets—12% of all global crypto assets are held on the platform.
What Coinbase really is—four business models in one:
- Trading platform: Retail and institutional crypto trading—the historical core, now under pressure due to low trading volume
- Infrastructure & Custody: 2% of all global crypto assets—Coinbase is the go-to solution for institutional investors
- Subscription & Services: Staking, USDC interest income, Coinbase One Premium — already accounting for 44% of net revenue and growing
- Base Blockchain: Coinbase’s own Ethereum Layer 2 chain for stablecoin payments, AI agents, and DeFi
Coinbase Stock Segment Breakdown 2026 — Source: Aktienfinder
Why Coinbase Can Secure Significant Market Share Now: In particular, the market share of retail investors from competitor Binance could mean a significant influx of transactions for Coinbase. Binance does not yet have a MiCA license, whereas Coinbase already obtained one in 2025.
What is MiCA—and why is it a game-changer for Coinbase?
MiCA is the most important regulatory development in the history of the European crypto industry—and Coinbase is on the winning side. Here’s a complete explanation:
What is MiCA?
MiCA stands for “Markets in Crypto-Assets Regulation”—the first comprehensive EU-wide regulation for crypto service providers. MiCA has been in effect since December 2024, and the final transition period expired on July 1, 2026. As of that date, any crypto exchange wishing to serve customers in the EU must hold a CASP (Crypto Asset Service Provider) license. A single CASP license in one EU member state entitles the holder to “passporting”—that is, to operate in all 27 EU member states. A rejection has the opposite effect: it blocks access to the entire EU single market in one fell swoop.
What does MiCA mean for investors in concrete terms?
Of the more than 1,200 crypto providers previously operating in the EU, only about 210 (17%) have received full CASP authorization so far; the rest must restrict or cease operations. For users, this means: deposits halted, no new spot orders, savings plans frozen—withdrawals remain possible, but switching to a licensed provider is mandatory.
What happened to Binance?
Binance is the most prominent loser. On June 24, 2026—shortly before the deadline—Binance voluntarily withdrew its MiCA CASP application with the Greek regulatory authority HCMC, even before a formal rejection was issued. Binance held national registrations in France, Poland, Italy, Spain, Sweden, and Lithuania—but these do not confer passporting rights under MiCA. The result: Millions of EU users in Germany, France, Poland, Italy, and Spain received emails urging them to withdraw their funds. Binance most recently had 450 million EU users and held approximately $47.5 billion in EU customer funds.
Why is Coinbase benefiting so significantly?
Coinbase has held a MiCA license through the Luxembourg regulatory authority CSSF since 2025—and uses Luxembourg as its European hub for all 27 EU member states. CEO Brian Armstrong reacted immediately: He offered new EU users a 5% transfer bonus for transfers made by July 13. The message was clear: Coinbase is ready for the millions of Binance customers who need a new licensed provider.
The comparison with Uber is apt: MiCA has effectively flipped a regulatory switch in the EU—those with a license can drive; those without must get off the road. Coinbase is driving. Binance is on the sidelines.
How large is the potential market share gain for Coinbase?
Out of 1,200 providers, approximately 210 will remain. That’s a market consolidation of over 80%. For Coinbase, this means a huge pool of EU users will have to switch—and Coinbase is one of the largest licensed providers, alongside Kraken, OKX, and Bitpanda. July 30, 2026, will reveal how much of this is reflected in the Q2 figures.
Is the Coinbase stock fundamentally undervalued?
Fundamental Analysis (as of October 31, 2026)
No, the Coinbase stock is not yet a clear bargain from a fundamental perspective—the valuation has fallen, but the core business continues to shrink. According to the stock finder’s fair value calculation, the price-to-revenue ratio of 8.8 is actually above the 7-year average of 8.3—the stock will only become a bargain once trading volume picks up again.
Revenue and Segments: In the third quarter of 2026, Coinbase generated revenue of $1.216 billion, down 35% from the previous year. Transaction revenue plummeted by 43.6% to $590 million (of which $450 million came from retail customers and $92 million from institutional clients). The subscription and services business, at $570 million—which now accounts for 49% of net revenue—is having a stabilizing effect, led by stablecoin revenue from USDC at $307 million (+5% from the previous quarter).
Margins and Costs: Coinbase has its costs under control. Operating expenses fell by 16.9% to $1.154 billion, operating income returned to positive territory at $61.7 million, and adjusted EBITDA rose 60% from the previous quarter to $332.9 million —marking the 15th consecutive quarter of profitability. By contrast, the GAAP profit of $718.7 million is inflated: $715 million of that figure consists of paper gains on crypto holdings.
Balance Sheet and Cash Flow: With $8.60 billion in cash and cash equivalents and $5.95 billion in long-term debt, the balance sheet remains solid. Operating cash flow for the first nine months, however, fell by 56% to $785.5 million—and yet over $2 billion was spent on share buybacks. Anyone who wants to see how strongly a balance sheet can carry a stock through difficult times should take a look at the Rheinmetall Aktie.
Valuation: The Stock Finder’s fair value calculation shows just how expensive Coinbase still is despite the sharp drop in its share price: The adjusted P/E ratio stands at 377 (7-year average: 123), the price-to-cash-flow ratio at 28.6 (average: 22.9), and the P/B ratio at 8.8 (average: 8.3). A traditional P/E ratio based on reported earnings is hardly meaningful due to the volatility of crypto book gains. Prediction markets are the wild card: With over $200 million in annualized revenue and 82% quarterly growth since launch, Bernstein sees this as a billion-dollar market by 2028.
Coinbase Stock Price Targets and 2026 Forecast
How is the Coinbase stock price performing?
The average analyst price target for Coinbase stock is $216.57, which is about 51% above the closing price of $143.54 —from a technical analysis perspective, however, the 2026 forecast hinges on the trigger levels of $140 and $230.
Key price levels:
52-week high: $342.80 (Nov. 3, 2025)Current price: $143.54 (closing price as of Oct. 30, 2026)First resistance level: $230Second resistance level: $280Critical support level: $140; below that, target zone of $115
Analyst price targets:
Average price target: $216.57 (20 Buy / 13 Hold / 3 Sell, as of Oct. 30, 2026)Bernstein: $250, Outperform (Oct. 28, 2026)BTIG: $240, Buy (October 30, 2026) Goldman Sachs: $210, Buy (October 30, 2026) JPMorgan: $189, Overweight (October 28, 2026)Wells Fargo: $174 (October 30, 2026) Mizuho: $145, Neutral (October 30, 2026) Barclays: $120, Underweight (October 30, 2026)
Chart Analysis: On the weekly chart, Coinbase stock is moving sideways in neutral territory. The support zone marked in yellow between $140 and $150 has absorbed every sell-off since April 2025 and is now being tested again—this zone is quite interesting. Although the downward trend line from the October 2025 high was broken in September, the breakout failed, and the stock is once again trading below the moving averages and below the red Ichimoku cloud. The RSI (35) and MACD are turning slightly downward.
Upside scenario:Only a weekly close above $230 would trigger the bullish scenario with a target of $280. After a pullback to this zone, the path toward the record high of $443 would be clear again in the long term.
Downside scenario: If the stock closes below $140 on a weekly basis, the path to the target zone around $115 is clear. From there, a counter-movement and, in the medium term, a new upward momentum would be possible.
Conclusion: Is Coinbase stock still worth it?
My assessment: Wait until the trigger levels are reached
My conclusion on Coinbase stock: Wait and watch, focusing on the marked trigger levels. On the weekly chart, the stock is currently trading sideways in neutral territory—even though the current support zone between $140 and $150 is certainly interesting. Only a weekly close above $230 would make the picture clearly bullish again; conversely, a weekly close below $140 opens the door toward $115. Fundamentally, Coinbase remains a crypto giant with a strong balance sheet, declining costs, and an exciting new growth driver in prediction markets—but as long as trading volume shrinks, there’s no catalyst for the stock price. Anyone who has seen how the Palantir Aktie suddenly skyrocketed after months of sideways movement knows why patience pays off at such price levels.
✅ Opportunities
⚠️ Risks
- Support at $140–$150 has held since April 2025—potential for a double bottom
- Prediction Markets with over $200 million in annualized revenue and 82% quarterly growth
- 2026 cost forecast lowered; adjusted EBITDA up 60% from the previous quarter
- Strong balance sheet with $8.60 billion in cash and cash equivalents
- Over $2 billion in share buybacks are supporting the stock price
- Average analyst price target: $216.57—about 51% upside potential
- Weekly close below $140 paves the way toward $115
- Transaction volume down 44%, weak start to the fourth quarter
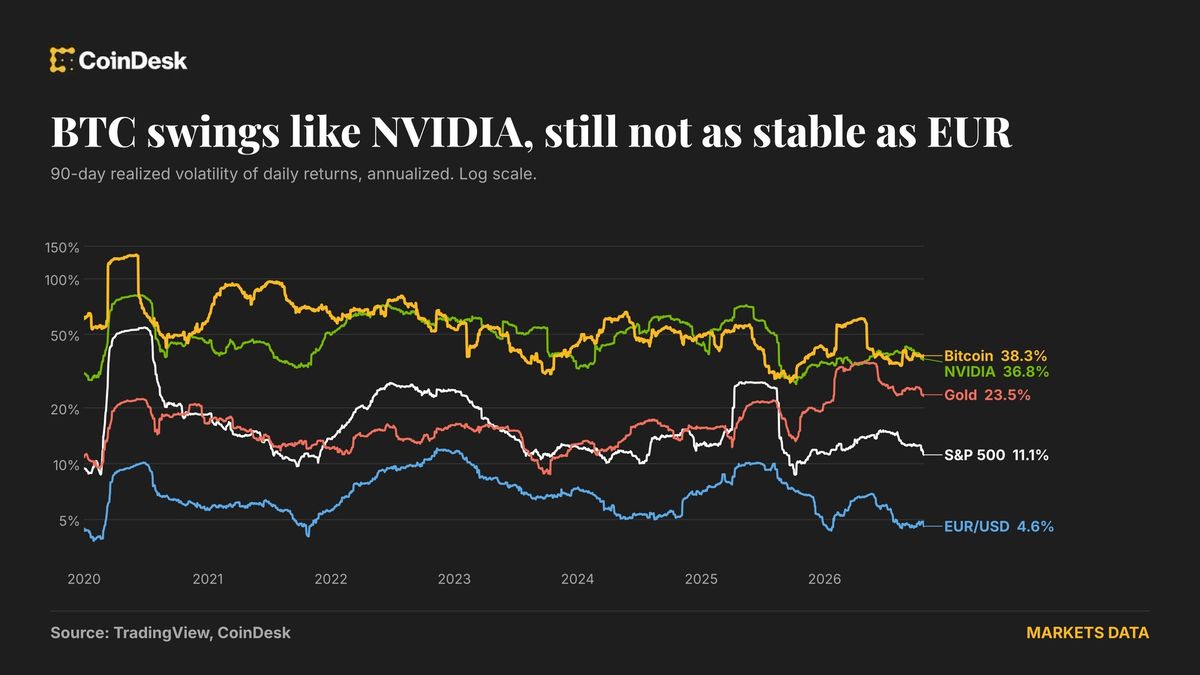
- Bitcoin is about 36% below its all-time high – crypto sentiment is down
- Wave of price target cuts; Barclays now at just $120
- Adjusted P/E ratio of 377 and P/S ratio above the 7-year average – valuation justified only by a recovery in trading volume
- GAAP earnings heavily dependent on crypto paper gains
FAQ: Frequently Asked Questions About Coinbase Stock
Is Coinbase stock a buy in 2026?
Currently, Coinbase stock is more of a hold position that requires monitoring: At $143.54 (Oct. 30, 2026), it is at a strong support level between $140 and $150, but on the weekly chart, it is trading sideways in neutral territory. A clear buy signal will only emerge if the weekly close exceeds $230.
Why did Coinbase stock fall?
Coinbase stock fell 12.7% in the week ending October 30, 2026, because third-quarter revenue plummeted 35% to $1.216 billion, transaction revenue dropped 44%, and several firms, including Goldman Sachs, Barclays, and Mizuho lowered their price targets.
What is the price target for Coinbase stock?
The average analyst price target is $216.57 (as of October 30, 2026). The range extends from $120 (Barclays) to $250 (Bernstein); Goldman Sachs forecasts $210, and JPMorgan forecasts $189.
What is the forecast for Coinbase stock in 2026?
From a technical analysis perspective, two levels are key: A weekly close above $230 opens the door to a target of $280, while a weekly close below $140 points toward a target range around $115. Until then, the outlook is neutral.
When will Coinbase release its next earnings report?
The fourth-quarter 2026 earnings are expected to be released in mid-February 2027; the exact date has not yet been confirmed. For the fourth quarter, Coinbase expects subscription and services revenue of $550 million to $630 million.
How much does Coinbase pay in dividends?
Coinbase does not pay a dividend. Instead, the company returns capital through share buybacks—over $2 billion through the end of the third quarter of 2026, with an additional $2 billion or so approved.
How does Coinbase make money?
Coinbase generates revenue primarily from trading fees (Q3 2026 transaction revenue: $590 million) as well as from subscriptions and services ($570 million), including stablecoin revenue from USDC ($307 million), staking rewards ($86 million), interest income, and the Coinbase One subscription. A new addition is Prediction Markets, with over $200 million in annualized revenue.
What does the $140 mark mean for Coinbase stock?
The range between $140 and $150 has been the key support level since April 2025. If it holds on a weekly closing basis, a double bottom is possible; if the stock falls below that level, the target range around $115 comes into focus.
What’s your take on the $COIN (-4,31%) right now?