

Vediamo che succede fra 3 mesi.

Hoegh Autoliners
Azione
Azione
ISIN: NO0011082075
Ticker: HAUTO
NO0011082075
HAUTO
Price
Discussione su HAUTO
Messaggi
116


1G·
Monthly Review 09/2026
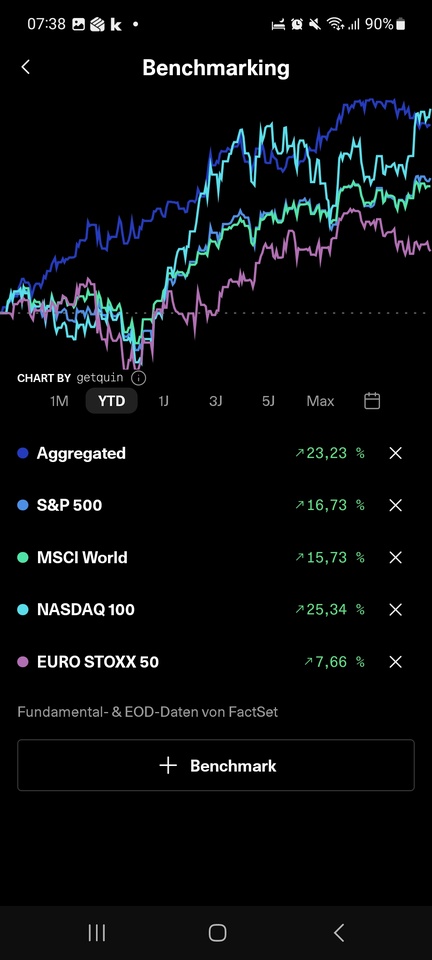
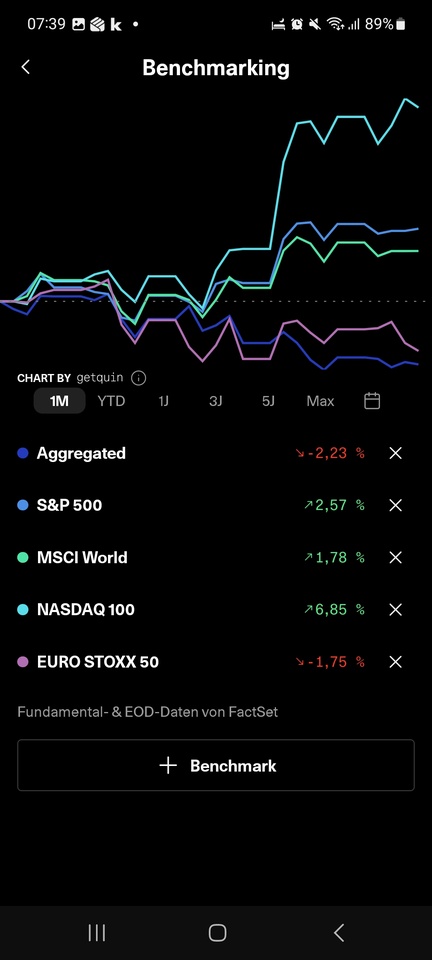
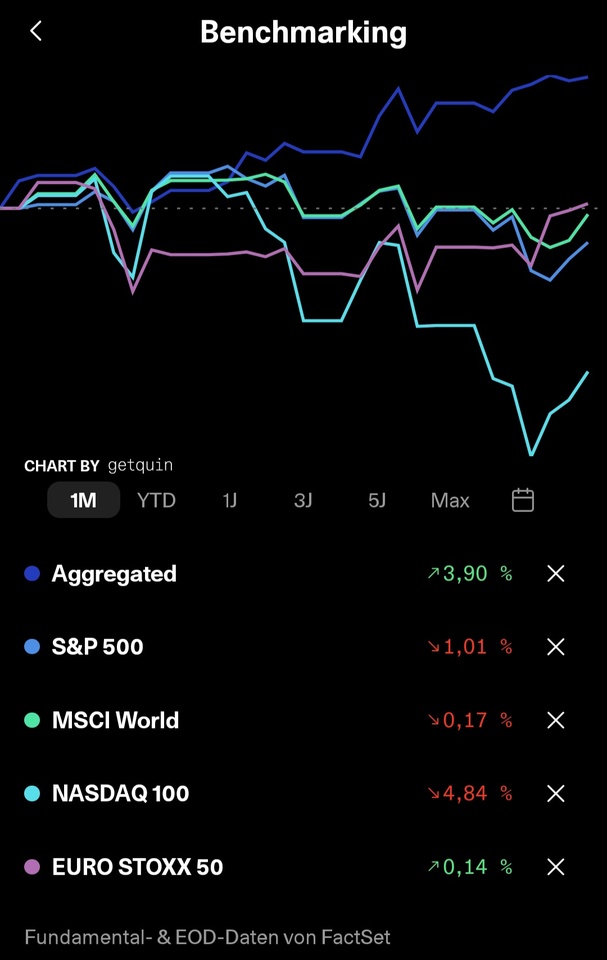
Another quarter is behind us, and after this past 🦘 month, I find it amusing to note that this year, it seems the last month of every quarter always ends up in the red...
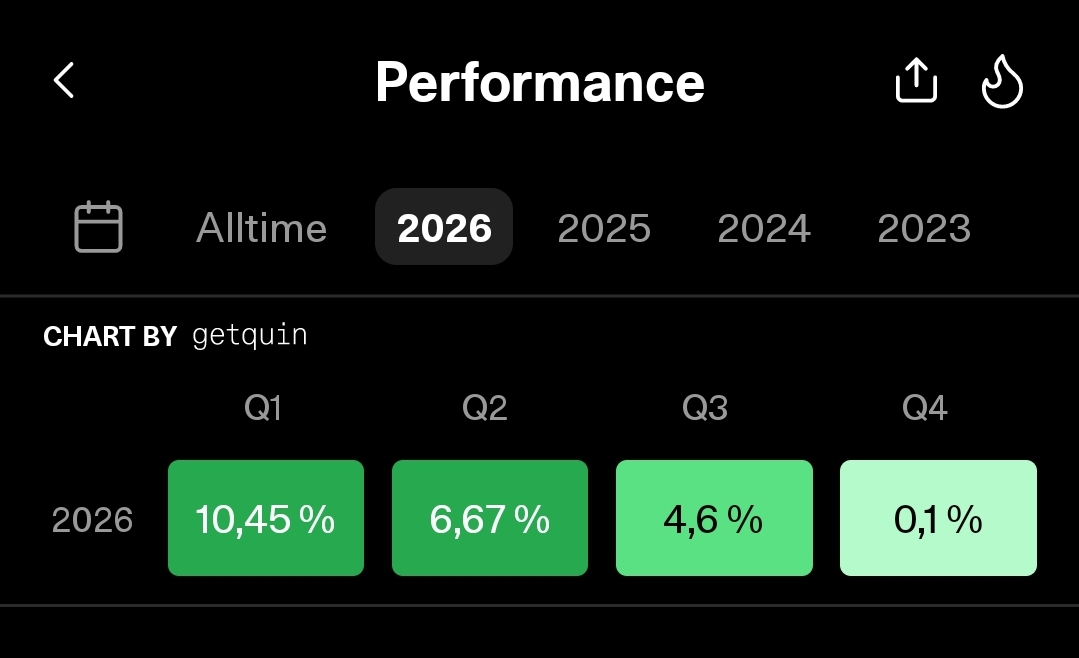
But it doesn’t really bother me, because when viewed on a quarterly basis, everything still fits well into the overall picture...
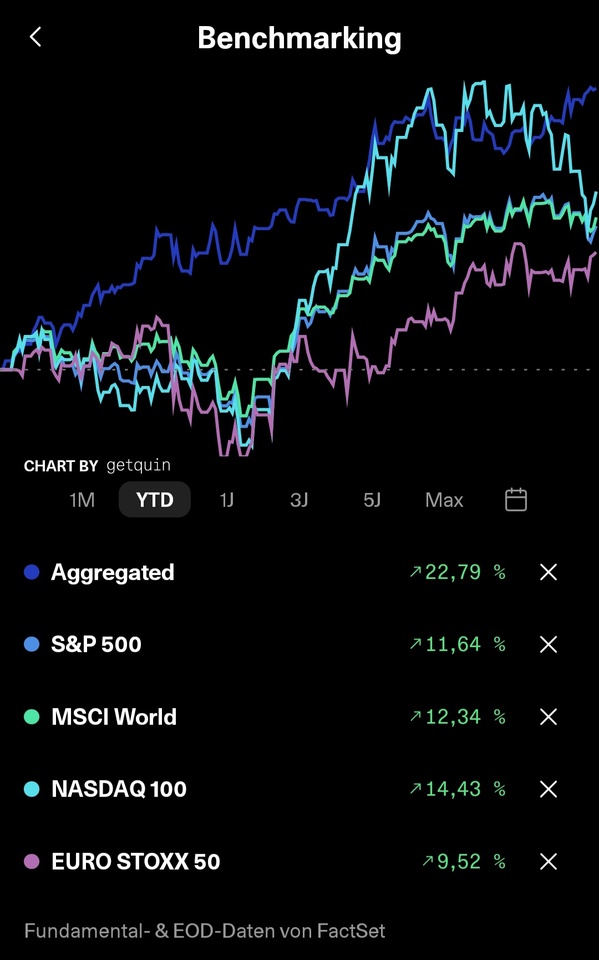
...and from an annual perspective, things aren’t looking too bad so far either...
...for a relatively conservative, dividend-focused portfolio that isn’t heavily weighted toward tech, so everything’s still within reason...
...and from a long-term perspective, everything continues to fit into the overall strategy.
Sure, things can always be better, faster, higher, and further, but considering the resources and the overall conditions, everything is perfectly within the target range 🫠
》DIVIDENDS《
Despite the pesky taxes, this month still yielded €215.63 in net dividends, corresponding to a YOC of 6.28 (target range between 6–7%).
》TOP 3《
$HAUTO (+0,77%) + 9.89% (+147.82%)
$ASWM (+1,41%) +4.31% (+24.81%)
$VAR (-0,98%) +0.86% (+70.93%)
》FLOP 3《
$AII (+2,83%) -19.10% (+19.85%)
$3750 (-0,6%) -16.85% (+87.16%)
$DTE (+1,9%) -8.15% (-4.61%)
》 NEW ADDITIONS 《
43.95 x $WINC (+0,79%)
24 x $AII (+2,83%)
10 x $MUX (+1,96%)
1 x $MUV2 (+2,11%)
》DISPOSALS《
----
》CONCLUSION《
Everything remains the same, except that the final certification (DATEV LuG) is still pending this month, and with the change of the month, we’ll also have to handle the move into our new apartment.
With that in mind, things continue to be exciting, so I wish you and your portfolios all the best 👍🏻
+ 1
3232
1 Commento
I think the performance is really impressive. It's awesome. Congratulations. 🙂
•
99
•
1Mes·
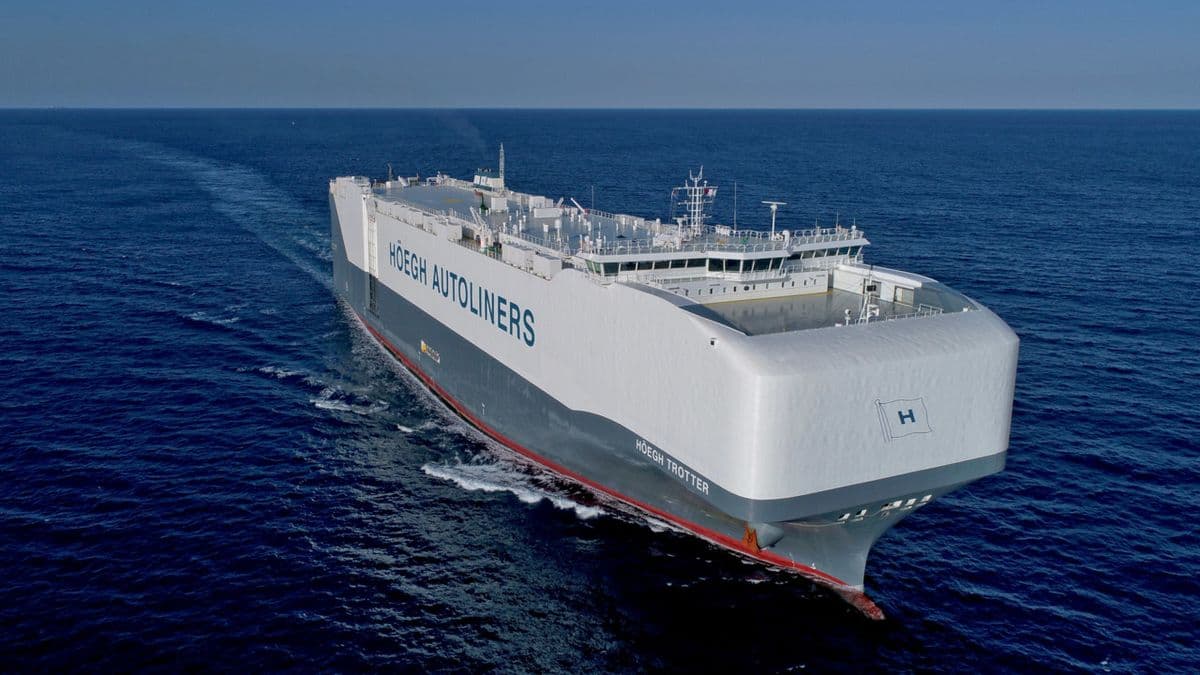
HÖEGH AUTOLINERS +100% AND I DON'T SEE AN END IN SIGHT 🚀
Sometimes it’s not the well-known tech giants that make the most exciting stories in your portfolio.
For me, it’s currently a company that many probably don’t even have on their radar: Höegh Autoliners.
My position is now up over 100%—and that’s despite a dividend yield that makes many people do a double-take at first.
But that’s exactly where it gets interesting:
Höegh doesn’t just transport cars. The company is at the center of a structural shift in the global automotive trade.
China is exporting more and more vehicles worldwide. In the first half of 2026, Chinese vehicle exports were already 66% higher than the previous year. At the same time, available RoRo capacity is becoming scarcer, and Höegh reports that its fleet is operating at full capacity. (Höegh Autoliners)
At first glance, the Q2 figures were weaker:
- $376 million in revenue
- $122 million in EBITDA
- $86 million net income
However, the reason is significant: high fuel costs and geopolitical upheavals in the Middle East have weighed on earnings. The fuel effect alone cost approximately $22 million in the quarter. (Investing.com)
And that’s exactly why I find the current situation exciting.
Because if these one-time costs subside, while exports to China continue to grow and market capacity remains tight, the company could $HAUTO (+0,77%) continue to offer an attractive combination of cash flow, dividends, and growth.
The company itself expects the BAF/fuel surcharge to return to normal over the course of Q3. At the same time, charter rates for the industry have risen significantly. (thedcn.com.au)
For me, Höegh is therefore not a stock I hold solely for the dividend.
I see this as a bet on a long-term trend:
More Chinese vehicles + more global vehicle transport + tight shipping capacity = an interesting starting point for a specialized player.
Of course, shipping remains a cyclical industry. The dividend isn’t guaranteed, and high payouts can fluctuate.
But that’s exactly what makes the stock interesting to me.
+100% price gain realized.
Dividends collected.
And yet the position remains in my portfolio.
Now I’m curious:
Which of you are also invested in Höegh Autoliners—and do you hold the stock for the dividend or for the long-term story?
#HöeghAutoliners
#HAUTO
#Dividendenaktien
#Dividende
#Aktien
#Investieren
#Börse
#China
#Autowerte
www.hoeghautoliners.comHoegh Autoliners
2222
8 Commenti
1Mes
I've been with Höegh for 1.5 years now and am up 105%. I invest a small monthly savings plan as well as my Trade Republic round-up. Dividends also keep coming back. Top company...
•
55
•
1Mes·
After the sale is before the purchase
$HAUTO (+0,77%) It's out…
What should I put in now? 🤔
Hoegh actually was a pretty good fit for my portfolio (logistics sector)
So now, maybe $MAERSK A (+3,21%) or $HLAG (+1,08%) add it?
So many questions…
GaLiGrü
66
4 Commenti•
22
•
1Mes·
Hoegh Autoliners Reports Financial Results and Significantly Reduces Its Dividend
Hoegh Autoliners $HAUTO (+0,77%) released its latest quarterly results today and announced the amount of its next cash dividend. Investors aren’t happy about this for now, and the stock is down significantly in early trading.
Although revenue and EPS exceeded expectations, Hoegh is struggling with its operating performance. High fuel costs and the impact of the Iran conflict are putting significant pressure on margins.
What will upset many even more is that Hoegh has drastically cut its dividend to just $0.0839. The company hopes this will allow it to keep more cash on its balance sheet.
The dividend cut at Hoegh Autoliners isn’t just a cosmetic move; rather, it changes the earnings logic quite significantly. If this continues, it would fundamentally alter the investment thesis for many.
What do you think? A one-time blip in the dividend. Sell? Or wait and see if improvement is in sight? The outlook for the next quarter is relatively subdued; results are expected to remain roughly flat.
1616
23 Commenti
I posted 1 minute before you 😬 but deleted it; here’s my opinion:
I see this more as a temporary strain, but not as a guaranteed one-time slip-up.
The business remains profitable, and demand for Ro-Ro transport remains strong, according to the company. The main causes were high fuel costs, rerouting due to the Middle East conflict, and a delay in passing these costs on to customers.
Over the course of the third quarter, cost recovery is expected to take full effect again, and cash conversion should normalize. However, Höegh initially expects Q3 EBITDA to be roughly on par with the weak second quarter. A quick return to the previously high dividends is therefore by no means certain.
My conclusion: no fundamental collapse, likely temporary in part—but the dividend remains highly volatile and dependent on free cash flow. Q3 and Q4 will be decisive.
Only when cash flow and dividends rise significantly again can we speak of a genuine one-time blip.
•
99
•
1Mes·
De-risk my portfolio
$HAUTO (+0,77%) I have a 2100 shares position in HOEGH and think about selling it completely at 200 NOK because it has grown to 13% of my portfolio. I want to reinvest 10.000 euro in $WINC (+0,79%) and the rest in $LDGL (+1%) to have stable dividend growth. Is there a flaw in my thinking or should I keep this cyclical stock but a winner so far?
44
6 Commenti1Mes
Dividends and Growth: You Can Have One Without Sacrificing the Other
••
2Mes·
Monthly Review 07/2026
Another month has passed, and it’s time once again to take a quick look into the engine room...
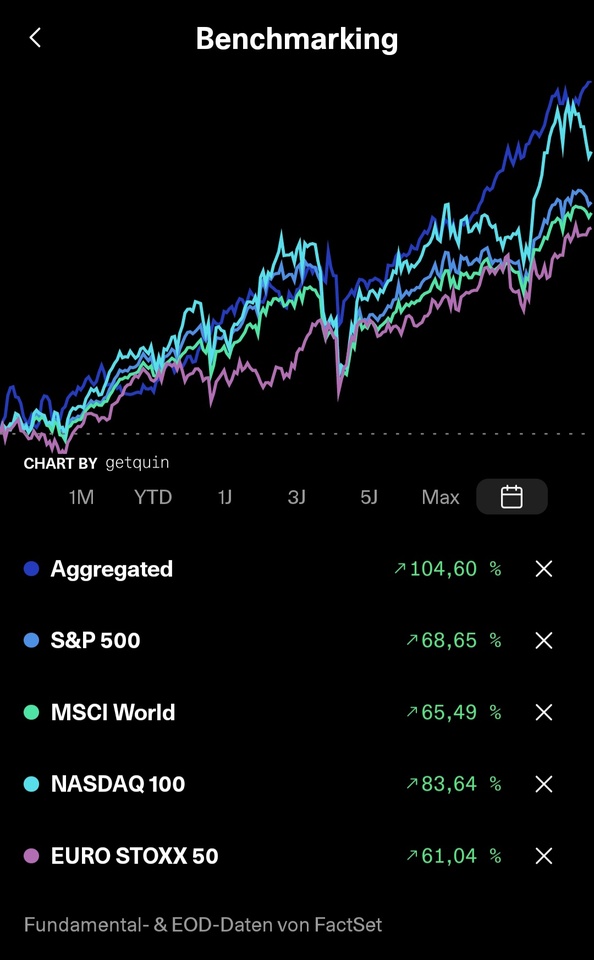
...actually, not much has changed in the big picture, except that after 38 months of consistent performance, the 40k mark has been broken, and so the final sprint of the first half has now begun...
...it’s not a high-flyer portfolio, but so far it’s been a solid growth story, and as the saying goes, every little bit helps...
...which is why YTD hasn’t changed much either...
...nor has it since the very beginning...
...the structure, however, is a different story, and so there were a few changes to the portfolio this month...
》New Additions《
$WINC (+0,79%) 244.01x
$AII (+2,83%) 101x
》Exits《
$EVD (+2,7%) 25x
》Top 3《
$HAUTO (+0,77%) +24.42% (+122.67%)
$VAR (-0,98%) +19.82% (+60.72%)
$DTE (+1,9%) +10.61% (-1.53%)
》Flop 3《
$3750 (-0,6%) -10.58% (+128.32%)
$ASWM (+1,41%) -9.86% (+17.84%)
$YYYY (+0,46%) -7.01% (-4.80%)
》Dividends《
This month, there were €252.24 in net dividends, representing a 12.24% increase year-over-year.
》CONCLUSION《
Everything’s business as usual, so we can relax and prepare for next Friday’s upcoming DATEV certification 👍🏻
I wish everyone continued success, and may dividends and growth be on our side 🫡

3Mes·
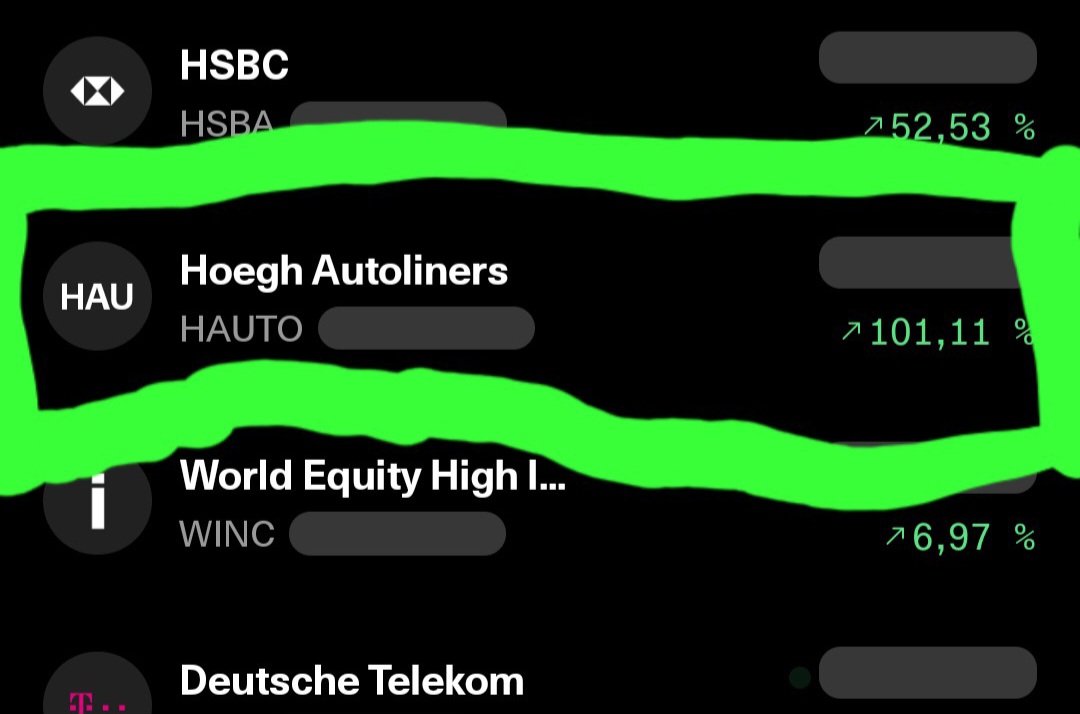
100%
...besides $BATS (-0,05%) and $3750 (-0,6%) the next value has now also -> $HAUTO (+0,77%) the 100% mark 🫠


4Mes·
Höegh Autoliners Q1 2026
Finanzen Q1 2026
- EBITDA: 145 Mio. USD, stabil gegenüber Vorquartal trotz Zusatzkosten durch Hormuz‑Krise .
- Nettoergebnis: 103 Mio. USD .
- Dividendenzahlung: 94 Mio. USD im Quartal (16. Quartal in Folge) .
- Cash & Liquidität: ~500 Mio. USD am Quartalsende .
- Operativer Cashflow: 144 Mio. USD .
Markt & Nachfrage
- Chinesische Autoexporte explodieren:
- Gesamt +57 % YoY
- EV/Hybrid‑Exporte +80–90 % YoY .
- Globaler Absatz von Leichtfahrzeugen: –5 % YoY, aber China kompensiert das durch massive Exporte .
- Starke Nachfrage nach High & Heavy (Baumaschinen): +31 % YoY aus Asien/China .
Kapazität & Flotte
- 8 von 12 Aurora‑Neubauten bereits im Einsatz .
- Chartermarkt extrem eng: nur 2–3 Schiffe bis Sommer verfügbar, Preise steigen weiter .
- Orderbook der Branche: von 42 % auf 20 % gefallen – neue Kapazität wird vollständig absorbiert .
- Alternde Legacy‑Flotte → steigende Wahrscheinlichkeit für Scrapping in den kommenden Jahren .
Vertragslage
- Überbuchung der 80‑%‑Vertragsabdeckung für 2026; großer Teil 2027 bereits gesichert .
- 160 Mio. USD neue Verträge im Quartal .
- Spotmarkt nur 6 % des Volumens, hauptsächlich High & Heavy
Treibstoffkosten & BAF‑Mechanismus
- Hormuz‑Krise verursacht massiven Anstieg der Bunkerkosten; voller Effekt erst in Q2 sichtbar .
- BAF (Fuel Surcharge) kompensiert ~95 % der Kosten – aber mit 5–6 Monaten Verzögerung .
Ausblick Q2 2026
- Q2 stark belastet durch:
- +20 Mio. USD Treibstoffkosten
- –10 Mio. USD Nahost‑Störung .
- Erwartetes EBITDA: leicht unter oder auf Niveau von Q1 (bereinigt) .
- Keine Rückkehr in den Persischen Golf in naher Zukunft geplant .
Zyklus & Marktposition
- Markt wird klar von chinesischem Exportboom getragen; absorbiert alle Neubauten und hält Raten hoch .
- Keine Anzeichen für fallende Raten im aktuellen Umfeld
Quelle seekingalpha.com, Zusammenfassung Copilot
1717
5Mes·
Logistik Aktien
Als geneigter Logistiker überlege ich, diesen Bereich in meinem Portfolio weiter auszubauen.
Aktuell hab ich :
$KCC (+3,72%)
$DHL (+2,58%)
$MPCC (+1,02%) und eine sehr kleine position $HAUTO (+0,77%)
Mit allen Positionen bin ich deutlich im Plus.
Aus Beruflicher Erfahrung sehe ich im Sektor deutliches Potenzial, mir fehlen aber etwas die Inspirationen.
Welche ist eure Top Aktie aus dem Bereich, oder wo wollt ihr Investieren?
55
7 Commenti
5Mes
•
11
•