

Murata Manufacturing, Japan's leading manufacturer of passive components, has announced that it will discontinue production of select consumer electronics and automotive MLCC products covering the GRM, GRJ, GRT, GXM, GXT, GCM, GCJ, GCG, and ZRA series, with a final order deadline of March 31, 2028. The move aims to reallocate capacity toward higher-margin, high-quality MLCCs for AI servers. The news sent Taiwanese passive component stocks higher, with Prosperity Dielectrics and Viking Tech briefly hitting their daily limit, while Yageo, Walsin Technology, and Holy Stone Enterprise also posted gains. Analysts believe that Yageo and Walsin Technology will benefit the most, as their production capacities for standard and automotive products stand to gain the most. TrendForce had previously noted that the displacement effect of high-end AI MLCCs has already spread to the automotive and consumer markets, giving Taiwanese suppliers the opportunity to win overflow orders.
Murata MFG
Price
Discussion sur 6981
Postes
4Murata Discontinues Selected MLCC Lines; Taiwanese Passive Component Manufacturers Face Order Delays
Company Presentation Before Midnight
Hello, everyone,
Given today's great performance and numbers in the tech sector,
is there a little treat for you.
The figures from OnVista and Market Screener differ once again.
So, as always, I’m eager to hear your take on our prompts (@Raketentoni / @Aktienhauptmeister )
But of course, I’m also looking forward to the community’s overall take.
After memory chips, the next bottleneck component is coming into focus in the AI supply chain: Tiny ceramic capacitors are driving lead times up to half a year—and sending stocks from Japan, Korea, and Taiwan soaring.
After processors and memory chips, the next component facing a shortage is coming into investors’ focus: so-called MLCCs, or multilayer ceramic capacitors. These tiny components—the smallest about the size of a grain of sand—are found in virtually every modern electronic device. In AI servers, they perform a critical function: they smooth out voltage spikes, filter out electrical noise, and prevent chips from becoming unstable when massive computing operations are booted up.
This is precisely what makes them the next target of the so-called “bottleneck strategy,” which investors have already successfully applied to memory chips. Goldman Sachs recently ranked MLCCs as the third-largest cost factor in the construction of AI server racks, after GPUs and memory. Analysts estimate that by 2030, the relevant MLCC market for AI servers could grow to more than four times its current volume. A single modern AI server rack can require hundreds of thousands of these components.
The consequences are noticeable: According to market observers, lead times for high-quality MLCCs now exceed 20 to 24 weeks. Because AI applications tie up enormous production capacities, the bottleneck is also affecting the automotive industry. Prices rose by as much as 25 percent at their peak.
The global MLCC market is firmly in Asian hands:
The world market leader is the Japanese corporation Murata Manufacturing with a market share of more than 35 percent. The company is considered a technological pioneer in the miniaturization of these components.
In second place is Samsung Electro-Mechanics from South Korea, which specializes in high-performance components for smartphones and AI infrastructure.
Murata Manufacturing Co., Ltd. is a Japan-based company primarily engaged in the manufacture of semi-finished products, which are intermediate components for various electronic devices. The company operates in three business segments.
The “Components” segment offers capacitors, inductors, and filters for electromagnetic interference (EMI) suppression. It is the world’s largest manufacturer of multilayer ceramic capacitors (MLCCs) and sensor solutions.
The “Devices and Modules” segment offers high-frequency modules, surface acoustic wave filters, rechargeable lithium-ion batteries, and sensors.
The “Other” segment is active in the provision of medical devices as well as in the solutions business. Murata Manufacturing develops and manufactures passive electronic components and modules for smartphones, automotive, industrial, and consumer electronics applications and supplies components to leading manufacturers such as Apple, Samsung, and Tesla.
Murata Manufacturing benefits from structural growth in electric vehicles, AI devices, and 5G smartphones, all of which have a significantly higher demand for multilayer ceramic capacitors than traditional electronic products.
The company also offers employee benefits, leases real estate, and develops and distributes products and software.
Number of employees: 75,912
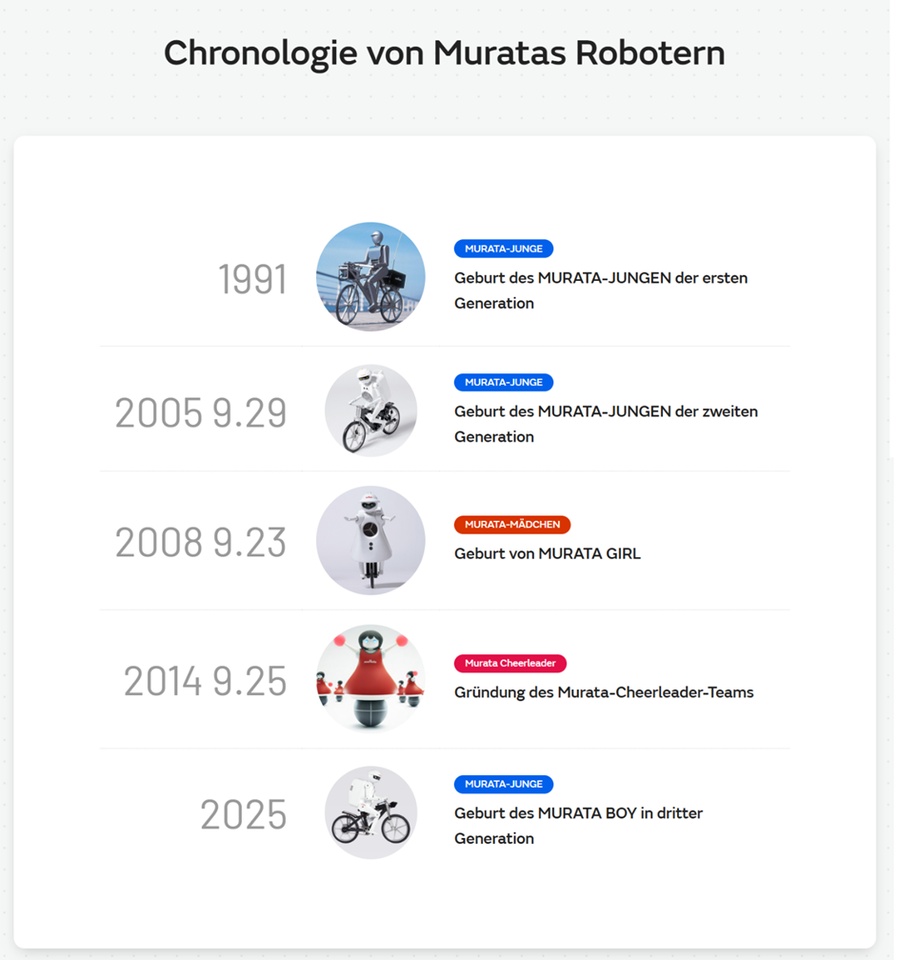
Various stunts by MURATA BOY
The robot is riding a bicycle. It maintains its balance even when it’s completely stopped!
It performs stunts such as climbing slopes and walking on balance beams.
It is able to move while maintaining balance using the handlebars, just like a cyclist.
It can cross 2-cm-wide balance beams while maintaining its balance, and even climb up and down steep slopes with ease.
With its ultrasonic sensor, it can stop before hitting obstacles.
MURATA GIRL
Thanks to her excellent sense of balance, the robot can ride a unicycle! She’s doing her best to catch up with MURATA BOY.
Earnings Release Conference First Quarter of FY2026 July 31, 2026
Murata is collaborating with Synopsys to provide simulation models using Ansys’ electromagnetic and thermal analysis tools.
The Japan-based Murata Electronics and Tribe in Singapore, an open innovation platform, have launched the KUMIHIMO Tech Camp Singapore 2026, an open innovation program that invites MedTech startups in ASEAN and India to jointly develop healthcare solutions that address the region’s most pressing medical challenges.
Murata Plans 85–90% Revenue Growth in AI and Data Center Components
Murata plant Umsatzsprung von 85-90 % bei KI- und Rechenzentrumskomponenten Von Investing.com
Revenue Breakdown by Business Segment:
2026 (JPY)
Components 1.175 billion
Devices and Modules 656 billion
Others 69.7 billion
Elimination/Corporate -70.06 billion
Geographic Revenue Breakdown:
2026 (JPY)
Greater China 865 billion
Asia and Other 376 billion
United States 255 billion
Europe 153 billion
Japan 133 billion
Americas (excl. U.S.) 49.02 billion
Juan – A Brief, Realistic Summary of Murata
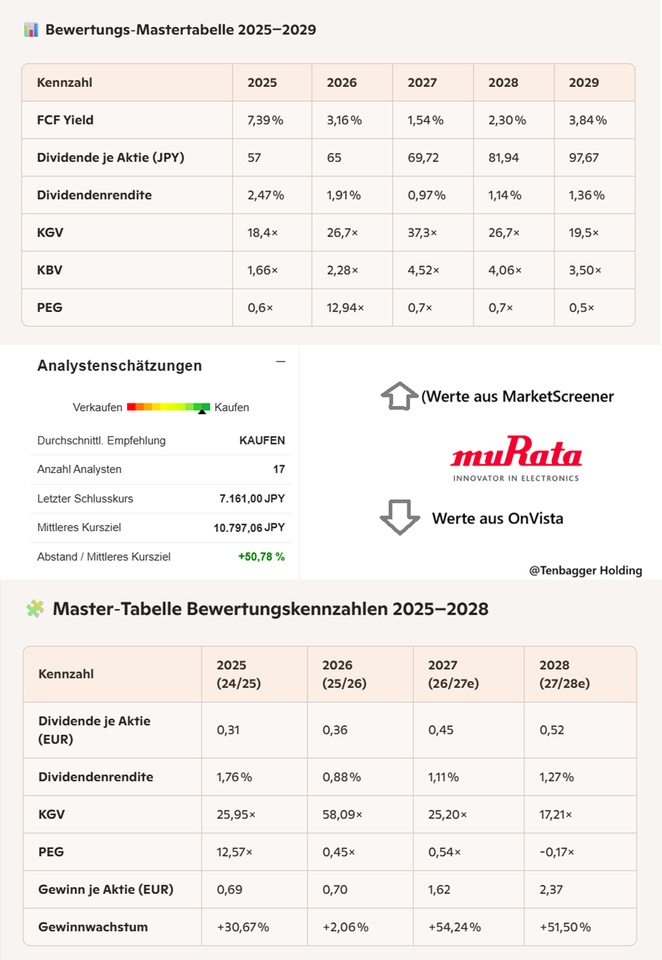
(Financial & Valuation Metrics 2025–2029 / onvista + MarketScreener)
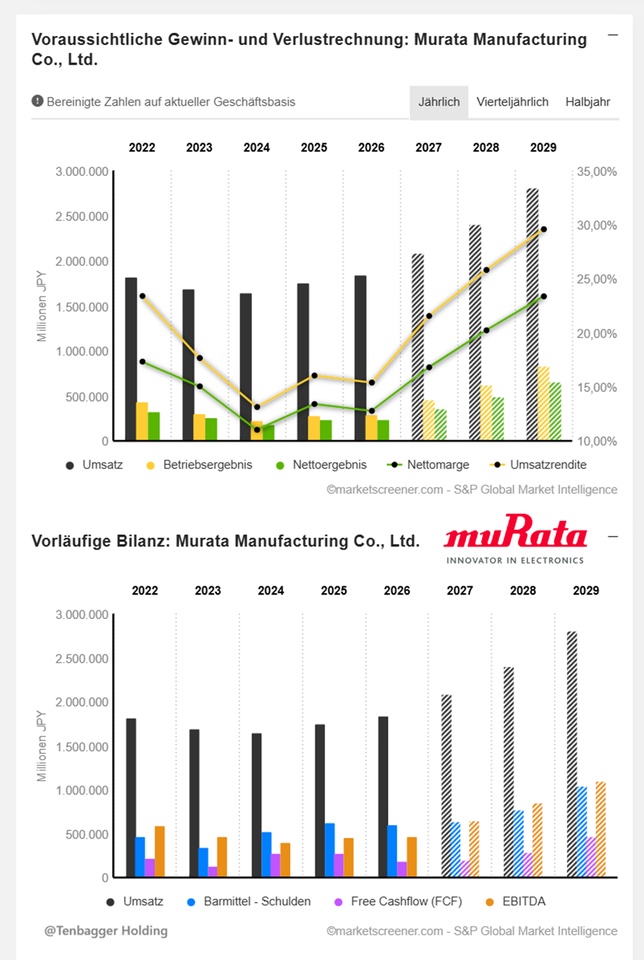
“When I take a sober look at Murata, I see a company that is clearly getting back on track financially. Revenue, EBIT, and net income will rise significantly starting in 2026, margins will climb steadily, and free cash flow will become really strong again starting in 2027. This is a classic ‘fundamentals are stabilizing, quality is returning’ scenario.
In terms of valuation, however, Murata appears to be split: The MarketScreener metrics show a moderate P/E ratio and a sharply falling PEG—in other words, a company that’s becoming more affordable as earnings pick up. Onvista, on the other hand, shows short-term fluctuations in multiples, which reflect market volatility rather than the company’s true quality.
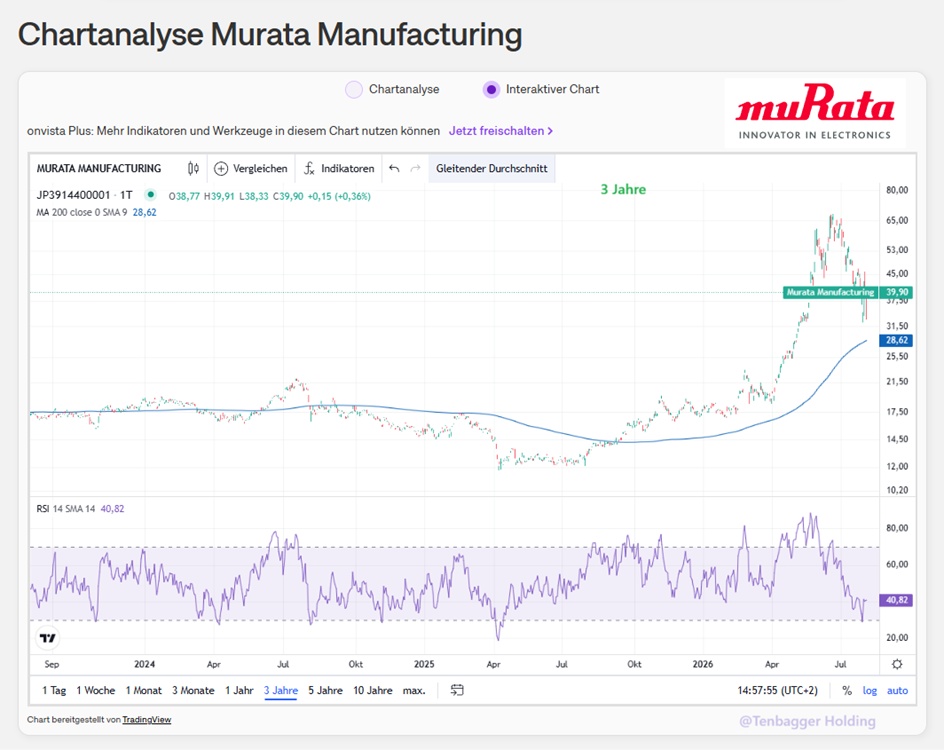
Performance:
1 week -6.03%
1 month -32.05%
6 months +124.01%
1 year +202.63%
3 years +129.24%
+ 2
Company Presentation Before Midnight
Hello, everyone,
Given today's great performance and numbers in the tech sector,
is there a little treat for you.
The figures from OnVista and Market Screener differ once again.
So, as always, I’m eager to hear your take on our prompts (@Raketentoni / @Aktienhauptmeister )
But of course, I’m also looking forward to the community’s overall take.
After memory chips, the next bottleneck component is coming into focus in the AI supply chain: Tiny ceramic capacitors are driving lead times up to half a year—and sending stocks from Japan, Korea, and Taiwan soaring.
After processors and memory chips, the next component facing a shortage is coming into investors’ focus: so-called MLCCs, or multilayer ceramic capacitors. These tiny components—the smallest about the size of a grain of sand—are found in virtually every modern electronic device. In AI servers, they perform a critical function: they smooth out voltage spikes, filter out electrical noise, and prevent chips from becoming unstable when massive computing operations are booted up.
This is precisely what makes them the next target of the so-called “bottleneck strategy,” which investors have already successfully applied to memory chips. Goldman Sachs recently ranked MLCCs as the third-largest cost factor in the construction of AI server racks, after GPUs and memory. Analysts estimate that by 2030, the relevant MLCC market for AI servers could grow to more than four times its current volume. A single modern AI server rack can require hundreds of thousands of these components.
The consequences are noticeable: According to market observers, lead times for high-quality MLCCs now exceed 20 to 24 weeks. Because AI applications tie up enormous production capacities, the bottleneck is also affecting the automotive industry. Prices rose by as much as 25 percent at their peak.
The global MLCC market is firmly in Asian hands:
The world market leader is the Japanese corporation Murata Manufacturing with a market share of more than 35 percent. The company is considered a technological pioneer in the miniaturization of these components.
In second place is Samsung Electro-Mechanics from South Korea, which specializes in high-performance components for smartphones and AI infrastructure.
Murata Manufacturing Co., Ltd. is a Japan-based company primarily engaged in the manufacture of semi-finished products, which are intermediate components for various electronic devices. The company operates in three business segments.
The “Components” segment offers capacitors, inductors, and filters for electromagnetic interference (EMI) suppression. It is the world’s largest manufacturer of multilayer ceramic capacitors (MLCCs) and sensor solutions.
The “Devices and Modules” segment offers high-frequency modules, surface acoustic wave filters, rechargeable lithium-ion batteries, and sensors.
The “Other” segment is active in the provision of medical devices as well as in the solutions business. Murata Manufacturing develops and manufactures passive electronic components and modules for smartphones, automotive, industrial, and consumer electronics applications and supplies components to leading manufacturers such as Apple, Samsung, and Tesla.
Murata Manufacturing benefits from structural growth in electric vehicles, AI devices, and 5G smartphones, all of which have a significantly higher demand for multilayer ceramic capacitors than traditional electronic products.
The company also offers employee benefits, leases real estate, and develops and distributes products and software.
Number of employees: 75,912
Various stunts by MURATA BOY
The robot is riding a bicycle. It maintains its balance even when it’s completely stopped!
It performs stunts such as climbing slopes and walking on balance beams.
It is able to move while maintaining balance using the handlebars, just like a cyclist.
It can cross 2-cm-wide balance beams while maintaining its balance, and even climb up and down steep slopes with ease.
With its ultrasonic sensor, it can stop before hitting obstacles.
MURATA GIRL
Thanks to her excellent sense of balance, the robot can ride a unicycle! She’s doing her best to catch up with MURATA BOY.
Earnings Release Conference First Quarter of FY2026 July 31, 2026
Murata is collaborating with Synopsys to provide simulation models using Ansys’ electromagnetic and thermal analysis tools.
The Japan-based Murata Electronics and Tribe in Singapore, an open innovation platform, have launched the KUMIHIMO Tech Camp Singapore 2026, an open innovation program that invites MedTech startups in ASEAN and India to jointly develop healthcare solutions that address the region’s most pressing medical challenges.
Murata Plans 85–90% Revenue Growth in AI and Data Center Components
Murata plant Umsatzsprung von 85-90 % bei KI- und Rechenzentrumskomponenten Von Investing.com
Revenue Breakdown by Business Segment:
2026 (JPY)
Components 1.175 billion
Devices and Modules 656 billion
Others 69.7 billion
Elimination/Corporate -70.06 billion
Geographic Revenue Breakdown:
2026 (JPY)
Greater China 865 billion
Asia and Other 376 billion
United States 255 billion
Europe 153 billion
Japan 133 billion
Americas (excl. U.S.) 49.02 billion
Juan – A Brief, Realistic Summary of Murata
(Financial & Valuation Metrics 2025–2029 / onvista + MarketScreener)
“When I take a sober look at Murata, I see a company that is clearly getting back on track financially. Revenue, EBIT, and net income will rise significantly starting in 2026, margins will climb steadily, and free cash flow will become really strong again starting in 2027. This is a classic ‘fundamentals are stabilizing, quality is returning’ scenario.
In terms of valuation, however, Murata appears to be split: The MarketScreener metrics show a moderate P/E ratio and a sharply falling PEG—in other words, a company that’s becoming more affordable as earnings pick up. Onvista, on the other hand, shows short-term fluctuations in multiples, which reflect market volatility rather than the company’s true quality.
Performance:
1 week -6.03%
1 month -32.05%
6 months +124.01%
1 year +202.63%
3 years +129.24%
+ 2


Satellite to a million - MSCI World Momentum Champions - Update for June 2026
🚀🚀 May (the 5th month since the launch) also delivered a great performance. 🚀🚀
It only ran out of steam a little in the final week. But in the last 30 minutes of trading it has turned upwards again. I am following the algorithm with Western DIgital ($WDC (+4,01 %)), Lumentum ($LITE (+3,71 %)), Ciena ($CIEN (+0,43 %)), Kioxia ($285A (+5,62 %)) and Bloom Energy ($BE (-4,71 %)) at the start.
The initial value was approx. 22,700 euros. Of this, 60 euros were lost due to capital gains tax on the switch to Kioxia and there was a capital inflow of 1,300 euros. This capital inflow largely flowed outside the algorithm into 1 SanDisk share ($SNDK (+10,68 %)), as SanDisk is now one of the most valuable 100 companies in the world and has shown the most explosive momentum signals in the last 12 months, but is still stuck in the MSCI World Small Cap Index. To my surprise, this will remain the case for the coming quarter, which means that I will retain my "special position" for the time being. So it started at the beginning of May with 6 shares and 23,750 euros. And May flushed almost exactly +21% into the satellite portfolio.
+5,000 euros price gain - 21% up in 30 days 🚀
Who started and who performed how?
- Bloom Energy +3%
- Western Digital +23% 🚀
- Ciena +16%
- Lumentum -5%
- Kioxia +71% 🚀🚀🚀
- SanDisk +36% 🚀🚀
The overall increase is thus very strongly fueled by Western Digital. But Kioxia was the last and thus smallest position size to be added and has overtaken all other stocks with 71%. Ciena has done a stable job and Bloom Energy and Lumentum have stagnated somewhat without harming the portfolio too much. The special position in SanDisk improved the monthly average slightly. So we did everything right.
YTD the momentum performance is at an outstanding +122% TTWROR. 🤯😍
I hope to close above the 30k mark for June.
Here is a general summary of how the portfolio is made up before the stocks for June are published:
It consists of 3 pots:
Pot 1 selects the momentum stock from the MSCI World with the strongest momentum signal.
Pot 2 selects 4 stocks from the top 30% market capitalization (deciles 8 to 10) with the strongest momentum signal.
Pot 3 selects 3 stocks from deciles 7 to 9 with the strongest momentum signal.
It is to be expected that there will be duplications from the various pots. These are not overweighted, but kept simple. This means that there can be between 4 and 8 stocks in the portfolio.
How will the portfolio change in June?
It's nice to see that almost all stocks ended May on a positive note and even nicer to see that there will still be a change. This means that "from below" a stock has achieved stronger momentum than a stock that was held. In my view, this is the strategy's preferred behavior when it comes to switching.
Micron ($MU) (+3,36 %) is back, but Dell ($DELL (-3,14 %)) will also make it into the portfolio, displacing Ciena. According to the score, Western Digital would also be narrowly beaten by Intel ($INTC (-0,41 %)), but due to the 5% holding threshold there is no change. This means that Intel has once again narrowly missed out on the portfolio.
The composition for June follows:
- Kioxia (6,400 euros)
- Western Digital (6,400 euros)
- Bloom Energy (6,400 euros)
- Lumentum (3,650 euros)
- Micron (2,500 euros)
- Dell (2,500 euros)
- SanDisk (1,400 euros) --> not in the investment universe!
Evaluation of the pots:
Pot 1
Kioxia wins by a wide margin ahead of Micron and Ibiden ($4062) (+3,79 %).
Pot 2
Kioxia
Micron
Dell
Western Digital
A hair's breadth ahead of Intel, Seagate ($STX (+7,46 %)) and Murata Manufacturing ($6981 (+3,51 %))
Pot 3
Absolute dominance of
Kioxia
Bloom Energy
Lumentum
ahead of Ciena and, among others, RocketLab ($RKLB (-4,99 %) ).
May the games continue.
Only 35X to the million 🥹

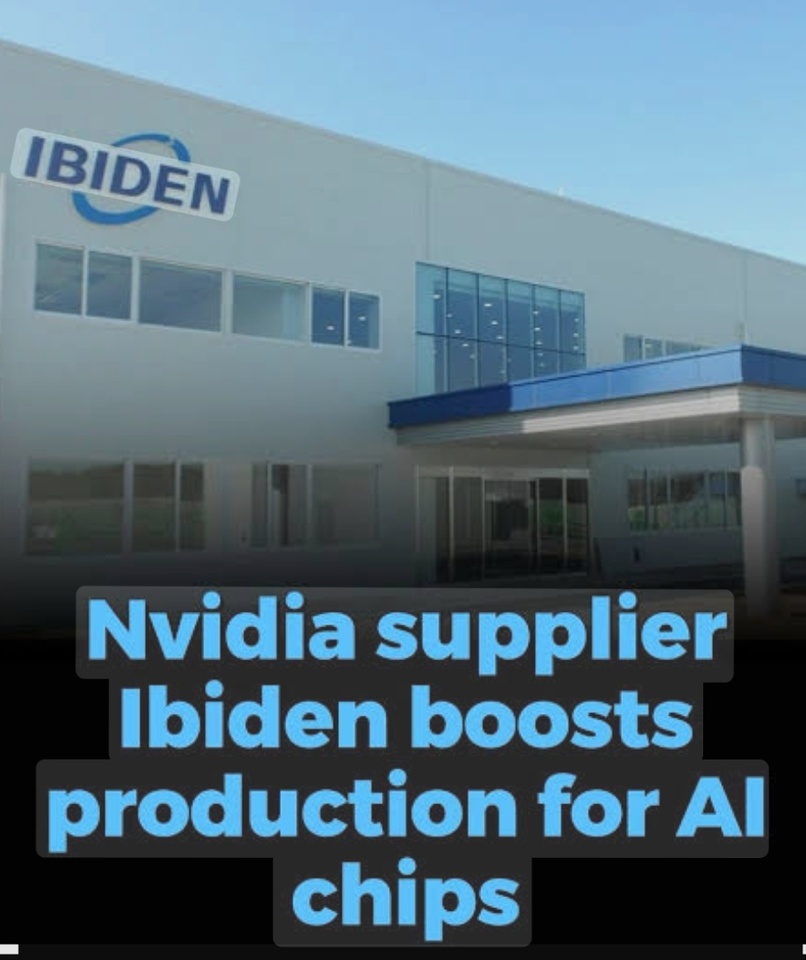
TB JAPAN TAG 🇯🇵 Ibiden: The silent hero of AI chip production from Japan. - Investing in blade suppliers -
$4062 (+3,79 %)
$NVDA (+1,14 %)
Hello my dears,
Maybe Japan Day will slowly turn into Japan Week.
Maybe also to introduce you to our Japan helper @PikaPika0105 to introduce you.
Anyone who knows me knows that I like to dive deep into the engine room. To look for hidden champions and blade suppliers for you.
While Nvidia can boast an annual performance of 18 %. This important blade supplier shines with an annual performance of 173 %.
That's why I'm a big fan of blade suppliers.
My dears, how many of you actually know Ibiden?
Attention, no investment advice.
Due to the good annual performance, a major correction is also possible with Ibiden.
An alternative would be $6981 (+3,51 %) Murata.
Ibiden is a key Japanese supplier to Nvidia, which manufactures highly specialized IC substrates (packaging materials for chips) for Nvidia's AI accelerators, which have to withstand enormous heat. The massive boom in generative AI is leading to strong demand for Ibiden products, which is why the company is massively expanding its production capacity to supply Nvidia and other AI chip manufacturers. Ibiden is considered the leading supplier in this niche market and is benefiting greatly from the AI revolution.
The relationship between Ibiden and Nvidia:
Critical component: Ibiden supplies the substrates that serve as the connection between the actual chip (GPU) and the PCB, which is critical for signal transmission and thermal regulation.
AI boom: Nvidia's success in the AI sector is directly driving demand for Ibiden products.
Technological challenge: Only a few companies can mass-produce the demanding substrates for Nvidia's high-performance AI chips, which secures Ibiden a strong market position.
Ibiden as a company:
Market leader: Ibiden is a leading global supplier of IC substrates for AI servers and has a dominant position in this market segment.
Expansion: The company is investing heavily in new factories (e.g. in Gifu Prefecture) to increase production for AI chips.
Diversification: Although Nvidia is a major customer, Ibiden also supplies other chip manufacturers such as Intel, AMD, Samsung and plans to supply in-house chips for Google and Microsoft.
To summarize, Ibiden is an "unsung hero" of the AI revolution and plays an indispensable role in Nvidia's supply chain by providing the physical base for the powerful AI chips.

Titres populaires
Meilleurs créateurs cette semaine