
Hello, everyone,
A recent analysis by TrendForce suggests that the NAND flash memory market is moving toward a balance between supply and demand, with full stabilization expected by the second half of 2027.
Gute Nachricht: NAND-Flash-Speicher-Knappheit soll bis 2027 enden
Despite strong numbers from Nvidia, this continues to cause uncertainty in the semiconductor sector.
That’s why I’ve once again gone searching for you—for a stock that isn’t affected by the uncertainty surrounding AI stocks.
Unlike tech stocks, we actually have a stock here that’s benefiting from rising inflation.
Inflation has significantly changed consumers’ shopping behavior.
We can see this clearly in the latest quarterly figures.
My friends, the new figures will be released tomorrow. The bold among you might even open a new position. (not an investment recommendation) @Multibagger , @Dividendenopi (Zockeropi)
Feel free to let us know in the comments.
Ross Stores Inc.: The discount retailer posts its best quarter ever and wins over Gen Z
(June 26, 2026)
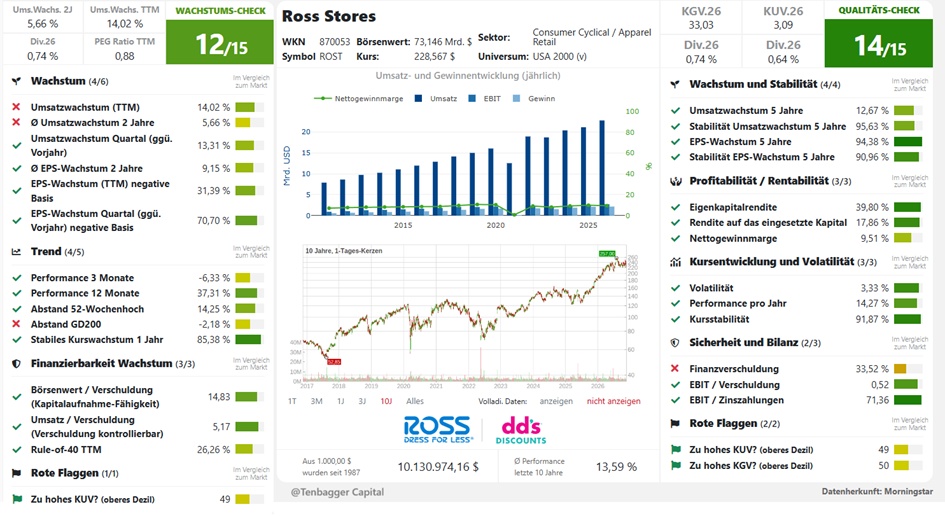
Ross Stores sells brand-name clothing, shoes, and home goods at prices up to 70% below regular department store prices. In the first quarter of 2026 , the company posted the strongest results in its forty-year history. Revenue rose 21%, and earnings per share increased 37%.
Will Ross Stores (ROST) once again exceed expectations in its next earnings report?
Looking at the last two reports, the discount retailer has had a strong streak of beating earnings estimates. The company has, on average, exceeded forecasts by 12.78% over the past two quarters.
Last quarter, Ross Stores was expected to report earnings of $1.93 per share but instead reported $2.06 per share, representing a 6.74% positive surprise. For the previous quarter, the consensus estimate was $1.70 per share, while it actually earned $2.02 per share—an 18.82% beat.
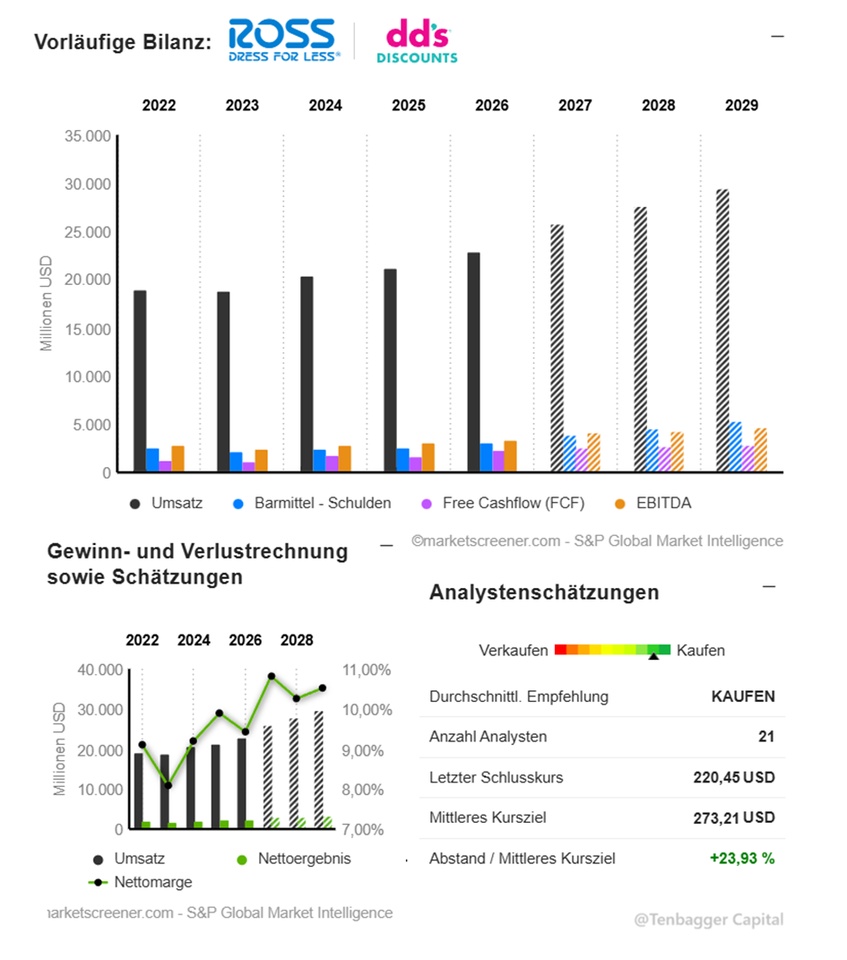
In the most recent fiscal year , Ross Stores Inc.’s revenue rose by 7.7%, from $21.1 billion to $22.8 billion. Net income increased by 2.6%, from $2.1 billion to $2.1 billion. The net profit margin was thus 9.4%, compared to 9.9% in the previous year.
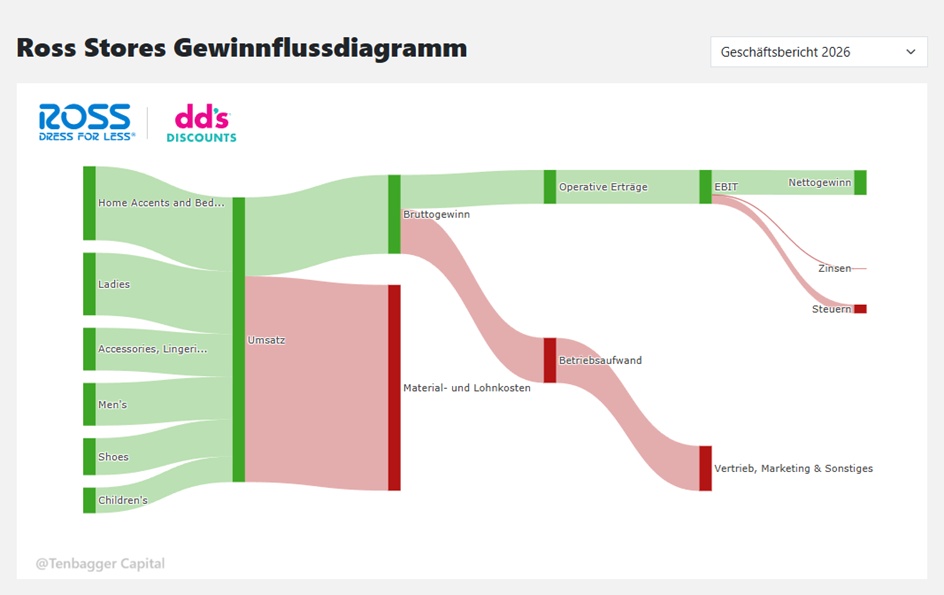
Ross Stores, Inc. is America’s second-largest retailer of name-brand clothing and accessories at discount prices. Net sales are broken down by product category as follows:
- Home goods (26%);
- Women’s apparel (22%);
- Men’s apparel (16%);
- Accessories (15%): jewelry, lingerie, perfumes, and cosmetics;
- Footwear (12%);
- Children’s apparel (9%).
As of February 1, 2025, the group operated a network of 2,186 stores, divided by brand name into Ross Dress For Less (1,831) and dd's DISCOUNTS (355).
All revenue is generated in the United States.
Number of employees: 111,000
In the Home Accents & Bed & Bath , Ross Stores sells home goods such as decorations, tableware, kitchen utensils, bed linens, towels, and bath mats through its own stores, which offer significant discounts compared to traditional retailers as an off-price retailer and represent the group’s highest-revenue segment. In the Ladies segment, the company sells women’s apparel—such as dresses, pants, tops, outerwear, and athletic wear—from renowned brands at off-price prices. In the Men's segment, the company offers men’s fashion such as shirts, pants, tops, outerwear, and sportswear. In the Accessories, Lingerie, Fine Jewelry, & Cosmetics segment, the company sells accessories such as bags and jewelry, women’s lingerie, high-end jewelry, and beauty products at off-price prices.
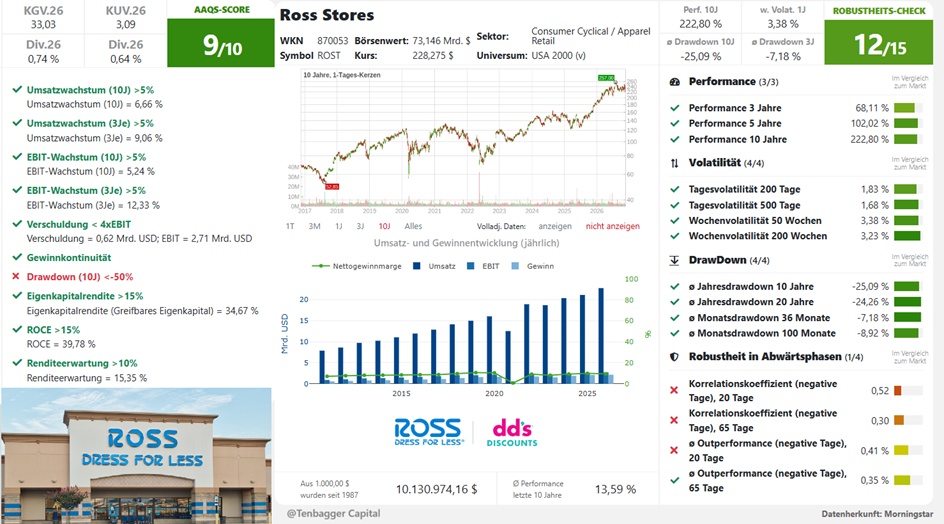
Ross Stores benefits from a recession-resistant off-price business model. The company maintains a high level of discipline in inventory management.
UPCOMING EVENTS
Q3 2026 Ross Stores, Inc. Gewinnkonferenzkonferenz
Nov. 19, 2026, at 4:15 p.m. EST
10/12/26
Ross Stores eröffnet 51 neue Standorte
Aug. 20, 2026
Ross Stores berichtet starke Umsatz- und Gewinnergebnisse im zweiten Quartal
July 20, 2026
Ross erweitert seine Präsenz mit 47 neuen Filialen
May 21, 2026
Company: Ross Stores
ISIN: US7782961038
Source exclusively:
MarketScreener – Finanzdaten Ross Stores
All financial figures in millions of USD, unless otherwise stated. Earnings per share in USD. The percentages indicate the respective change from the previous year.
Date of publication: March 3, 2026
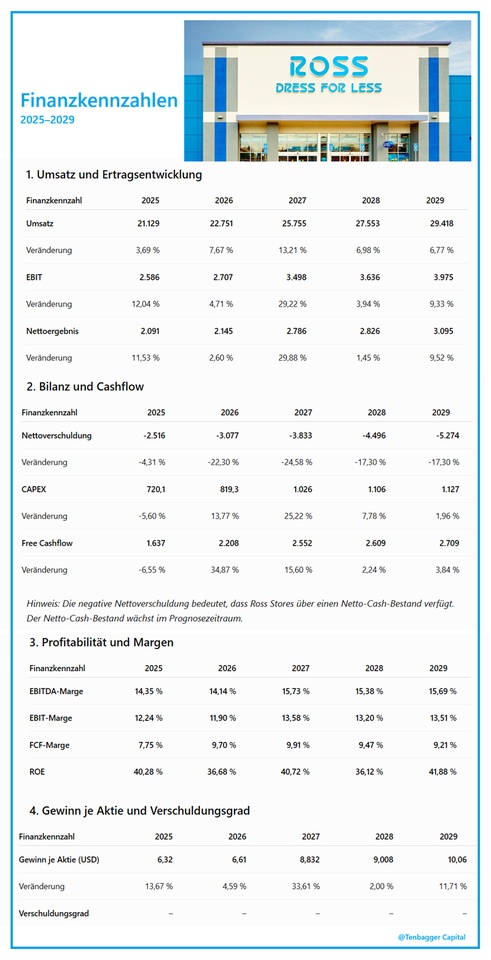
5. Investment-Relevant Developments 2025–2029
Three points stand out in particular:
Key Figure
Trend 2025–2029
Revenue
$21,129 million
$29,418 million
+39.2%
EBIT
$2,586 million
$3,975 million
+53.7%
Net Income
$2,091 million
$3,095 million
+48.0%
Free Cash Flow
$1,637 million
$2,709 million
+65.5%
Earnings per Share
$6.32
$10.06
+59.2%
My assessment:
Ross Stores exhibits an interesting quality profile:
- Growth: Revenue and earnings are rising steadily.
- Profitability: The EBIT margin is expected to remain above 13%.
- Cash Flow: Free cash flow is growing significantly faster than revenue.
- Balance Sheet: Net cash continues to increase.
- Return on Equity: Exceptionally high at around 36–42%.
The combination of rising profitability, strong cash flow, and a very solid balance sheet is particularly interesting.
Conclusion: Ross Stores is a company with impressive operational quality. However, the key question for an investment remains the valuation: How much growth is already priced into the current stock price?
My Assessment
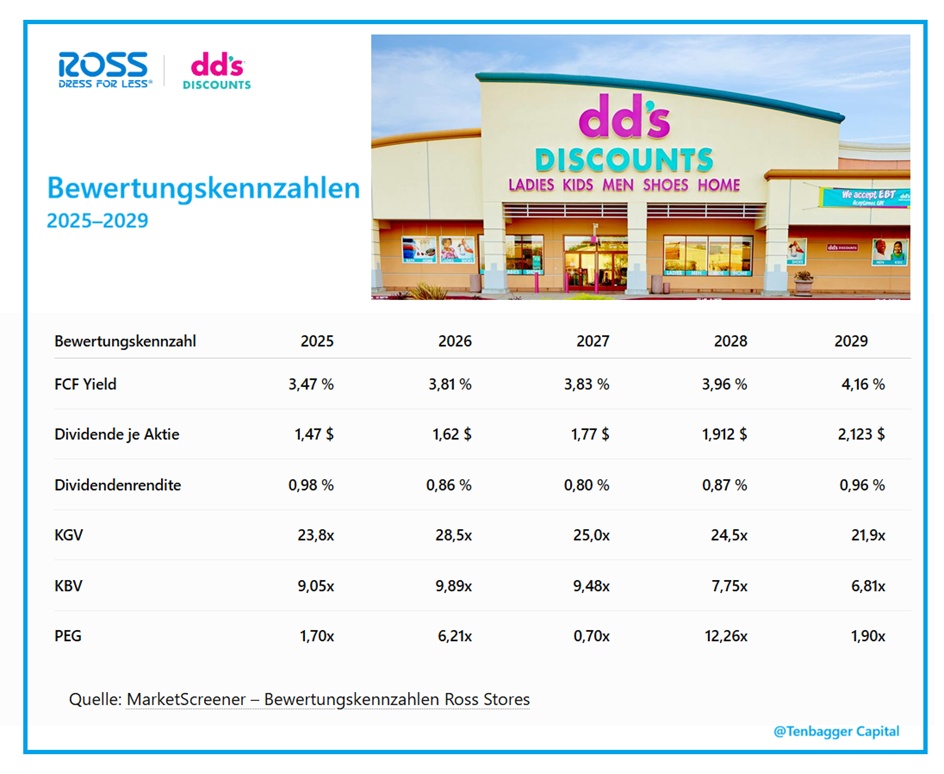
Three trends are worth noting:
FCF Yield: Rising steadily from 3.47% to 4.16%. This points to an improved free cash flow yield.
P/E ratio: Declining to 21.9 by 2029. This suggests a more favorable valuation given the assumed earnings growth.
Dividend: The dividend per share is increasing by approximately 44%.
Conclusion: Ross Stores is showing some interesting trends in its valuation metrics. In particular, the combination of a growing dividend, a rising FCF yield, and a declining P/E ratio deserves attention.
Note: The figures for 2027–2029 are analyst estimates. The dividend is stated in USD; no conversion to euros has been made.
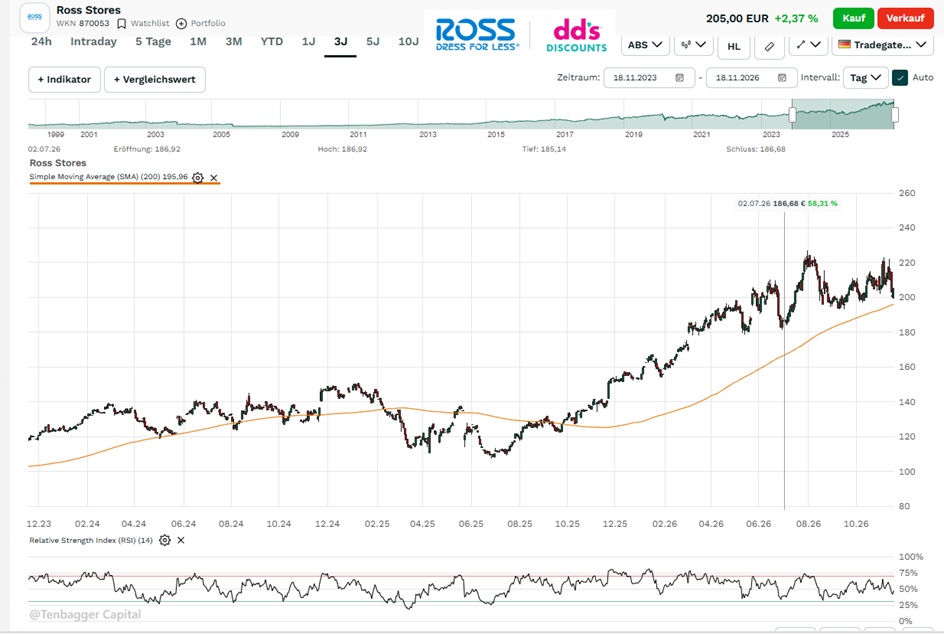
207.85 EUR +7.75 EUR +3.87%
5:03:47 PM
STU
227.06 USD+6.63 USD+3.01%
5:17:06 PM
BTT
