Hello, everyone,
Even though the current AI correction might make some of you less inclined to invest in tech stocks,
Take comfort in this: my portfolio has also taken quite a beating.
And despite the news about a few financing problems here and there, superintelligence can no longer be stopped.
Because, in my opinion, we’re already in the
- second wave –
And that’s exactly what today’s presentation—which I’d already started with ServiceNow—is all about.
The first wave of AI shaped the stock market: Nvidia, memory manufacturers, semiconductor equipment suppliers, data centers, and their suppliers took center stage. Companies invested billions in GPUs, networks, memory, and power supplies.
Now a crucial next phase is beginning: How can these investments be turned into a profitable business model?
Who pays for AI? Which companies can sell their products at a higher price? Where are entirely new markets emerging? And which companies from the Depot 2036 could benefit from this development?
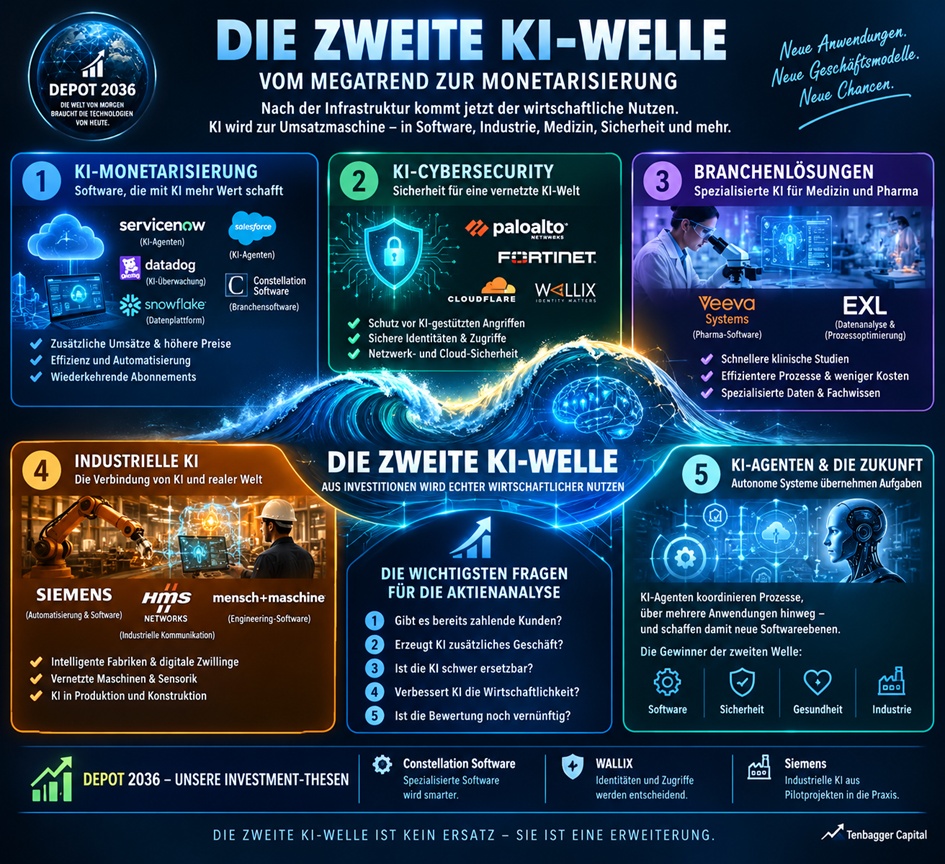
I would bet on the second wave of AI into six major areas:
AI monetization: Software companies that generate additional revenue through AI.
AI agents: Software that not only responds but also performs tasks independently.
AI Cybersecurity: Protection against AI-powered attacks and securing autonomous systems.
Vertical AI: Specialized applications in medicine, pharmaceuticals, and other industries.
Industrial AI: The integration of artificial intelligence with machines, factories, and robots.
The infrastructure behind the second wave: Data, networks, sensors, and industrial control systems.
My central thesis is:
The next exciting hunt for hidden gem stocks begins where AI delivers measurable economic results—and no longer merely consumes computing power.
For the Portfolio 2036 , this is particularly exciting because I already hold companies from several of these sectors.
A Comparison of the First and Second Waves of AI
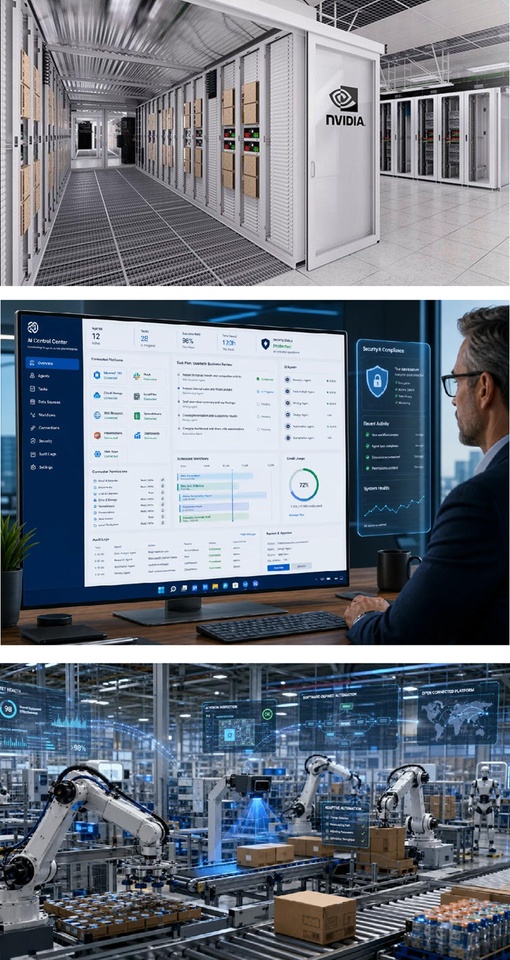
Nvidia wird im Jahr 2025 schätzungsweise 70 Prozent des HBM-Markts für KI beanspruchen
https://intellimindsdigital.com/use-cases/ai-for-workflow-automation/?utm_source=chatgpt.com
https://intelgic.com/industrial-automation-ai-machine-vision-systems?utm_source=chatgpt.com
https://airisdynamics.com/blog/computer-vision-manufacturing?utm_source=chatgpt.com
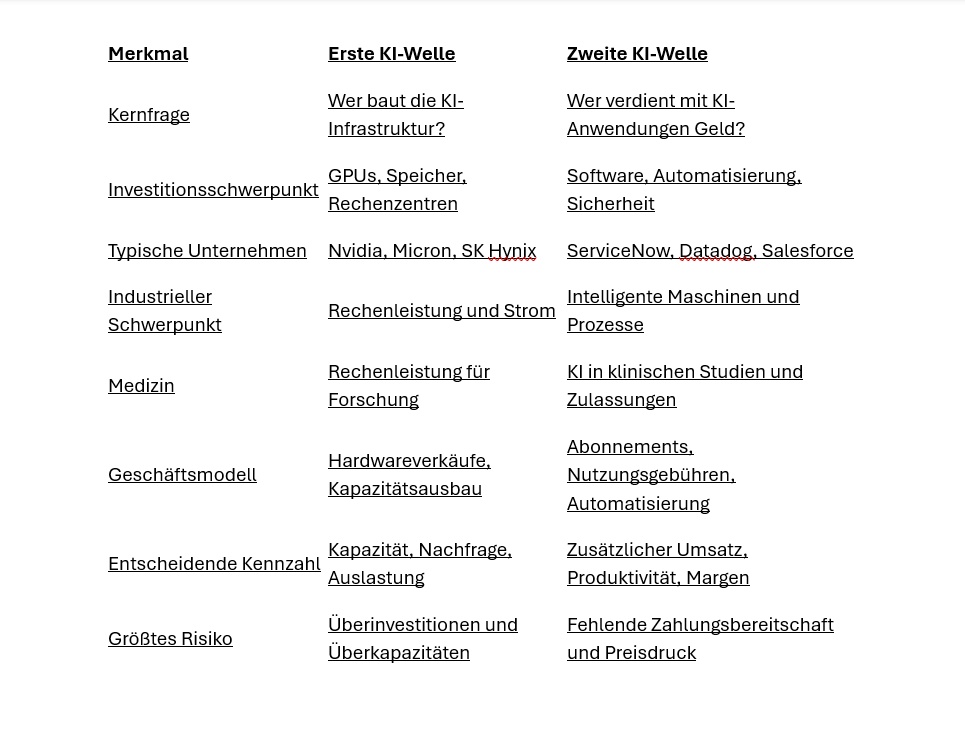
The two waves will overlap in time. The second wave does not replace the first, but rather builds upon it.
Powerful AI still requires memory, networks, data centers, and energy. But as its adoption grows, the crucial question shifts:
Which companies can claim a share of the economic benefits?
This is the point where we need to take a closer look in our stock analysis.
My friends, this is once again about stock picking—feel free to check out my post on the topic.
2. AI Monetization: Which software companies are already making money?
This is where I’d start. After all, we don’t have to wait for some distant future to find the first evidence of viable business models.
There are companies where AI is already evident in revenue figures, contract volumes, or rising demand.
2.1 ServiceNow – AI as a Paid Employee
(Feel free to check out my overview of ServiceNow)
For me, ServiceNow is one of the most interesting examples when it comes to understanding how companies can monetize AI.
The company automates workflows in large organizations. This includes IT services, human resources, customer service, and other business processes.
This new development goes beyond a simple chatbot.
For example, an AI agent can:
- detect an IT issue,
- analyze the cause,
- develop a proposed solution,
- carry out defined actions,
- and document the process.
The key difference: The AI doesn’t just answer a question—it takes on part of the actual work.
Key metric
Result
Quarterly revenue
$3.987 billion
Revenue growth
+24%
Subscription revenue growth
+24.5%
Annual Contract Value of ServiceNow AI
Over $1 billion
Remaining performance obligations
$29 billion
The company also raised its revenue forecast for the full year. The number of productive agent-based AI implementations had increased ninefold within nine months.
Why is this important for the second wave of AI?
ServiceNow demonstrates that AI can be more than just a value-added feature. It can become a standalone growth driver for an established software company.
What I would keep an eye on
- How quickly is the contract value of AI products growing?
- Are additional features actually subject to fees?
- Can customers demonstrably reduce staffing costs and processing times?
- Will growth remain strong once the initial experimental phase is over?
Depot 2036 Assessment: ServiceNow is a good benchmark company for AI monetization. However, this is not proof that every software stock will benefit from this trend.
2.2 Datadog – Monitoring, Securing, and Controlling AI
Datadog is particularly interesting for the second wave of AI because AI systems increase technical complexity.
Companies must not only monitor their traditional applications; they must also understand what their AI models and agents are doing.
This includes questions such as:
- Why is an AI model suddenly delivering poorer results?
- Which query is causing particularly high costs?
- Where are delays occurring?
- What data is being processed?
- Did an autonomous agent trigger an error?
- Has an AI system possibly been compromised?
Datadog is therefore expanding its platform to include AI monitoring, security, and automation.
The numbers point to high demand
In the second quarter of 2026, Datadog achieved:
Metric
Result
Quarterly Revenue
$1.12 billion
Revenue growth
+36%
Free cash flow
$279 million
Customers with at least $100,000 in ARR
Approximately 4,720
The company also launched additional AI features, including autonomous capabilities for detecting, investigating, and resolving issues.
My Thesis
The more AI applications are put into productive use in enterprises, the greater the need to monitor these systems and operate them cost-effectively.
Datadog can generate revenue in several areas: traditional cloud monitoring, security, and the increasing complexity of AI applications.
The risk: With usage-based business models, customers can optimize their spending. Strong AI growth therefore does not necessarily lead to a proportional increase in profits.
Context: An interesting candidate for combining AI, the cloud, and cybersecurity.
2.3 Snowflake – No Data, No Intelligent AI
Snowflake addresses a key weakness in many AI projects: while companies possess large data sets, they cannot readily make them usable for AI.
An AI model is of limited value if it does not understand the company’s internal data, rules, and business processes.
Snowflake enables companies to store, process, and make data available for analytics and AI applications.
With offerings such as Cortex AI, the platform is increasingly becoming an environment where companies can apply AI directly to their data.
Recent Developments
In the second quarter of fiscal year 2027, Snowflake reported:
Key Figure
Result
Quarterly Revenue
$1.55 billion
Product revenue
$1.49 billion
Growth in product revenue
+37%
Net revenue retention
126%
Remaining service obligations
$9 billion
Snowflake subsequently raised its forecast for product revenue in fiscal year 2027. The company attributed the stronger performance, among other factors, to demand for AI applications.
Put simply, a net revenue retention rate of 126% means that existing customers generate, on average, 26% more revenue than in the corresponding prior-year period, before accounting for the impact of churn.
Why Snowflake Is Exciting
Snowflake could benefit from a trend in which companies are increasingly building AI applications on top of their own data.
The potential growth cycle:
More AI applications → more data processing → more platform usage → additional revenue.
However, Snowflake isn’t automatically a winner for every AI application. Customers can reduce costs, make data processing more efficient, or use alternative platforms.
Classification: A candidate for monetizing the data foundation of AI.
2.4 Salesforce – When AI Directly Serves Customers
Salesforce is pursuing a different strategy with Agentforce.
The company integrates AI agents into existing business processes. For example, they can handle customer inquiries, support sales representatives, and automate service workflows.
Of particular interest here is the existing customer base: Salesforce already has customer data, business processes, and enterprise applications into which AI can be integrated.
In the second quarter of fiscal year 2027, Salesforce reported:
Key Figure
Result
Quarterly Revenue
$11.3 billion
Revenue growth
+11%
Agentforce ARR
Over $1.5 billion
Agentforce and Data 360 ARR
Just under $3.9 billion
Growth of Agentforce and Data 360 ARR
Over +210%
The AI and data metrics cited refer to the annual recurring revenue as defined by Salesforce; they should not be equated with actual quarterly revenue
Salesforce liefert Rekordergebnisse für das Geschäftsjahr 2027 im zweiten Quartal – Salesforce
This is an important distinction: A rising annual contract value indicates that customers are willing to pay for AI. However, it does not, on its own, show how profitable these products will be in the long term.
Salesforce must prove that Agentforce drives additional growth and does not merely replace existing software revenue.
My assessment
With its established customer relationships, data, and business processes, Salesforce possesses key prerequisites for AI monetization.
The decisive factor will be whether AI agents deliver sufficient economic value for companies to continue paying for them over the long term.
2.5 And what about Constellation Software?
Here’s where it gets interesting for Portfolio 2036 .
Because I’m already invested here.
Constellation Software follows a different business model than ServiceNow or Salesforce.
The company acquires specialized software providers that often solve very specific industry problems. These applications are often deeply embedded in their customers’ workflows.
For example, one can imagine software that supports a specific municipal administration, a specialized service provider, or a niche provider in the industry.
Why could AI be a major opportunity here?
Many of these applications share three characteristics:
Specialized data: They contain industry-specific information that general AI models do not automatically possess.
Well-established workflows: The software is integrated into customers’ daily routines.
High barriers to switching: Switching can be costly and risky, especially when core business processes are involved.
AI could add new features to these applications: automated document processing, smarter search functions, forecasting, or the automation of recurring tasks.
The company does not need to develop the leading AI model itself to achieve this.
It could leverage existing AI technologies to make its industry-specific applications more attractive.
The Key Difference
With ServiceNow and Salesforce, we see concrete AI platforms with proven contract metrics.
With Constellation Software, the investment thesis is more a matter of long-term execution:
- How quickly will the individual software companies integrate AI?
- Can they generate additional revenue?
- How high are the costs for development and external AI services?
- Will customer loyalty remain high even if AI makes it easier to develop new competing products?
I would therefore view Constellation Software as a potential indirect beneficiary of the second wave of AI .
An important caveat: AI can also make the development of competing software cheaper. This could put pressure on individual niche providers.
This is an interesting thesis for the 2036 portfolio, but we shouldn’t automatically assume that Constellation has already achieved the same level of direct AI monetization as ServiceNow.
4. Cybersecurity: The AI wave creates new vulnerabilities
https://www.netcontroll.com/network-security?utm_source=chatgpt.com
https://divihn.com/perspectives/article/zero-trust-as-an-enterprise-security-https://en.rainbowtec.com/blog-posts/como-evitar-acesso-indevido?utm_source=chatgpt.commodel?utm_source=chatgpt.com
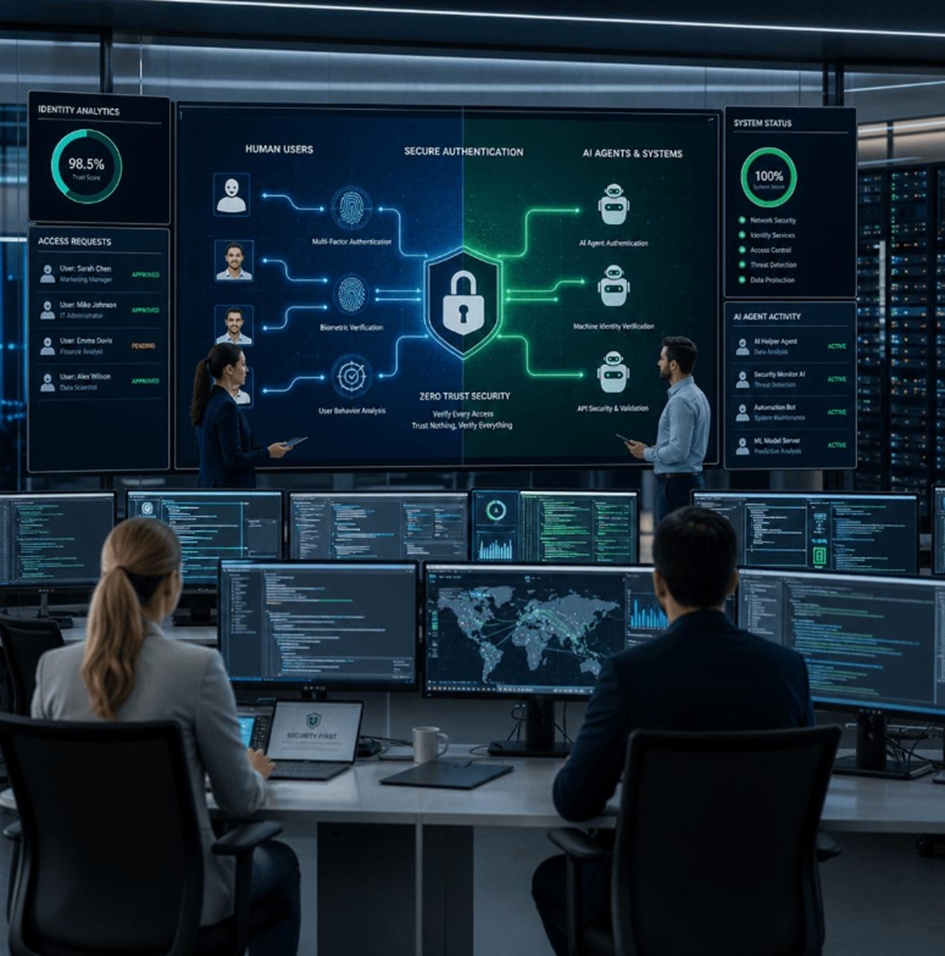
This sector could become one of the structurally most important winners of the second wave of AI.
Why?
AI not only reduces the effort required for productive activities; it can also facilitate the automation of cyberattacks.
At the same time, new risks are emerging from AI agents that access corporate data, operate applications, and, in some cases, carry out actions autonomously.
Companies therefore need additional security mechanisms.
In this context, we must distinguish between two markets:
- Traditional IT security: Protecting networks, endpoints, identities, and cloud systems.
- AI security: Controlling AI models, agents, their permissions, data access, and actions.
Many companies will need both areas.
3.1 Palo Alto Networks
Palo Alto Networks covers several areas of cybersecurity, including network security, cloud security, and enterprise security platforms.
The strategic opportunity lies in the fact that customers could consolidate as many security functions as possible into a single, integrated platform.
With the increasing use of AI, additional requirements are emerging for securing applications and infrastructure.
Palo Alto Networks reported strong financial results for the fourth quarter of its 2026 fiscal year and highlighted demand for its network and AI security platforms, Cortex and Idira. The company added nearly one billion U.S. dollars in additional annual contract value in the Next-Generation Security segment during the quarter.
What I’d be watching for
- Growth in the recurring security business.
- New AI security products and actual customer demand for them.
- Free cash flow trends.
- Costs and integration of acquisitions.
- Ability to compete against established and new competitors.
Investment thesis: Palo Alto Networks could benefit as companies expand and consolidate their security architectures in light of increasing AI usage.
However, this is not a risk-free market: high expectations, competition, and potential security incidents can influence the company’s valuation and customer confidence.
3.2 Fortinet
Fortinet combines networking technology and security.
This is interesting because AI not only requires additional software but also needs to communicate reliably and securely with corporate networks.
As data centers, industrial facilities, and cloud systems become increasingly interconnected, the importance of network security is growing.
Fortinet could therefore benefit in two ways:
- through the expansion of traditional network security;
- by meeting the rising security requirements of more complex, AI-powered infrastructures.
However, not every additional AI application automatically translates into an additional order for Fortinet.
The key factor remains whether the company can offer compelling benefits over existing security solutions and gain market share.
3.3 Cloudflare
Cloudflare is particularly interesting because the company operates at the intersection of network infrastructure, application security, and developer platforms.
The AI wave could open up several opportunities for Cloudflare:
- running AI applications closer to users;
- protecting data and applications against attacks;
- Providing developers with a platform for AI applications;
- efficiently routing traffic between users, applications, and AI systems.
This is a different approach than that of pure-play software providers.
Cloudflare could benefit as more and more companies develop and deploy AI applications without wanting to operate their entire infrastructure themselves.
The risk: Competition for cloud and AI infrastructure is intense. Additionally, monetizing AI services may initially require significant investment.
3.4 My Portfolio 2036 Stock: WALLIX
Now we come to a particularly interesting company for the second wave of AI.
WALLIX specializes in identity and access management, particularly in controlling privileged access.
Why might this become more important in the AI era?
Imagine an AI agent that is not only allowed to read information, but also to:
- access internal corporate systems;
- modify databases;
- initiate production processes;
- manage user accounts;
- perform administrative actions.
This raises a new security question:
Who is authorized to grant this AI which permissions—and who monitors what it actually does?
This is where identity and access management becomes a critical component of a secure AI infrastructure.
The Potential Role of WALLIX
WALLIX could benefit from increasing demands for privileged access and the control of digital identities.
It’s important not to overpromise: The traditional protection of human administrators and technical accounts is already an established business area. The additional demand for securing autonomous AI agents is an opportunity whose actual economic significance remains to be seen.
In May 2026, WALLIX published a statement on sovereign AI cybersecurity and its partner network. The company is thus expanding its positioning in this field.
https://www.wallix.com/de/ueber-uns/newsroom/?utm_source=chatgpt.com
I will be keeping an eye on three things at WALLIX
1. AI agents and privileged access
Will concrete products emerge that securely manage AI agents and control their permissions?
2. New customers and larger contracts
Will this area become a measurable growth driver, or will it remain primarily a strategic positioning for now?
3. Recurring revenue and profitability
Can WALLIX translate its market position into rising revenue and better margins over the long term?
My assessment for the 2036 portfolio
I view WALLIX as an interesting company for illustrating the AI security thesis.
The potential upside lies in the fact that more and more autonomous systems require controlled access rights.
At the same time, we must keep an eye on the company’s size, competitive position, and actual market penetration.
The key question is not only whether AI requires more security, but whether WALLIX can capture a economically significant share of this additional demand.
5. Healthcare and Pharmaceuticals: AI Is Becoming a Specialized Tool
https://voka.io/biotech-biopharma-industry-trends/?utm_source=chatgpt.com
https://community.spotfire.com/articles/spotfire/clinical-safety-https://sourceforge.net/software/product/Altis-Labs-Nota/?utm_source=chatgpt.commonitoring/?utm_source=chatgpt.com
https://n-economia.com/buenaspracticas/recursion-https://www.ontimeedge.com/blog/creating-a-digital-lab-with-zontal-innovation-at-leading-pharma-company?utm_source=chatgpt.compharmaceuticals/?utm_source=chatgpt.com
https://community.jmp.com/t5/JMPer-Cable/New-in-JMP-Clinical-17/ba-p/562265?utm_source=chatgpt.com
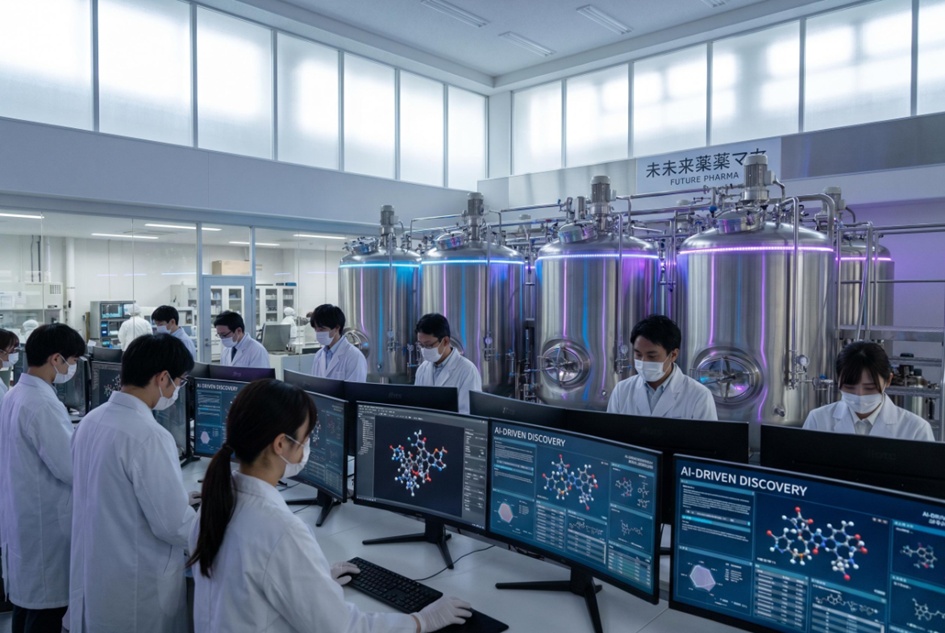
In the healthcare sector, the second wave of AI could prove particularly interesting, as it brings together large volumes of data, complex processes, and stringent documentation requirements.
AI does not necessarily have to discover a new drug to generate economic value.
It can also help to
- plan clinical trials more efficiently;
- review medical documents;
- meet regulatory requirements;
- consolidate data from various sources;
- automate processes in drug development.
Specialized software companies, in particular, could develop new business models from this.
4.1 Veeva Systems
Veeva develops software specifically for the pharmaceutical and biotechnology industries.
Among other things, the company supports clinical research, quality management, regulatory documentation, and commercial processes.
This specialization is crucial: A general AI model does not automatically understand the industry-specific requirements and workflows that play a role in the development and marketing of drugs.
AI as an Additional Product Layer
With its AI offerings, Veeva is developing solutions designed to automate workflows in the pharmaceutical industry, among other things.
One example is Falcon, which provides AI capabilities for reviewing medical, legal, and regulatory content.
This could help companies streamline certain review processes.
In the second quarter of fiscal year 2027, Veeva reported:
Key Figure
Result
Total Revenue
$928 million
Revenue Growth
+18%
Subscription Revenue
$766.8 million
Subscription Revenue Growth
+16%
The company also reported progress on its AI offerings and strong performance from Vault CRM
https://ir.veeva.com/financials/quarterly-results/default.aspx?languageid=1&utm_source=chatgpt.com
What makes Veeva an attractive investment?
Veeva combines three key attributes:
Specialized software for a complex industry.
Long-standing customer relationships and established workflows.
The ability to integrate AI into existing products.
The key question is whether AI will further strengthen customer loyalty and generate additional revenue growth.
One risk is that new AI providers could offer individual workflows at lower prices. Veeva must therefore demonstrate the value of its integrated platform.
4.2 My Portfolio 2036 Stock: EXL Service
EXL takes a slightly different approach.
EXL combines data analytics, AI, and services to improve business processes for clients.
Among other things, the company works with data-intensive industries such as insurance, financial services, and healthcare.
This is interesting in the context of the second wave of AI because many companies need more than just an AI model.
They need someone who understands their data, analyzes their processes, and integrates the technology into their operations.
Where might the opportunity lie?
EXL could benefit if customers become increasingly willing to redesign business processes using AI.
Examples include:
- automated processing of insurance claims;
- support for the analysis of medical data;
- smarter customer service;
- automated document processing;
- forecasting and decision support.
The key point: EXL doesn’t just sell software. The company can also generate revenue from the implementation and deployment of AI solutions.
This opens up opportunities but also carries additional risk.
If AI replaces human labor, traditional service revenues could come under pressure. EXL must therefore demonstrate that the added value generated by AI products, data expertise, and more complex services more than offsets this effect.
EXL is of interest to the 2036 portfolio because monetizing AI doesn’t have to rely solely on software licenses. Companies that integrate AI into real-world business processes could also benefit.
5. Industrial AI: This is where the second wave could become particularly tangible
https://intelgic.com/industrial-automation-ai-machine-vision-systems?utm_source=chatgpt.com
https://india.rexel.co.in/siemens?utm_source=chatgpt.com
https://webinars.sw.siemens.com/ko-KR/smart-manufacturing-transformation/?utm_source=chatgpt.com
https://inosimmuhendislik.com/?utm_source=chatgpt.com
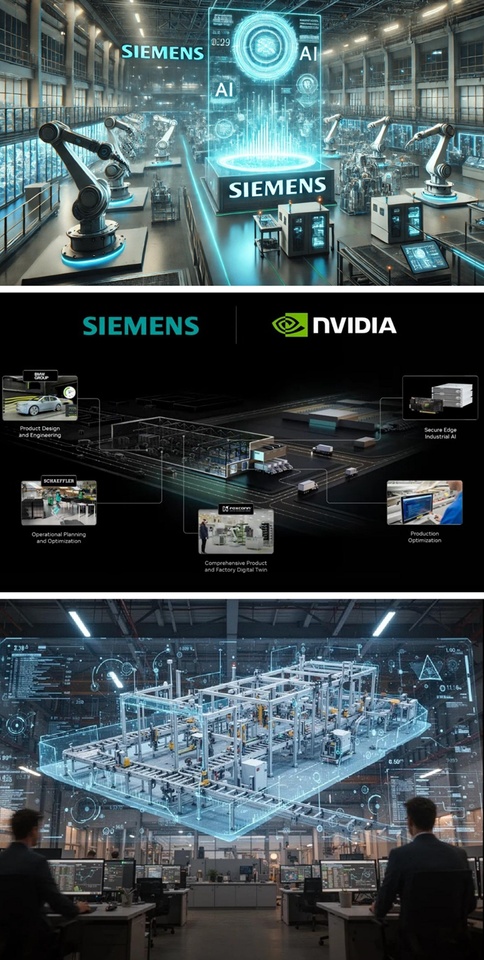
Now we come to the area I find particularly exciting for long-term development: the connection between AI and the real world of industry.
An AI agent that writes a text is one thing.
An AI system that monitors a production facility, analyzes machine conditions, suggests maintenance measures, and coordinates robots is something else entirely.
This is where software meets the physical world.
And that is precisely what could trigger the next major investment phase.
5.1 Current Developments in Germany
The federal government is working to integrate industrial AI more deeply into the economy.
As early as April 2026, Chancellor Friedrich Merz highlighted the opportunities presented by industrial AI at the Hannover Messe. In July, the federal government, industry, and the research community realigned the Industry 4.0 platform to focus more on industrial AI, with the goal of making data-driven and AI-based applications the standard in German industry by 2030
On October 16, 2026, the Tagesschau news program also reported on a planned collaboration between the federal government and Nvidia to promote industrial AI. According to the report, German companies such as Siemens are also expected to be involved; the focus will be on, among other things, physical AI and smart factories. At the time of the report, the collaboration was the subject of ongoing planning and media coverage.
For us as investors, one thing in particular is of interest here:
When AI moves from the digital world into factories and machines, new opportunities arise for companies that understand industrial processes.
These include automation, sensor technology, industrial communication, control technology, and software.
5.2 Siemens – The Connection Between AI and Manufacturing
I’m invested in Siemens through Portfolio 2036.
Siemens is particularly relevant to this development.
The company has expertise in industrial automation, control technology, digital twins, and industrial software.
These areas can be combined to use AI not only for analysis but also to integrate it into production processes.
An example
A factory wants to make its production more efficient.
To do this, the AI system must:
Collect machine data.
Understand production processes.
Detect deviations.
Assess the impact on quality and throughput.
Suggest improvements.
Implement changes into production in a controlled manner.
Siemens is active at several of these levels.
Its strength lies not only in AI itself, but in the combination of software, automation, and industrial experience.
Why is this important for Depot 2036?
Siemens could benefit from industrial AI without having to develop the leading general-purpose AI model itself.
The company can integrate AI with its existing automation and software solutions.
At the same time, one should not assume that every industrial AI initiative will immediately lead to high additional revenue.
Implementation in factories is complex. Customers must integrate systems, ensure data quality, and meet safety requirements.
My thesis: Siemens could become a major beneficiary once industrial AI moves from pilot projects to full-scale production.
5.3 HMS Networks – Industrial Data Traffic
HMS Networks is significantly smaller and more specialized than Siemens.
The company offers solutions for industrial communication and networking.
Why could this become important in the second wave of AI?
A smart factory needs more than just AI models. Machines, sensors, controllers, and software must communicate with one another.
In practice, industrial systems are often heterogeneous. Machines from different manufacturers, using different protocols and belonging to different generations, must be connected to one another.
HMS Networks operates in this environment.
The Potential AI Leverage
As more production facilities are digitized, the demand for the following is likely to increase:
- industrial networking;
- reliable data transmission;
- interfaces between different systems;
- remote maintenance and monitoring;
- secure communication between machines.
AI requires this data to understand production processes.
This gives rise to an interesting indirect investment thesis:
More industrial AI can generate greater demand for industrial communication.
However, this does not necessarily translate proportionally into revenue growth. Demand also depends on the industry’s overall willingness to invest, competition, and the scale of new plant projects.
HMS Networks would therefore be a candidate worth watching in the context of industrial AI.
5.4 Mensch und Maschine – AI in the Design Process
Human and Machine is also interesting because AI can be used not only in production but also as early as the product design phase.
The company specializes in CAD/CAM and engineering software as well as related services.
Here, for example, AI could help accelerate design processes, automate repetitive tasks, and analyze technical data more efficiently.
The business opportunity lies in the fact that engineers can get more work done with existing resources.
However, there is one key difference compared to a traditional AI platform provider:
Mensch und Maschine does not necessarily have to develop its own large AI models to benefit. Rather, the company could create added value by integrating new AI functions into established engineering workflows.
The following questions would be particularly crucial for the analysis:
- Which AI functions are actually offered?
- How do they change the demand for the products?
- Can higher prices or additional revenue be achieved?
- Does productivity improve without putting pressure on margins?
Siemens
Automation, Control, Industrial Software
Integrating AI into production processes
HMS Networks
Industrial Communication and Networking
Connecting Machines and Systems
People and Machines
CAD/CAM and Engineering
Making Design and Technical Workflows More Efficient
These companies operate at different levels.
They are therefore not simply interchangeable AI investments.
6. The Next Level: AI Agents Become Autonomous Systems
So far, we’ve mainly talked about AI as a tool.
The next development could go beyond that.
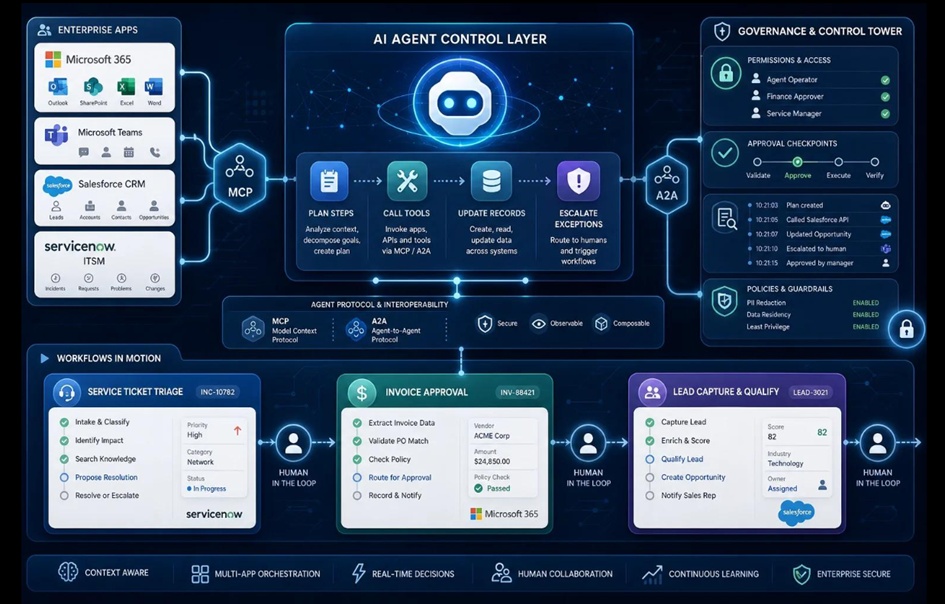
An AI agent can not only analyze a task but also execute it autonomously across multiple steps.
An example from industry:
A system detects that a machine is consuming an unusually high amount of energy. It analyzes the measured values, compares them with historical data, identifies possible causes, and creates a maintenance order.
With the appropriate permissions, it could even create the order on its own and schedule a technician.
This would represent a different business model than a simple chatbot.
A new layer of software is emerging that coordinates processes across multiple applications.
Companies in several sectors could benefit from this:
Sector
Potential Beneficiaries
Workflows
ServiceNow
Customer Service and Sales
Salesforce
Cloud and Application Monitoring
Datadog
Data Platforms
Snowflake
Identity and Access Management
WALLIX
Industrial automation
Siemens
Industrial communication
HMS Networks
These companies could profit from the same trend at different levels.
However, new competitors will also emerge. AI agents can take over functions that are currently still provided by standalone software products.
The second wave of AI therefore brings not only new opportunities but also a redistribution of existing software revenue.
7. Which companies are already monetizing AI—and which ones have the most potential?
Here, we should distinguish between proven monetization and a long-term investment thesis.
The following categories are not a ranking of stocks nor a statement about which valuations are attractive today.
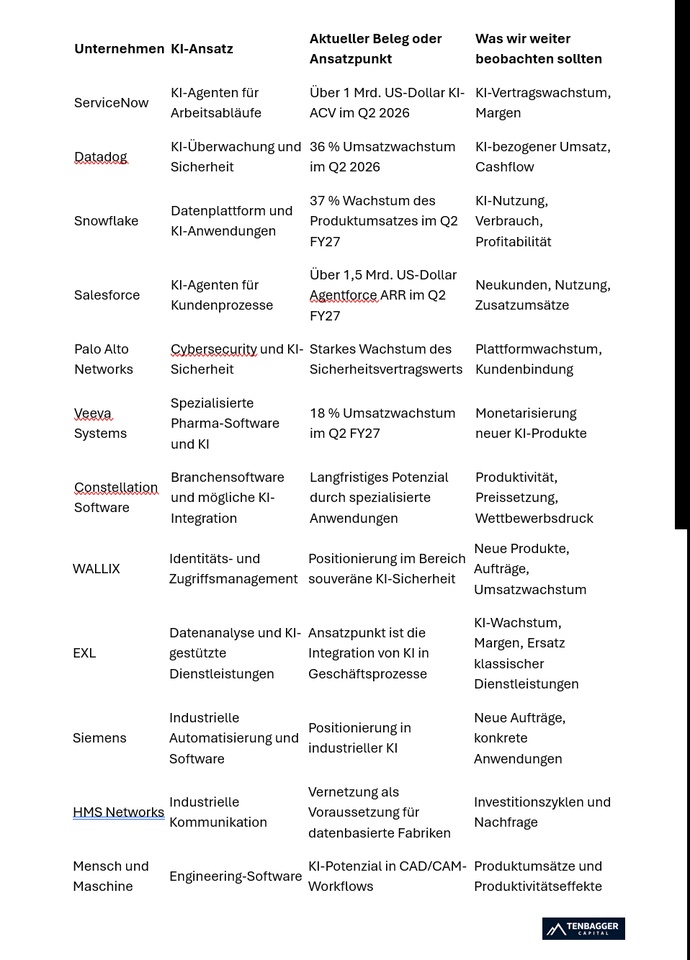
Sources for the reported current metrics: Company announcements from ServiceNow, Datadog, Snowflake, Salesforce, Veeva, and Palo Alto Networks. The potential of the remaining companies should be understood as investment theses, not as evidence of AI revenue already realized.
8. How I might structure the second AI wave for Portfolio 2036.
This time, I wouldn’t sort the companies by their name recognition or stock price performance.
I would rank them based on the economic function they fulfill in the second wave of AI.
Pillar A: AI Makes Money with Software
Companies: ServiceNow, Datadog, Snowflake, Salesforce, and Constellation Software.
The key question here is whether AI enhances existing software products and enables additional revenue.
For ServiceNow and Salesforce, we see concrete AI contract metrics. At the same time, Datadog and Snowflake are showing strong revenue growth in areas critical to running data-intensive AI applications.
Constellation Software is a different story: Here, we’re primarily interested in how well a broad portfolio of specialized software providers can integrate AI into existing applications.
Pillar B: AI Must Be Secured
Companies: Palo Alto Networks, Fortinet, Cloudflare, and WALLIX.
The more companies put AI to productive use, the more important it becomes to secure data, applications, identities, and networks.
WALLIX is particularly interesting for Depot 2036 because controlling privileged access could become increasingly important in a world of autonomous agents.
However, the investment thesis depends on whether this actually results in additional products and revenue.
Pillar C: AI Becomes Industry-Specific
Companies: Veeva Systems and EXL.
The opportunities lie in specialized data sets, industry-specific knowledge, and integration into existing workflows.
Veeva focuses more on specialized software, while EXL combines data analysis with services.
Both business models can benefit, but they must demonstrate that AI creates new economic value and does not merely replace existing services.
Pillar D: AI Is Transforming the Industry
Companies: Siemens, HMS Networks, and Mensch und Maschine.
This is where the connection between digital models and the physical world is formed.
Siemens covers industrial automation and software. HMS Networks is relevant for the networking of industrial systems. Mensch und Maschine could benefit from smarter engineering processes.
These companies could become particularly interesting as industrial AI increasingly moves beyond pilot projects.
9. The Five Most Important Questions for Finding AI Gems
Not every company that labels its products as “AI” will be a winner.
I would ask five questions of every candidate.
1. Are there already paying customers?
A product can be technically impressive yet still lack a profitable business model.
We should distinguish between free features, pilot projects, the order backlog, and actual recurring revenue.
2. Does AI generate additional business?
It’s not enough for a company to simply offer a new AI feature.
It becomes interesting when customers buy additional products, pay higher prices, or use more services.
3. Is the AI hard to replace?
A company does not automatically have a competitive moat just because it uses AI.
A competitive advantage can arise from specialized data, deeply integrated workflows, high switching costs, regulatory expertise, or the integration of software and hardware.
4. Does AI improve profitability?
If a software company has to pay a disproportionately high amount for computing power and external models for every additional euro in revenue, monetization may be less attractive than expected.
We should therefore look not only at revenue but also at gross margins, free cash flow, and the costs of developing new products.
5. Is the valuation still reasonable?
Even an outstanding company can be a disappointing stock if the expected earnings are already very generously priced in.
That’s why the second wave of AI always involves two types of analysis:
- Company analysis: How good is the business model?
- Valuation analysis: How much growth is already factored into the stock price?
Only when combined do they form a robust investment thesis.
10. My Conclusion: The Second Wave of AI Could Be Broader Than the First
The first wave of AI primarily brought to the forefront companies that provide the technical foundation.
The second wave could extend to other industries as companies increasingly integrate AI into their actual workflows.
In this context, I see four developments we should pay particular attention to:
First: AI is becoming part of existing software.
ServiceNow, Salesforce, Datadog, and Snowflake demonstrate different ways in which AI can be integrated into and monetized through established platforms.
Second: Security is becoming a prerequisite for productive use.
Palo Alto Networks, Fortinet, Cloudflare, and WALLIX could benefit from rising demands for the protection of digital systems.
Third: Specialized industry solutions are gaining importance.
Veeva and EXL demonstrate that AI can deliver economic value not only through general-purpose models but also through specialized knowledge and integration into specific processes.
Fourth: AI is making its way into the physical world.
Siemens, HMS Networks, and Mensch und Maschine could become interesting investments as smart factories, connected machines, and AI-supported engineering processes are increasingly put to productive use.
However, the opportunities are not evenly distributed. Some companies will generate new revenue with AI. Others will simply have to adapt their products to remain competitive. Still others could come under pressure from new AI-driven competition.
My personal conclusion for the 2036 portfolio
I don’t view the second wave of AI as a replacement for previous AI investments, but rather as a broadening of our perspective.
My friends, that’s why I’m staying invested in the first wave.
In addition to companies that provide storage, computing power, and infrastructure, those that translate AI into concrete products and workflows are increasingly taking center stage.
I find three interconnected investment theses particularly exciting:
- Constellation Software: Can specialized industry software become more powerful through AI without losing its competitive advantage?
- WALLIX: Will the management of identities and privileged access become a key component of secure AI agents?
- Siemens: Can industrial AI be transitioned from pilot projects into the day-to-day operations of factories?
These are three distinct approaches—specialized software, cybersecurity, and industrial automation. They allow us to examine the second wave of AI from various perspectives.
For me, the next step is to systematically analyze these Depot 2036 companies based on four criteria: current AI revenue, additional revenue potential, competitive moat, and valuation.
After all, we’re not just looking for companies that talk about AI.
We’re looking for companies that can turn AI into a sustainably profitable business model.
My dear readers, my thanks go out to everyone who stuck with it and read to the end.
I’d appreciate lots of likes and comments.
Feel free to join us in discussing the second wave as well.