

$US60855R1005 (-2,06 %) Does it make sense to start now?

Molina Health
Stock
Stock
Price
Debate sobre Molina Health
Puestos
11

9Lun·
🚨 These are not "random safe stocks". These are deliberately sought-after mispricings.
I was looking for names that are:
- lagging behind the overall market
- strongly undervalued
- still fundamentally strong
- and are sitting on perfect charts that are on the verge of breakouts
If capital is reallocated defensively, these stocks are positioned to do just that.👇
$JD (-3,89 %) - JD.com 🛒
Business overview 🧬
One of China's largest e-commerce and logistics platforms with nationwide delivery service and strong presence in Chinese consumer behavior.
Basics 🧾
- Trading at approx. 46.9% below the estimated fair value
- Price-to-sales ratio ≈ 0.24 - heavily discounted
- Profit forecast: ~14.4% growth per year
- China is lagging behind the US - and JD is lagging behind China → a major divergence is emerging.
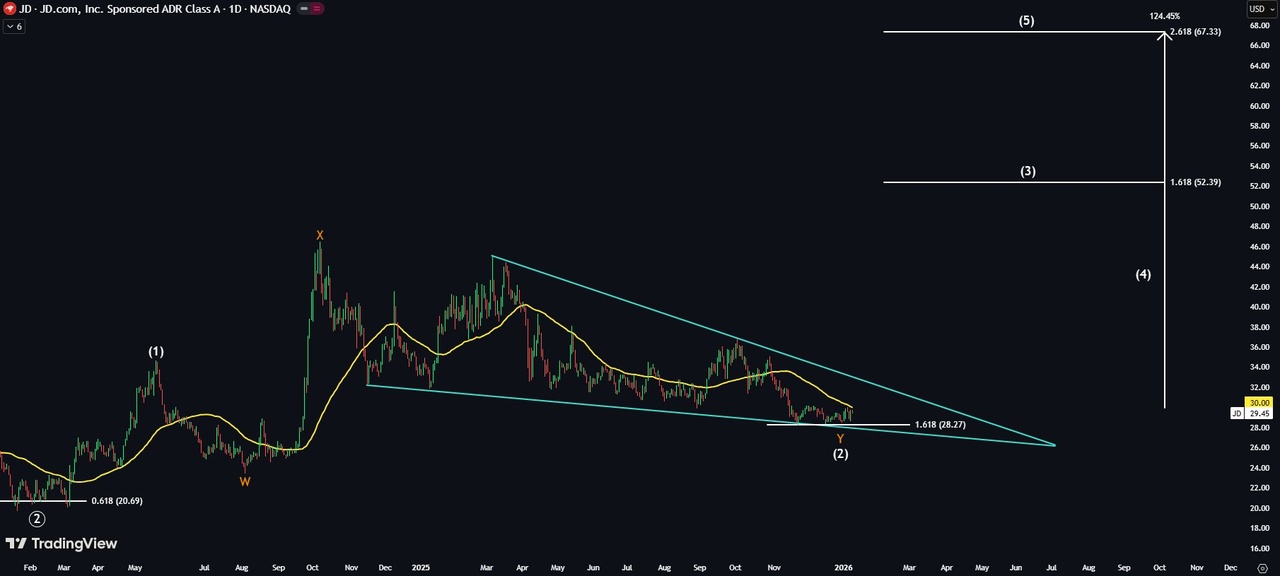
Diagram 📊
- Wave 2 just completed
- Consolidation in a descending wedge
- Currently actively accumulating, with a safer entry point when the 50-day moving average turns to support.
- Target of wave 5 = ~124 % upside potential
Conclusion 💡
This is what mispricing looks like.
Value is extremely high. The growth is real.
$US60855R1005 (-2,06 %) - Molina Healthcare 🏥
Business overview 🧬
US provider of managed care programs for low-income families through Medicaid, Medicare and state marketplaces - a major beneficiary of ACA subsidies.
Basics 🧾
- ~77% below fair value
- Earnings growth ~9.6%/year
- Non-cyclical demand
- Revenue backed by government programs
- Michael Burry is long
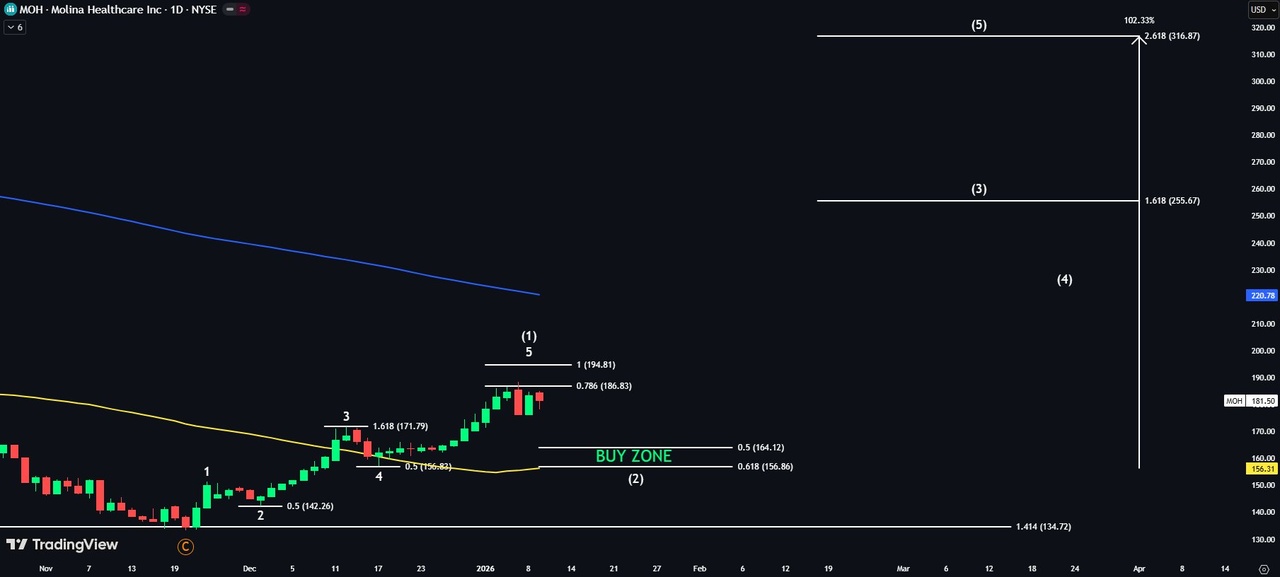
Chart 📊
- ~68% below the all-time high
- Second wave support at 200-MMA
- Watching the second sub-wave near the 50-day line.
- Monthly RSI ~37
Conclusion 💡
High value + demand supported by the Affordable Care Act (ACA).
Built to withstand changing pressures.
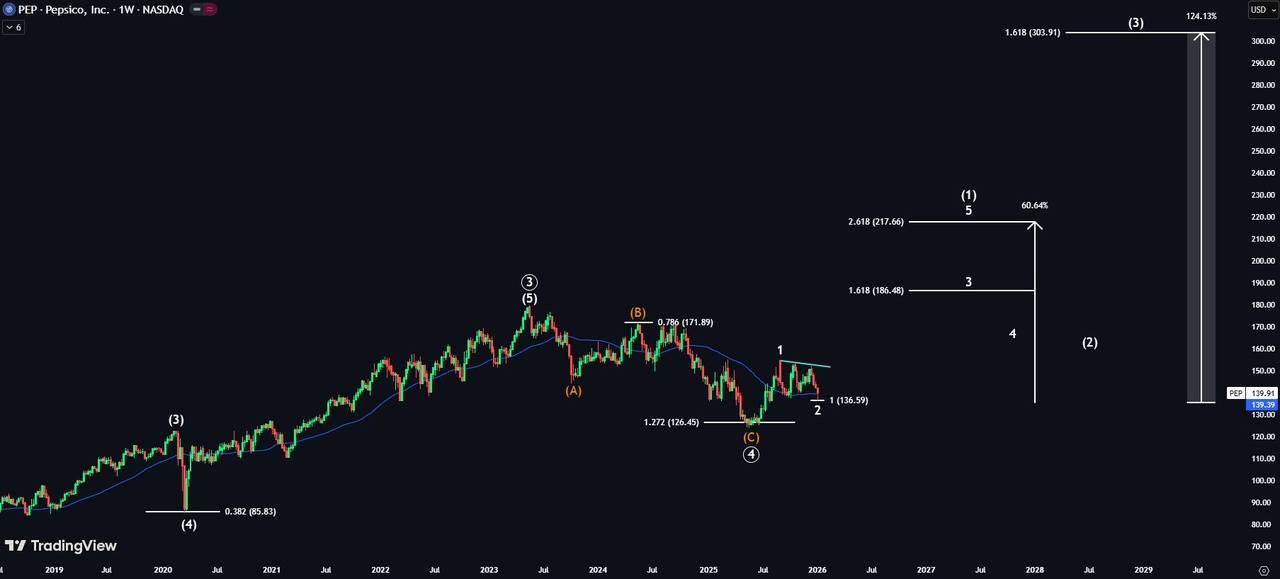
$PEP (+0,13 %) - PepsiCo 🥤
Business overview 🧬
Global food and beverage giant with brands like Pepsi, Gatorade, Lay's and Doritos - staples that people buy regardless of the economy.
Basics 🧾
- Trading around 43.3% below estimated fair value
- Profits are expected to increase by around 11.1 % per year
- Around 23% below all-time high and lags the broader US market.
- Pays a dividend of approx. 4 %
Chart 📊
- In wave 1 within a primary wave 5
- Sub-wave 2 found support in the 200 DMA area.
- Position A ★ is accumulated here, with a safer entry point on a trendline break.
- The short-term structure indicates an upside potential of approx. 60 % - definitely achievable this year.
Conclusion 💡
Undervalued, defensive and paid to wait.
Exactly what I want for the late 2026-27 cycle.
Which undervalued, defensive stocks are you currently watching for the late cycle phase?
👉 Do you prefer value + cash flow or are you still waiting for lower entries?
👇 Looking forward to your takes.


9Lun·
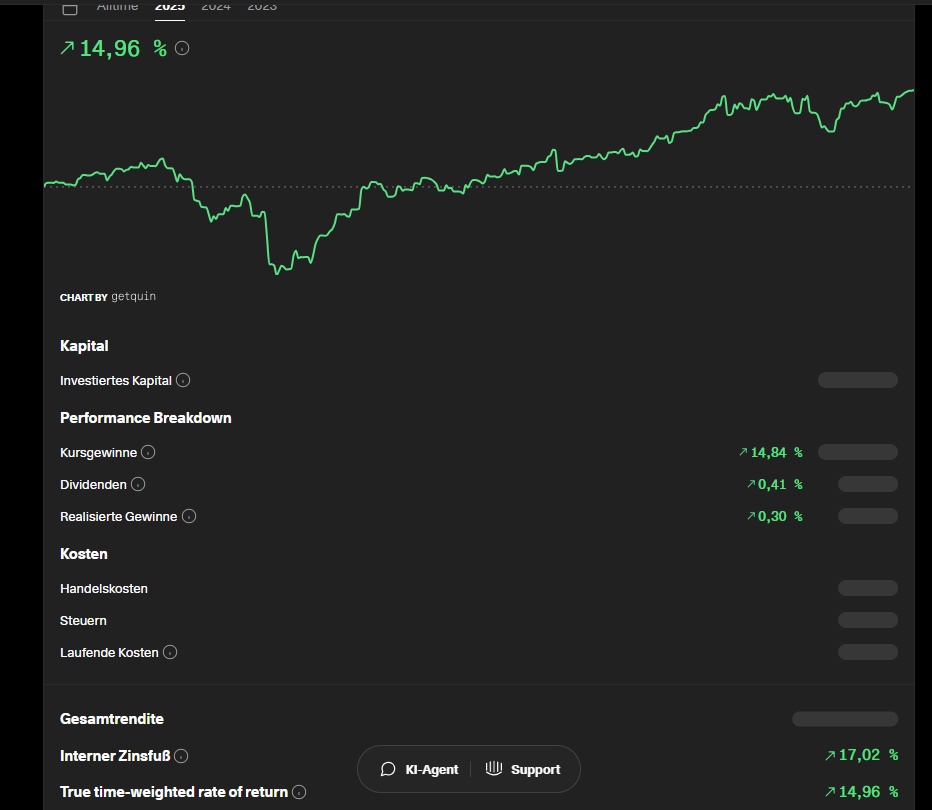
Performance 2025
Hello everyone,
I would like to wish everyone a happy holiday and a happy new year.
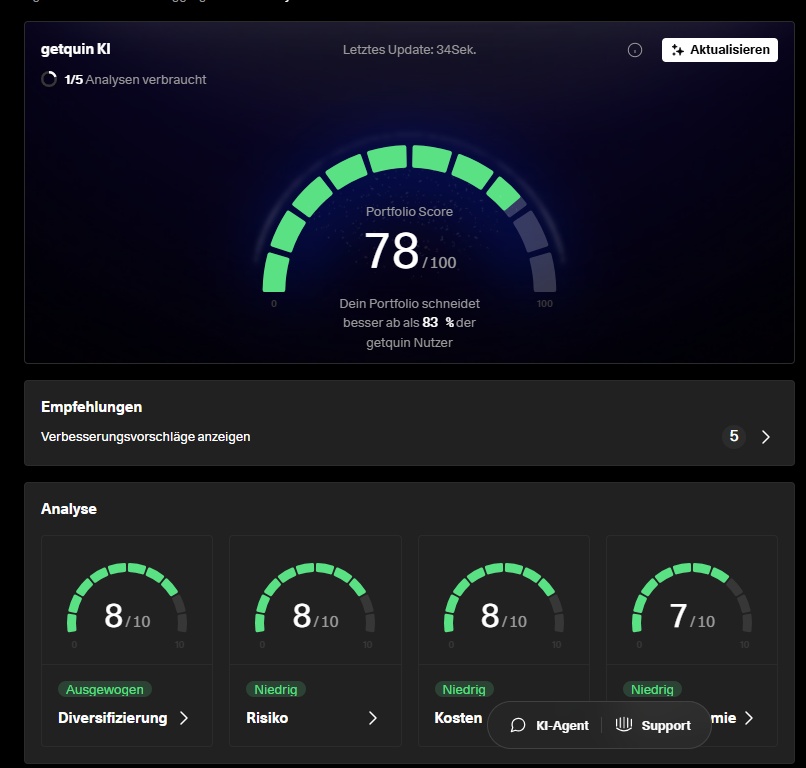
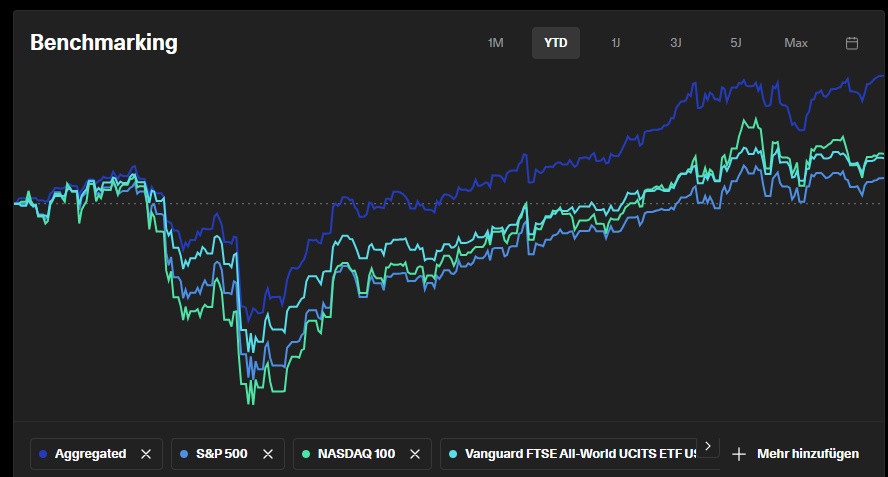
Here is my annual performance, which I am satisfied with, not only because of the return I achieved - some have achieved far more - but also because I was able to reduce my drawdown compared to my "comparison benchmarks".
I thought my 3 best stocks would be the ones I bought in the "Trump Crash". But the 3 best were the ones I bought before and simply held:
And also the ones I bought after the big carnage did well
However, the following did not go well at all
The surprise of the year for me was silver, which of course benefited my portfolio.
Best regards
1616

11Lun·
UnitedHealth Group Q3'25 Earning Highlights 🫡
- Revenue: $113.2B (Est. $113.156B) ✅; +12% YoY
- Adj EPS: $2.92 (Est. $2.84) ✅
- Earnings from Operations: $4.3B; -50% YoY
Raises FY25 Guidance:
- Adj EPS: at least $16.25 (Est. $16.22) ✅
- GAAP EPS: at least $14.90
Q3 UnitedHealthcare (Benefits):
- Revenue: $87.1B (Est. $86.72B) ✅; UP +16% YoY
- Operating Margin: 2.1%
- Consumers Served (U.S.): 50.1M; +795k YoY
Q3 Optum (Health Services)
- Revenue: $69.2B (Est. $67.52B) ✅; UP +8% YoY
- Optum Health Revenue: $25.9B; flat YoY
- Optum Insight Revenue: $4.9B; flat YoY
- Optum Rx Revenue: $39.7B; UP +16% YoY
- Optum Rx Adjusted Scripts: 414M (407M last year)
Other Metrics:
- Operating Cash Flow: $5.9B
- Medical Care Ratio (MCR): 89.9% (85.2% a year ago)
- Operating Cost Ratio: 13.5% (13.2% a year ago)
- Net Margin: 2.1%
- Debt-to-Capital Ratio (9/30/25): 44.1%
Comment:
🔸 "We remain focused on strengthening our performance and positioning for sustained and accelerated growth in 2026 and beyond, and our results this quarter reflect the solid execution of this objective."
🔸 Amedisys transaction completed on August 14, 2025; ongoing investments to support future growth.
$CVS (-0,59 %)
$ELV (-0,04 %)
$US60855R1005 (-2,06 %)
$OSCR (-0,2 %)
$CI (+0,13 %)
3535

11Lun·
Molina Healthcare earnings
Molina Healthcare $US60855R1005 (-2,06 %) is a managed care company that reported its third-quarter results for the calendar year 2025, reflecting a mixed performance that has drawn significant attention from investors and analysts. The company reported total revenues of $11.48 billion for Q3 2025, representing an 11% year-over-year increase, and notably exceeding analyst expectations of approximately $10.94 billion. This revenue growth was driven by both organic expansion and acquisitions, reflecting Molina’s steady growth in its core government-sponsored insurance programs, including Medicaid, Medicare, and the state insurance Marketplaces.
Despite the solid top-line growth, Molina’s profitability fell short of expectations. The company's adjusted earnings per share (EPS) were $1.84, which missed analyst forecasts by over 50%, as the consensus estimate had been approximately $3.91 per share. Similarly, the company’s adjusted EBITDA fell significantly short of expectations, registering about $179 million, less than half of the $346 million anticipated. This large earnings miss has been attributed primarily to rising medical care costs — particularly within the Marketplace segment — which caused the company’s Medical Care Ratio (MCR), the percentage of premiums spent on medical expenses, to rise to an elevated 92.6% for the quarter, up from 89.2% the previous year. The Marketplace segment’s MCR surged sharply to 95.6%, compared to just 73% a year ago, signaling increasing pressure on margins in this area.
Molina Healthcare serves approximately 5.6 million members as of September 2025, reflecting modest growth, with Marketplace membership showing more notable expansion to 713,000, compared to 410,000 members a year earlier. The company continues to focus on expanding its footprint, pursuing new state contracts and retention efforts to drive membership growth in Medicaid and Medicare segments, which remain more stable and profitable compared to the Marketplace.
In response to the higher-than-expected costs and earnings shortfall, Molina lowered its full-year 2025 adjusted earnings guidance to approximately $14 per share from a previous forecast close to $18.6 per share, representing a decline of roughly 26%. However, the company revised upward its revenue guidance slightly to about $44.5 billion, reflecting continued growth in premium revenue. Management’s outlook for 2026 suggests earnings will approximate 2025’s revised guidance, with expectations for the Marketplace segment to reduce its losses and possibly break even, thereby alleviating some pressure on overall profitability.
Molina Healthcare is navigating a challenging environment marked by increasing healthcare costs and regulatory complexities. The company’s strategic focus remains on maintaining strong medical care ratio management and administrative expense controls to protect margins, alongside pursuing growth initiatives through organic and inorganic strategies. While the current quarter’s results and lowered guidance weigh on investor sentiment, Molina’s strong presence in government-sponsored health insurance programs and its disciplined approach to cost management offer a foundation for potential recovery.
The market responded swiftly to the Q3 earnings announcement, with Molina’s stock price plunging around 18-20% in after-hours trading, reflecting investor concerns over margin pressures and ongoing cost inflation. Despite this immediate setback, the stock appears undervalued based on fundamental metrics, with a price-to-earnings ratio of about 7.7x and analyst price targets suggesting significant upside potential, indicating that the market may be pricing in short-term risks but recognizing the longer-term growth opportunities.
In summary, Molina Healthcare’s third-quarter 2025 performance highlights both the company’s growth capability in government-sponsored healthcare markets and the serious challenges it faces from medical cost inflation, particularly in the Marketplace segment. Investors should carefully weigh the short-term margin pressures against Molina’s strong market position, membership growth, and management’s commitment to returning to more sustainable profitability in the coming years. The company’s ability to control medical care costs and stabilize profitability will be key to restoring confidence and achieving the growth trajectory projected by analysts.
https://www.sec.gov/Archives/edgar/data/1179929/000117992925000125/moh-20251022.htm
11
1Año·
United Health
$UNH (-0,7 %)
$CNC (-0,53 %)
$US60855R1005 (-2,06 %)
$ELV (-0,04 %)
$CVS (-0,59 %)
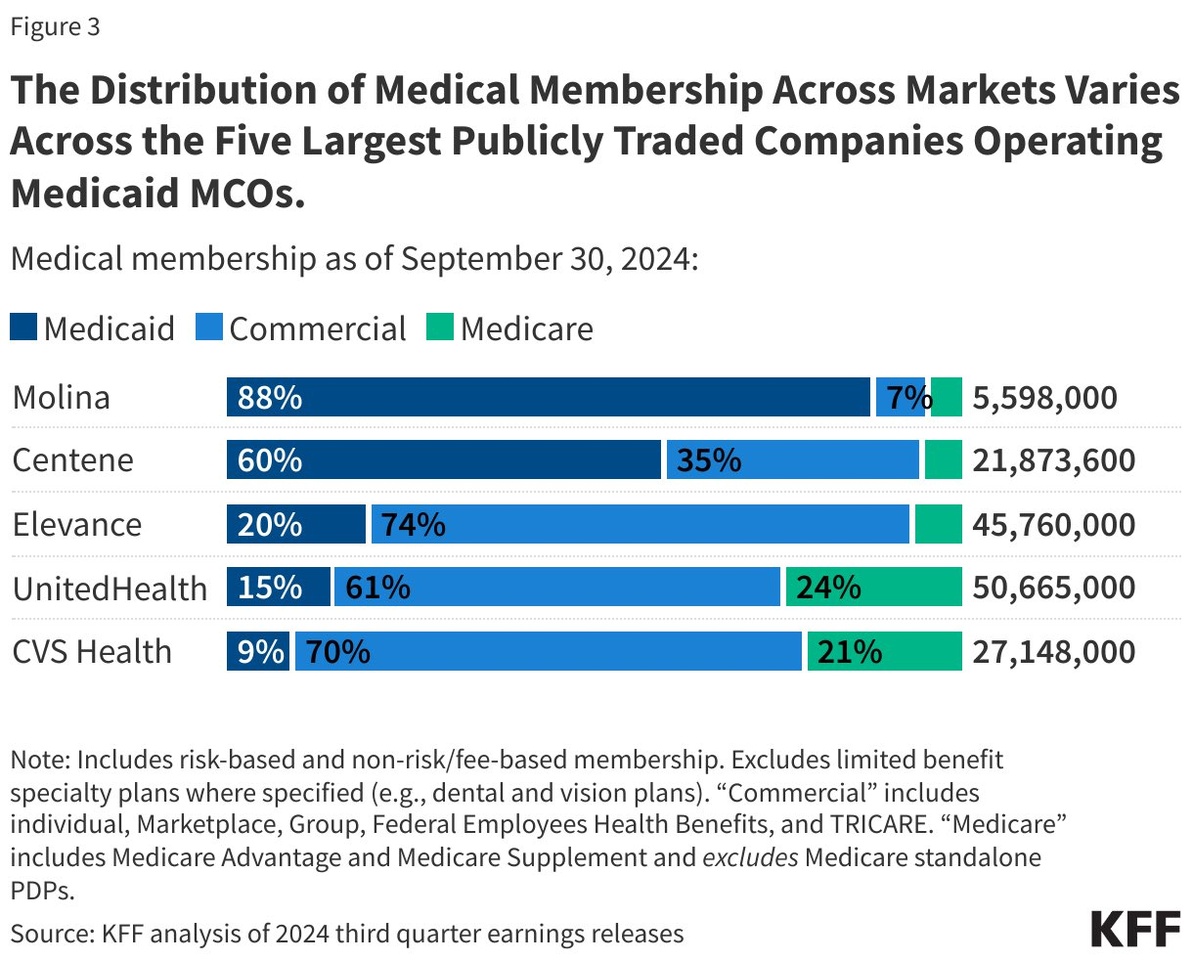
How the loss of $CNC (-0,53 %) and $US60855R1005 (-2,06 %) shows, Medicaid is charity care because you lose money when you care for the sickest and poorest population. To make a profit, you want as few Medicaid patients as possible.
$UNH (-0,7 %) is in a better position ✌️
1Año·
Centene Q2'25 result highlights
Next sale in the health insurance sector ?
🔹 Revenue: USD 48.74 billion (estimated USD 44.24 billion) ✅
🔹 Adjusted earnings per share: ( USD 0.16) (estimated USD 0.23) ❌
🔹 Health insurance ratio: 93.0% (estimated 91.6%) ❌ ; increase of +5.4 percentage points compared to the previous year
🔹 Total income from premiums and services: USD 42.47 billion; increase of 18% compared to the previous year
🔹 Selling and administrative expenses ratio: 7.1 %
Segment revenue:
🔹 Medicaid: USD 21.72 billion; increase of 7% compared to the previous year
Commercial: USD 10.07 billion; increase of 18% compared to the previous year
🔹 Medicare: USD 9.45 billion; increase of 58% compared to the previous year
🔹 Other: USD 1.22 billion; increase of 1% compared to the previous year
Other metrics
🔹 Cash flow from operating activities: USD 1.79 billion
🔹 Payability days for claims: 47 days
CEO comment:
➡️ "We are disappointed with our second quarter results, but have a clear understanding of the trends that impacted our performance and are working diligently and with focus to restore our earnings performance." - Sarah M. London
➡️ "Despite the changing landscape, we believe the staying power of Medicaid, Medicare and the Individual Marketplace is stronger than ever." - Sarah M. London
$UNH (-0,7 %)
$US60855R1005 (-2,06 %)
$CVS (-0,59 %)
$CI (+0,13 %)
$XDWH (-0,39 %)

1Año·
Centene Q2'25 result highlights
Next sale in the health insurance sector ?
🔹 Revenue: USD 48.74 billion (estimated USD 44.24 billion) ✅
🔹 Adjusted earnings per share: ( USD 0.16) (estimated USD 0.23) ❌
🔹 Health insurance ratio: 93.0% (estimated 91.6%) ❌ ; increase of +5.4 percentage points compared to the previous year
🔹 Total income from premiums and services: USD 42.47 billion; increase of 18% compared to the previous year
🔹 Selling and administrative expenses ratio: 7.1 %
Segment revenue:
🔹 Medicaid: USD 21.72 billion; increase of 7% compared to the previous year
Commercial: USD 10.07 billion; increase of 18% compared to the previous year
🔹 Medicare: USD 9.45 billion; increase of 58% compared to the previous year
🔹 Other: USD 1.22 billion; increase of 1% compared to the previous year
Other metrics
🔹 Cash flow from operating activities: USD 1.79 billion
🔹 Payability days for claims: 47 days
CEO comment:
➡️ "We are disappointed with our second quarter results, but have a clear understanding of the trends that impacted our performance and are working diligently and with focus to restore our earnings performance." - Sarah M. London
➡️ "Despite the changing landscape, we believe the staying power of Medicaid, Medicare and the Individual Marketplace is stronger than ever." - Sarah M. London
$UNH (-0,7 %)
$US60855R1005 (-2,06 %)
$CVS (-0,59 %)
$CI (+0,13 %)
$XDWH (-0,39 %)
1Año·
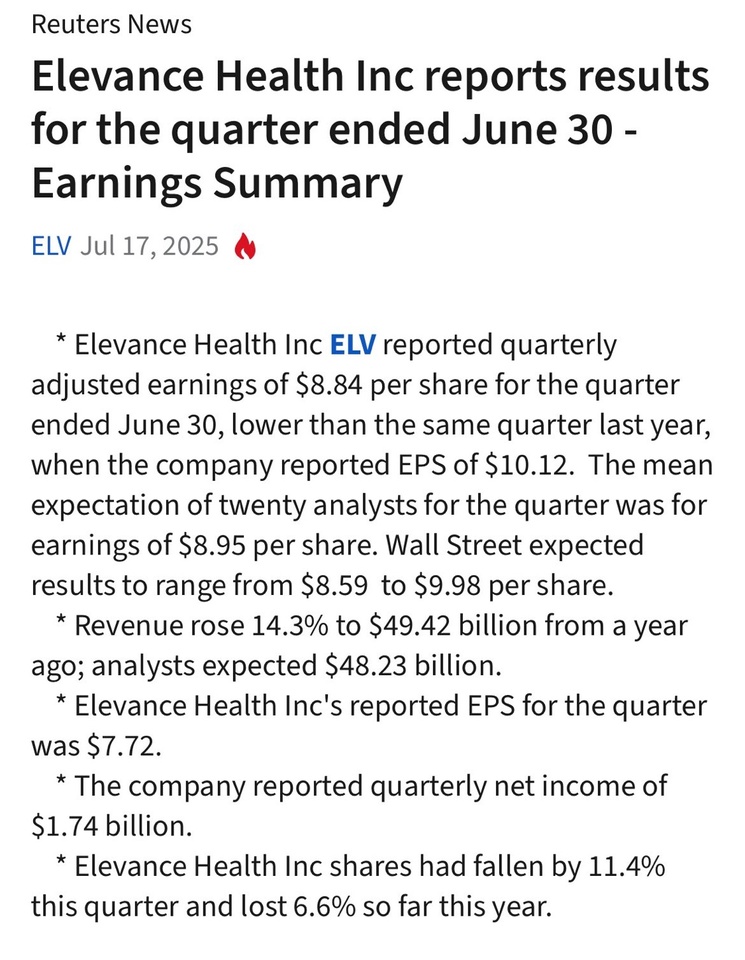
Elevance Health Q2 '25 Earnings Highlights
- EPS: $8.84 vs $9.07 expected ❌
- Revenue: $49.4 billion vs $48.14 billion expected ✅
- FY25 EPS guidance: $30.00 vs $34.48 consensus ❌
- Benefit cost ratio: 88.9%; increase of +260 basis points compared to the previous year
- Operating expense ratio: 10.1 %; decrease of -160 basis points compared to the previous year
The second-largest health insurer reported its profits. Although these were below consensus, they were not too bad given the panic in the industry.
The benefit cost ratio was 88.9%, an increase of 260 basis points from the previous year, reflecting the trend toward higher medical costs, particularly in the Medicaid business and ACA health plans.
CEO Comment:
- "In the second quarter, Elevance Health made significant progress in delivering a simple and personalized experience for our customers while advancing our efforts to improve efficiencies across the health system ... With the embedded earnings power of our diversified Health Benefits and Carelon businesses, we remain confident in our ability to deliver at least 12% compound annual growth in adjusted diluted earnings per share over time." - Gail K. Boudreaux
$UNH (-0,7 %)
$CNC (-0,53 %)
$US60855R1005 (-2,06 %)
$CVS (-0,59 %)
$OSCR (-0,2 %)
1Año·
Further increased
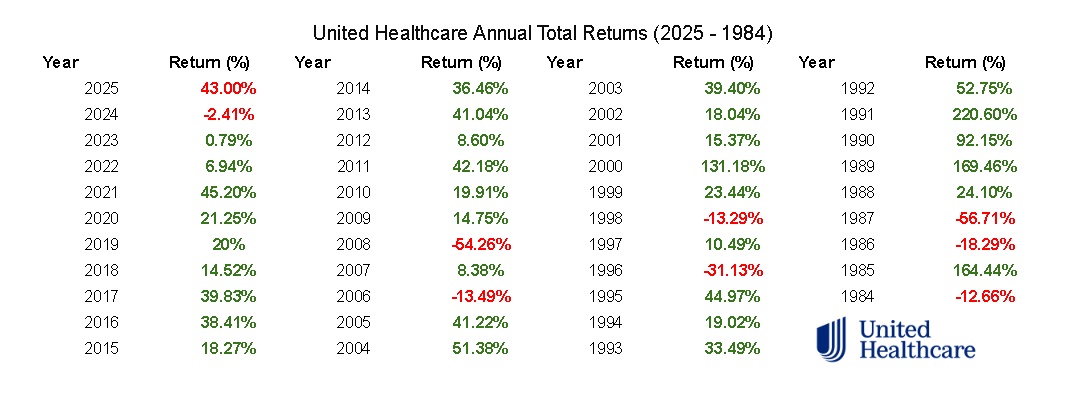
$UNH (-0,7 %) has not experienced two consecutive years of negative returns since 1987.
Who is still invested here, who is buying, what are your assessments? 🤔
In my opinion, a lot of negative things are already priced in here.
- There is no evidence for the accusations
- Every accusation is contradicted and more openness is also suggested
- They are regularly reviewed and nothing negative has been found
- Bad "old" news is constantly being rehashed which has already been dismissed as unfounded and unproven
- CEO and other insiders have set an example by buying it
- $UNH (-0,7 %) is one of the largest employers in the US and also system relevant
- Medicare/Medicaid accounts for only 15% of revenue
- Outlook/expectations have already been reduced
- Historically high dividend yield of just under 3%
- Possible penalties already priced in in my opinion
yes, of course there is still downside potential, but the risk/reward ratio is already very attractive
The entire sector has similar ways of working and a decline/reduction in Medicare could $UNH (-0,7 %) as the top dog in the private sector could even play into its hands.
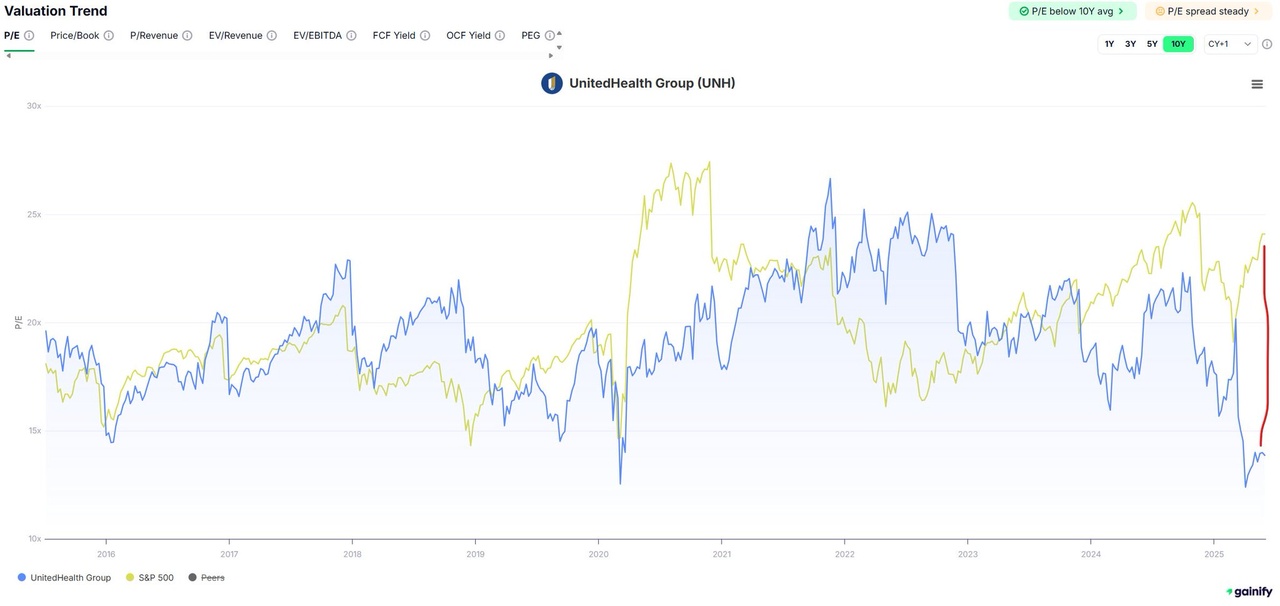
UnitedHealth Group $UNH (-0,7 %) has traded at the largest deviation from the S&P 500 price-to-earnings ratio since its IPO ...
This stock has literally NEVER been this cheap relative to the S&P 500.
Incredibly exciting to follow the story.
$CNC (-0,53 %)
$CVS (-0,59 %)
$OSCR (-0,2 %)
$HUM (-0,16 %)
$CI (+0,13 %)
$ELV (-0,04 %)
$XDWH (-0,39 %)
88
17 Comentarios
1Año
How many shares are you up to now? There should already be a lot of skin in the game. 😁
EDIT: At UNH, of course.
EDIT: At UNH, of course.
•
11
•1Año·
Percentage of income from Medicare:
Molina $US60855R1005 (-2,06 %) - 80 %
Centene $CNC (-0,53 %) - 52 %
Elevance $ELV (-0,04 %) - 25 %
UnitedHealth $UNH (-0,7 %) - 11 %
CVS Health (Aetna) $CVS (-0,59 %) - 6 %
Companies that in my opinion have upside potential on positive news.
Healthcare sector in general with a lot of catch-up potential, can in my opinion be well overplayed. $XDWH (-0,39 %) play.
Do you have any sectors that you play via ETFs and if so, which ones?
I would be interested, I will probably now also set up a savings plan on $DAPP (+4,09 %) and make a first purchase.
- Expansion of the money supply
- Possible fall in interest rates
- Debt of the USA (repayment 1/3 this year)
- and much more
In my opinion, this should $BTC (+2,04 %) and a large part of the associated companies.
(Even if we are already somewhat further advanced)
Looking forward to your opinions and sector ETF's, even if they are only short term positions.
Normally I only go for individual stocks, but as I hardly want to hold cash, I feel very comfortable in the healthcare sector at the moment. ✌️
88
16 Comentarios
1Año
not related to the topic, but what spoke for you in the massive sell-off for $ELF? there were already a lot of negative things coming together
••

2Año·
$MOH (-2,06 %) I know that maybe this company is little known but I want to tell you to prepare a cup of tea and go and see its balance sheet, it's worth it.
