

Yesterday, Aker paid a dividend ( $AKER (-2,19 %) ), so today I took advantage of the dip to pick up a few more shares at a good price. I’d like to reach 45 shares by the end of the year -> I still need 12 more. -> For those who are interested: a 5.4% dividend at the current price (though subject to Norwegian withholding tax). 🙂

Aker
Stock
Stock
ISIN: NO0010234552
Ticker: AKER
NO0010234552
AKER
Price
Debate sobre AKER
Puestos
8


2Semana·
𝐀𝐤𝐞𝐫 𝐀𝐒𝐀 𝐐𝟑 𝟐𝟎𝟐𝟔: 𝐑𝐞𝐜𝐨𝐫𝐝 𝐍𝐀𝐕 𝐨𝐟 𝐍𝐎𝐊 𝟏𝟏𝟏𝐁, 𝐍𝐬𝐜𝐚𝐥𝐞 𝐄𝐦𝐞𝐫𝐠𝐞𝐬 𝐚𝐬 𝐒𝐞𝐜𝐨𝐧𝐝-𝐋𝐚𝐫𝐠𝐞𝐬𝐭 𝐀𝐬𝐬
⠀
📊 𝐑𝐞𝐬𝐮𝐥𝐭𝐬
• Net Asset Value (NAV): NOK 111.2B (+5% QoQ; +65% YTD)
• NAV per Share: NOK 1,509 vs. NOK 1,429 QoQ
• NAV per Share (Nov. 3): NOK 1,550
• Gross Asset Value: NOK 127.5B
• Share Price (Nov. 3): NOK 1,120 (~28% discount to NAV)
• Net Interest-Bearing Debt: NOK 13.8B
• Net Loan-to-Value: 12%
• Liquidity Reserve: NOK 4.8B
• YTD NAV Return: +68.6% including dividends
• YTD Shareholder Return: +83.5% through Q3
⠀
🎯 𝐃𝐢𝐯𝐢𝐝𝐞𝐧𝐝𝐬 & 𝐎𝐮𝐭𝐥𝐨𝐨𝐤
• Q4 Dividend: NOK 29/share (~NOK 2.2B total)
• Annual Dividend Policy: 4%–6% of NAV
• Expected FY26 Dividend Income: >NOK 6B
• Cognite Sale: USD 1.48B in proceeds expected upon Q4 closing
⠀
📌 𝐊𝐞𝐲 𝐓𝐚𝐤𝐞𝐚𝐰𝐚𝐲𝐬
• Nscale valued at NOK 32.1B, representing 25% of Aker’s gross asset value and based on its March 2026 Series C valuation
• Aker holds 22.7% of Nscale, subject to potential future dilution from convertible financing, incentives and IPO-related transactions
• Nscale filed its S-1 for a proposed NYSE IPO
• Nscale reports ~$103B in total contract value, ~461,000 contracted and active GPUs, and visibility into 10GW+ of potential power capacity
• ~360,000 GPUs are NVIDIA Vera Rubin; ~48,000 of ~50,000 active GPUs are Grace Blackwell
• Nscale secured a $44.6B Anthropic contract and a $3.5B Figure agreement
• Nscale raised $3.36B in pre-IPO convertible financing and agreed to acquire Anyscale
• Aker BP contributed NOK 5.8B to Q3 NAV growth including dividends
• Aker BP production reached 374,300 boe/day, with Valhall PWP-Fenris and Yggdrasil targeting first oil in 2027
• Cognite sale to Schneider Electric values Aker’s stake at ~NOK 14.7B
• Aker BioMarine take-private completed October 1, bringing ownership to 100%
• Listed energy investments contributed NOK 22B to NAV growth YTD, including NOK 5B in dividends
• Nscale’s valuation remains based on its last priced funding round, not a public-market valuation
⠀
💬 𝐌𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 𝐂𝐨𝐦𝐦𝐞𝐧𝐭𝐚𝐫𝐲
“Rapid growth brings substantial capital requirements, operational complexity and execution risk. Building an industrial platform of this scale takes time, and the path forward will not always be straightforward.” — CEO Øyvind Eriksen
44

1Lun·
Gas Station with a Data Center
$AKER (-2,19 %) - I added my first position in Aker to my portfolio today.
Aker is a Norwegian industrial holding company with deep roots in offshore oil production; however, after various forays into wind power, hydrogen, and CO2 capture (most of these businesses have since been divested or spun off into joint ventures), it is now also a data center operator.
First, the current figures, which sound very promising to me: P/E ratio = approx. 3.5 (!), dividend yield = approx. 4%.
The stock price just experienced a slight dip, which I see as a buying opportunity to finally move the company from my “watchlist” to my “portfolio.”
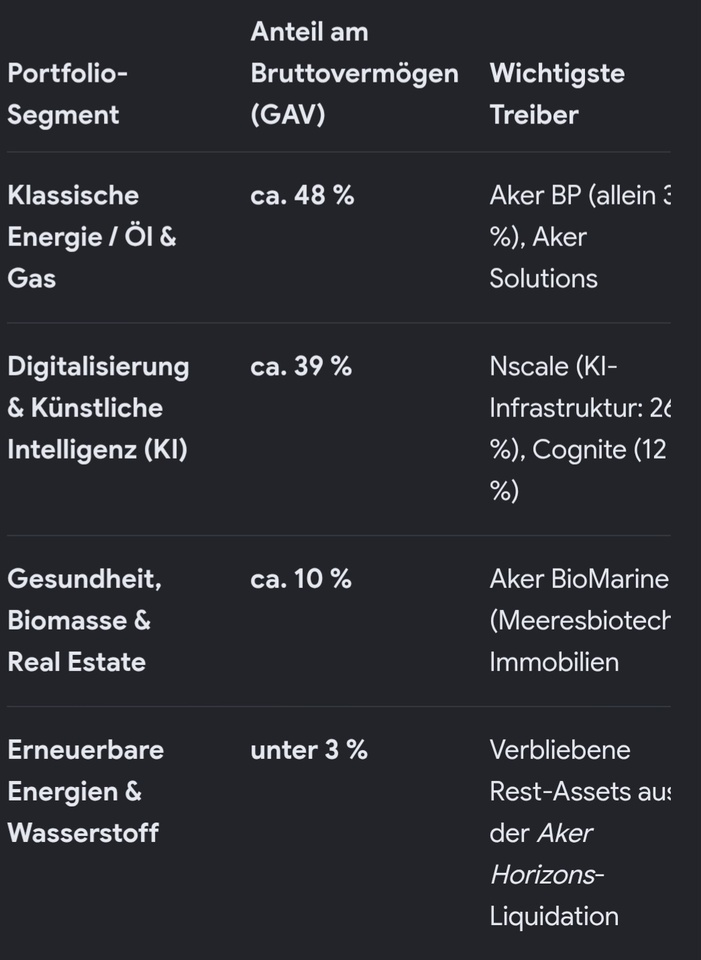
Here is a table showing the breakdown of the business segments:
1717
7 Comentarios
1Lun
Aker ASA, a Norwegian industrial holding company with stakes in Aker BP, Aker Solutions, Cognite, Aker BioMarine, and others, is currently very attractively valued on a fundamental basis, but the stock price is technically overheated following an extreme rally. I would be cautious about new purchases; for existing shareholders, there are strong arguments for partial sales or, at the very least, adding to positions only during a correction.
Aker is not a traditional oil company, but rather an actively managed investment company focused on energy, offshore, green technologies, industrial software, and marine biotechnology. Valuation should therefore be based primarily on NAV, dividends, and portfolio performance—the traditional P/E ratio is of limited use here.
NAV Valuation
This is the most important valuation benchmark:
NAV at the end of 2025: 67.26 billion NOK, or 905 NOK per share.
NAV for H1 2026: approximately 106 billion NOK after dividends, an increase of nearly 40 billion NOK.
Current share price: approx. 1,290 NOK.
Price-to-NAV ratio: around 1.43 based on the H1 2026 NAV, assuming the NAV is roughly divided by the number of shares.
This means that Aker is no longer trading at a traditional holding company discount, but rather at a premium to NAV. This is only justified if investors continue to expect strong value growth from companies such as Nscale, Cognite, Aker BP, or other portfolio companies.
Aker is not a traditional oil company, but rather an actively managed investment company focused on energy, offshore, green technologies, industrial software, and marine biotechnology. Valuation should therefore be based primarily on NAV, dividends, and portfolio performance—the traditional P/E ratio is of limited use here.
NAV Valuation
This is the most important valuation benchmark:
NAV at the end of 2025: 67.26 billion NOK, or 905 NOK per share.
NAV for H1 2026: approximately 106 billion NOK after dividends, an increase of nearly 40 billion NOK.
Current share price: approx. 1,290 NOK.
Price-to-NAV ratio: around 1.43 based on the H1 2026 NAV, assuming the NAV is roughly divided by the number of shares.
This means that Aker is no longer trading at a traditional holding company discount, but rather at a premium to NAV. This is only justified if investors continue to expect strong value growth from companies such as Nscale, Cognite, Aker BP, or other portfolio companies.
•
33
•

2Año·
Commodity shortages loom: "Good for investors, bad for the rest" / Which shares are worthwhile
Ok, the headline is a bit sensational. But cool interview from a René.
Among other things, it's about the commodities uranium lithium silver and copper
https://youtu.be/YbebkkKcdS4?si=ZkUYJDr4ApFfILBP
"The outlook for commodities seems good, as far too little has been invested in recent years. However, commodities as an asset class are not quite so simple and there can be nasty surprises. I spoke to Urs Marti, manager of the SIA Long Term Investment Fund Natural Resources, about what is important. I have to say: I've rarely had a guest talk to me in such a humorous way. And welcome to "Rene wants returns"!
Important points:
00:00 What can be learned from the price slump in lithium
05:56 The fluctuations in commodities
07:44 Too little has been invested and that will take its toll
09:45 The fatal impact of ESG on commodities
10:29 Is a commodity shortage looming in the next few years?
11:29 Four percent of production is lost every year
13:23 What could happen next with oil
14:04 The mistakes of the energy transition in Germany: the nuclear phase-out was the lignite phase-in
14:51 Switzerland is doing good business with cheap German electricity
15:49 The price of uranium has risen sharply - will it keep going up?
21:27 Where Urs Marti now sees opportunities
23:33 Not on the marketing straight at
commodities
25:18 Be careful with silver mines
26:30 What to consider when investing in
commodity companies 34:20 Politics is the problem with big companies
companies
35:21 European oil companies on the wrong track $SHEL (+0,11 %)
$TTE (-1,67 %)
36:17 Stocks that Urs Marti likes:
36:20 Glencore $GLEN (-3,32 %)
36:54 Harbour Energy and Aker $AKER (-2,19 %)
39:44 Cenovus $CVE (-0,52 %)
www.youtube.comRohstoffknappheit droht: "Gut für Anleger, schlecht für den Rest" / Welche Aktien sich lohnen
22
1 Comentario
2Año
I took the time to watch the video and agree with the main points of the opinion.
However, I don't understand why a manager of a fund would supposedly blame politics.
Politics sets the framework in which a market economy company operates. It goes without saying that companies have to adapt to this.
However, it is up to the individual management to decide whether the transformation is successful. In this respect, the blame should be placed less on politics and more on the management of the respective companies.
However, I don't understand why a manager of a fund would supposedly blame politics.
Politics sets the framework in which a market economy company operates. It goes without saying that companies have to adapt to this.
However, it is up to the individual management to decide whether the transformation is successful. In this respect, the blame should be placed less on politics and more on the management of the respective companies.
•
33
•
3Año·
I am continuing my search for potential stocks for the Tenbagger portfolio after Lynch. As it has been very US-heavy so far - strictly speaking, I have only invested in US stocks in this context so far - I have focused on the EU for the next stock. The search is not easy. There also seem to be certain sectors in which Lynch's criteria are simply standard for the industry, such as the paper industry. A more precise assessment of the individual values is therefore still necessary in a further step. However, the following companies have now been shortlisted:
- $AKER (-2,19 %)
- $BILL (-1,24 %)
- $BOL (-3,72 %)
- $CEM (-0,86 %)
- $KMR (+2,43 %)
- $PFV (+0,25 %)
- $TESB (-2,56 %)
- $TRI (-2,12 %)
- $WCH (-6,3 %)
What do you think? Do you think one share is particularly interesting? 🤔
-
I have explained more about Lynch's tenbagger strategy in this article:
https://www.patreon.com/posts/64094946?utm_campaign=postshare_creator
33
5 Comentarios
I would rather be in favor of Aker, as they invest broadly in an industry that is fit for the future. :)
•
11
•
4Año·
Aker ASA
Almost a year ago, some here discovered "Aker Carbon Capture". The largest shareholder, Aker Horizons, is still invested in a few other companies and in turn owns 76% of Aker ASA😵 Maybe you can find similar interesting companies and businesses there? Or is Aker Horizons even THE investment in renewable energies?
This is the introductory post in a series looking at the companies within Aker ASA holdings. Aker has MANY investments in several other companies and businesses. I will break down and analyze the largest and most exciting of these into individual posts.
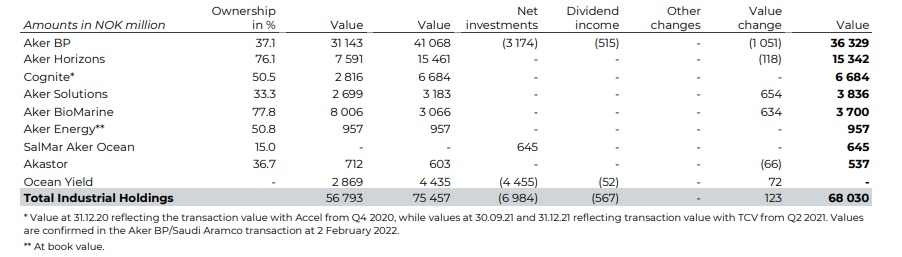
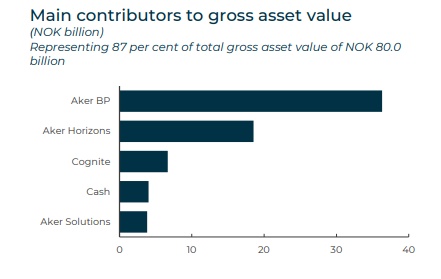
Industrial Holdings make up 85% of Aker investments; the largest are:
Aker BP ( $AKRBP (-1,63 %)
)
ownerhship: 37.1%
Oil and gas industry. Exploration and production of oil and gas offshore.
Value 2021 in NOK million: 36.329
[insert contribution here]
Aker Horizons ( $AKH )
https://www.akerhorizons.com/portfolio
ownership: 76.1%
Aker Horizons is Aker's investment in renewable energy and green technologies. This includes the following companies, for example:
Aker Carbon capture/ Mainstream renewable power/ Aker offshore wind/ Supernode
Value 2021 in NOK million: 15.342
[insert post here]
Cognite
ownership: 50.5%
Software company providing software and internet-of-things services to industrial companies.
Value in 2021 in NOK million: 6.684
Aker Solution ( $AKSO (-3,76 %) )/ Aker BioMarine/ Aker Energy
Ownership: 33.3%/ 77.8%/ 50.8%
https://www.akersolutions.com/who-we-are/
https://www.akerbiomarine.com/who-we-are
https://www.akerenergy.com/who-we-are
combined value 2021 in NOK million: approx. 8,500
In addition, there are/have been investments in other companies (see chart); furthermore, the remaining share of assets (15%) is in the financial area (annual report 2021 page 10).
Market capitalization Aker ASA ( $AKER (-2,19 %) ) : US $ 5.5 billion
with a profit before tax (2021) of approx. 1.2 billion US $
Assessment of this valuation comes after the individual analyses.
To read:
https://www.akerasa.com/en/investors/financial-reports-presentations
@KapriolenSonne
@RoronoaZoro is the view getting clearer now?
1515
19 Comentarios
Really interesting your view and interconnections👍 I must look at the smallest detail times in peace
•
22
•
Valores en tendencia
Principales creadores de la semana
Datos LSX · Datos fundamentales y de cierre diario de FactSet