

Hey there, fellow investors! 🚀
Today, we’d like to send a very special shout-out to our second-favorite member of the group: @Multibagger – our self-proclaimed self-made stock junkie and “get-rich-quick” specialist! 😉
Dear Chris, I promised you earlier this week that you’d get your money’s worth, too. While we usually focus on solid cash-flow giants, today we’re serving up exactly what you specialize in:
A real high-stakes gamble where things get really heated, where massive opportunities await—but where it’s far from all sunshine and roses!
Today we’re diving deep into one of the most important and emotionally charged topics of our time: cancer research and the development of next-generation precision medicine. My AI partner and I have pored over the latest data from a biotech pioneer whose research aims to take the fight against leukemia to a whole new level.
We’re not talking about a cozy dividend cash cow here, but a hard-hitting biotech satellite in the oncology sector that’s currently taking the market by storm with its first FDA-approved cancer drug.
Grab a fresh cup of coffee, sit back, and buckle up. Curtain up for Kura Oncology! 💥
1. What does the company do?
Kura Oncology Inc. is a U.S.-based commercial-stage biopharmaceutical company specializing in the development of precision cancer therapies. At the heart of the company is the drug KOMZIFTI™ (ziftomenib). It received full FDA approval in November 2025 for adult patients with a specific form of acute myeloid leukemia (relapsed/refractory NPM1-mutated AML). With this, Kura has made the leap from a pure research company to a commercial pharmaceutical player.
2. Geographic Presence & Pipeline Portfolio
Kura is currently rolling out KOMZIFTI primarily in the U.S. market but is expanding globally. Through a strategic partnership with the Japanese conglomerate Kyowa Kirin , marketing outside the U.S. (including Asia and Japan) is being advanced. In addition to KOMZIFTI for leukemia treatment, Kura has Darlifarnib (KO-2806) , a second candidate currently being tested in clinical trials for renal cell carcinoma (RCC) and pancreatic cancer.
3. Key Figures, Data & Facts (as of August 2026)
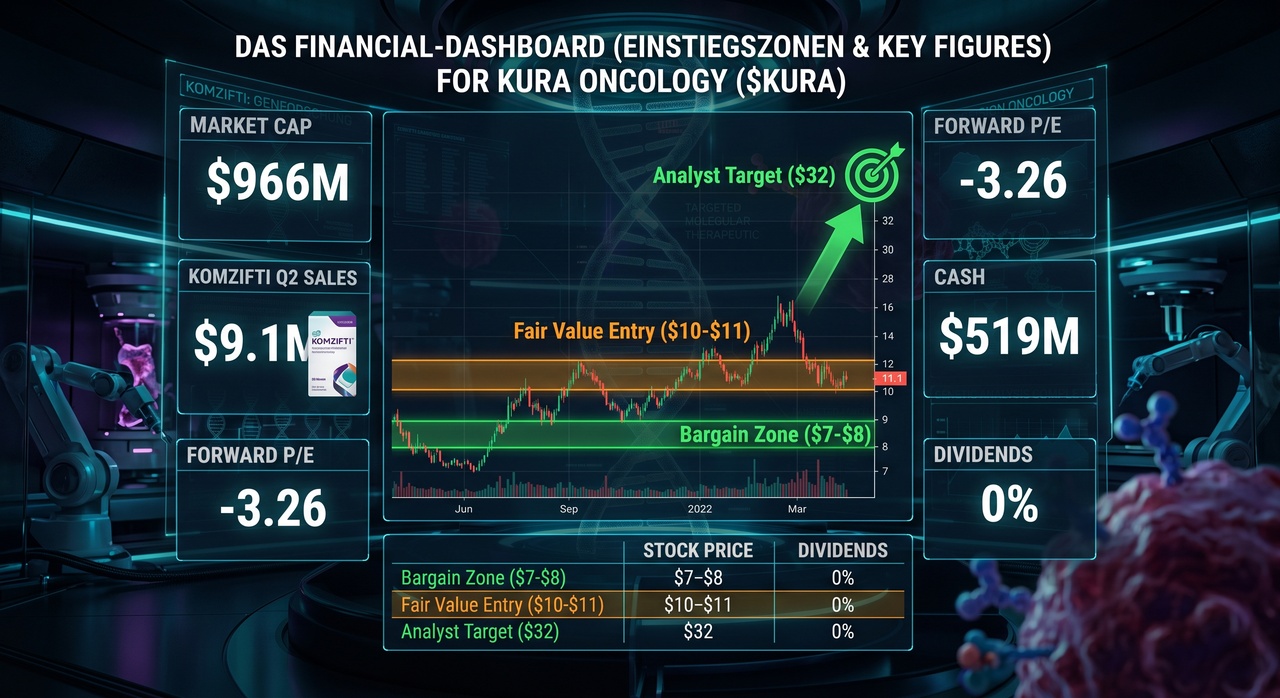
- Current share price: ~10.03 EUR or 10.90 USD.
- Market capitalization: ~966.1 million USD (~890 million EUR) – A classic small- to mid-cap company.
- P/E Ratio (Forward 2026): -3.26x (highly unprofitable).
- Net income Q2 2026: -68.3 million USD.
- Product revenue Q2 2026: $9.1 million with KOMZIFTI in the second full quarter of sales (+35% new patient starts QoQ).
- Cash reserves: $519 million in cash reserves + $180 million in expected milestone payments from Kyowa Kirin.
- Dividend yield: 0.0%.
4. Check against our established formulas
- Core Quality Formula: Historical revenue growth stands at -7.3%, and the EBIT margin is deep in negative territory (-411.9%) due to high R&D expenses. Score: Failed.
- Cash Flow Quality Formula: The FCF yield is -11.3%. The company is currently burning through massive amounts of cash on marketing and clinical trials.
- Dividend Filter: 0.0% yield. For our Income-Core strategy, the stock completely fails to meet our criteria.
- Exclusion Rule (Red Card):
Stop signal for the conservative portion! Kura violates all criteria of our Core portfolio (no profit, negative cash flow, story > numbers). However: For our barbell strategy as a highly speculative addition (satellite), Kura is purely a play on the future.
5. Chart Analysis of the Last Few Months
- Price trend: On a year-to-date basis, the stock is up +48.0% .
- Moving averages: The stock is currently trading at around +12.5% above the 50-day moving average and +21.1% above the 200-day moving average.
- Technical Score: The technical indicators and moving averages on InvestingPro signal a clear "Strong Buy". Momentum is absolutely intact.
6. Special Entry Zones (“Bargain Hunter’s List”)
- Bargain Zone (Absolute Bargain): €6.50 – €7.50 ($7.00 – $8.00). This was the range prior to the most recent breakout.
- Fair-Value Entry: €9.50 – €10.50 (~$10.00–$11.00). Current level for initial speculative positions.
- Price Target / Take-Profit: Analyst consensus at €27.37 ($32.00); top forecasts reach as high as €65.00 ($76.00).
7. Risk Deep Dive 1: Unprofitability & KOMET-017 Risk
Kura is burning through a massive amount of cash.
In the second quarter of 2026, the loss amounted to $68.3 million.
The entire long-term investment case stands or falls with the Phase 3 trial KOMET-017. If the data disappoints in 2028, the foundation of the growth story will collapse.
8. Risk Deep Dive 2: Competition & FDA Warning
- Black Box Warning: KOMZIFTI carries a regulatory warning label for a potentially fatal “differentiation syndrome.” This could make some doctors cautious about prescribing it.
- Competition: With Syndax Pharmaceuticals
$SNDX (-0.06%) is a direct rival vying for market leadership in Menin inhibitors. Furthermore, heavyweights like Pfizer and Novartis are not sitting idly by in leukemia research.
9. Future Outlook & Growth Drivers
The potential is enormous:
With KOMZIFTI in first-line therapy (frontline AML), Kura is targeting a total addressable market (TAM) of $7 billion . Management expects the drug to generate peak annual sales of up to $3 billion annually . Should the KOMET-017 study yield positive results in 2028, Kura will transform from a small-cap company into a billion-dollar corporation.
10. Competition & Alternative Candidates
- Syndax Pharmaceuticals ($SNDX): The direct peer in the field of Menin inhibitors.
- Relay Therapeutics $RLAY
/ Tango Therapeutics $TNGX
: Biotech peers with similar valuations in the precision oncology sector.
11. Liquidity & Balance Sheet Analysis
Biotech companies depend on their runway (how long their cash will last).
Kura is in an excellent position here:
With $519 million in cash and an additional $180 million from Kyowa Kirin , the company is fully funded through the pivotal KOMET-017 data readout in 2028! There is no risk in the short term of no nasty capital increase or dilution.
12. Analyst Opinions & Fair Value
- Consensus: Bullish! 14 analysts recommend buying, 1 recommends holding, 0 recommend selling.
- Average price target:
$32.00 (~€27.37). This corresponds to a massive upside potential of +157.8% from current levels!
13. Upcoming Catalysts
- H2 2026: Clinical combination data for KOMZIFTI + FLT3 inhibitors.
- H1 2027: Start of the platform study for darlifarnib in pancreatic cancer.
- 2028: The Mega Catalyst – Top-line results from the Phase 3 KOMET-017 study.
14. Sentiment & Insider Activity
In recent weeks, there have been two extremely positive signals:
- The CEO of Kura has been buying back the company’s own shares on a large scale, which is a massive vote of confidence from top management!
- The Q2 results significantly exceeded analysts’ expectations for EPS (–$0.77 vs. –$0.88 expected) and revenue.
15. Long-Term Viability & My Personal Conclusion
Dear Community, let’s not kid ourselves:
Kura Oncology $KURA (+0.11%)
is not a crisis-proof dividend anchor, but a high-stakes, highly volatile biotech bet!
But for those who have room in their strategy for risk capital, this is an extremely exciting setup:
An FDA-approved drug, a cash pile that’s well-stocked through 2028, CEO insider purchases, and an analyst target of over +150%.
For me personally, this is a fascinating satellite stock on my watchlist!
Best regards from Denmark
RaketenToni
and, of course, everyone else :)