

...as already announced, there will be another biotech gamble from my direction in January.
@Tenbagger2024
@Dividendenopi
@Multibagger
@Klein-Anleger
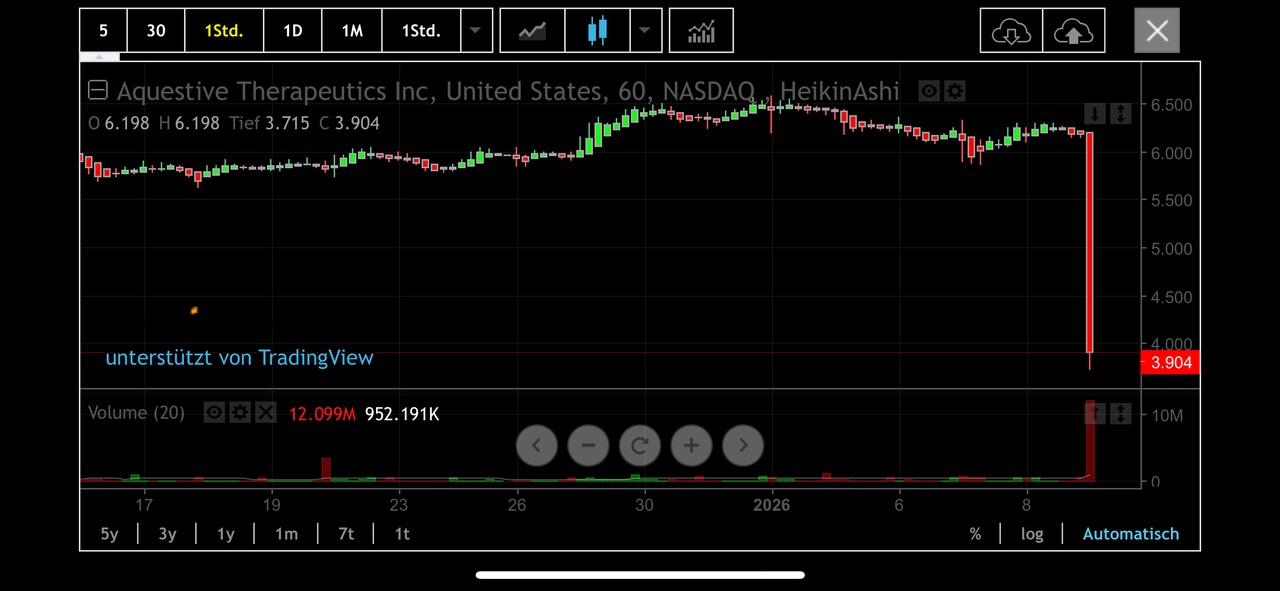
Today, completely by chance, I read news about $AQST read. An application for approval is currently being submitted to the FDA, with a decision date of 31.01.2026.
The FDA has pointed out "deficiencies in the application". Share price reaction today: -38%!
No clear indication of the problem, so it is difficult to assess the ultimate impact. However, the application has not been rejected (which I consider positive for the time being) and the review is continuing. According to the FDA, a decision will not be made before the deadline that has already been set.
The company is, of course, desperately waiting for a clearer statement from the FDA, but has already signaled that it wants to clear up any ambiguities or questions during the review, i.e. by the decision date.
In principle (although the details are different), this scenario reminded me very much of the scenario at $FBIO some time ago. I looked at the key facts about the company and the preparation that is the subject of the application is, in my view, really something special.
Specifically, it is Anaphylm, a sublingual film (to be placed under the tongue) for the treatment of severe allergic reactions. The special thing about it: while epinephrine currently has to be injected by syringe for allergic shocks $AQST has packed a life-saving dose of epinephrine into a self-dissolving gel platelet, which releases the necessary epinephrine via the mouth without the need for fluids.
In my opinion, this offers considerable advantages for emergencies. Easy storage (unrefrigerated, even in hospitals etc.), easy handling for really anyone (even untrained helpers etc., I wouldn't know where or how to hammer it into someone with allergic shock and an emergency pen in their pocket muss🤷🏼♂️), lighter, smaller, easier to handle etc....
Long story short: For me, it is not a completely absurd scenario that it is rather errors in the application with regard to the design of the application than doubts about the efficacy that play a role here (why else would one continue to review and not reject directly, does the FDA do this often enough?)
In my view, two scenarios can occur here:
- If approved, potential peak sales of up to 700 million US dollars (2035e) beckon.
- If it is rejected, the share price could fall further, but in my opinion the price currently already includes a worst-case scenario.
I therefore have the feeling that the market reaction is currently exaggerated here too and have entered the stock today with the same "play money" size at $AQST as I did with $FBIO at the time.
I didn't hit the daily low perfectly, but of course a little more research and consideration was still necessary.
The same applies here: absolute high-risk, high-reward gambling, only imitate if you have looked into it yourself, weighed up the opportunities and risks for yourself and, in the worst case, can write off the invested capital without financial ruin.
For number crunchers, here again are the key financials and, as recently, the chart for a quick overview:
- Around USD 120 million in cash at the end of 2025 - enough to cover all approval and launch costs.
Valuation:
- Market capitalization: 757.64 million US dollars
- Revenue growth in 2024: 13.8%
- Expected decline in sales in 2025: -21.8% (due to delays at Anaphylm to date)


