
Evotec is in the midst of the most drastic restructuring in its history—and the figures for the third quarter of 2026 show signs of life for the first time. The Hamburg-based drug discovery company and biologics manufacturer generated €164.9 million in revenue from July through September—more than in any other quarter this year—and adjusted EBITDA improved from −€15.0 million to just −€1.6 million. On November 5, 2026, management confirmed the full-year forecast—which had been drastically lowered in July—of €570 million to €610 million in revenue and −€105 million to −€70 million in adjusted EBITDA. In addition, there is a manufacturing contract from Vertex Pharmaceuticals for the subsidiary Just – Evotec Biologics and an ongoing strategic review of the entire group, which does not rule out a sale. The stock closed at €3.16 on Xetra on November 11, 2026, more than 50% below its 52-week high of €6.73. Analysts have an average price target of €4.08. From a technical analysis perspective, the stock has stabilized in the €2.85 range, but the annual low of €2.406 remains the key sell trigger.
Key Points
- Q3 2026: Revenue €164.9 million (previous year: €163.9 million), adjusted EBITDA −€1.6 million (previous year: −€15.0 million)
- Nine months: Revenue €465.0 million (−13.1%), adjusted EBITDA −€44.3 million
- 2026 forecast confirmed: Revenue of €570 to €610 million, adjusted EBITDA of −€105 to −€70 million
- 2030 target: approximately €1 billion in revenue, 20% EBITDA margin by the end of 2028
- Vertex Selects Just – Evotec Biologics for the Commercial Manufacture of Povetacicept
- Strategic review with Morgan Stanley and Moelis continues; liquidity at €400.9 million
- Analysts: Average price target €4.08, range €3.50 to €5.00
- Chart levels: Support at €2.865, resistance at €4.04 and €5.108, sell trigger at €2.406
What are the current key metrics for Evotec stock?
At €3.16 (Xetra closing price as of November 11, 2026), Evotec stock has a market capitalization of only about €0.56 billion—less than one year’s revenue.
A P/E ratio cannot be meaningfully calculated because Evotec is reporting operating losses in 2026. Based on the revenue forecast of €570 million to €610 million, the price-to-revenue ratio is just under 1, while the average over the last ten years, according to Aktienfinder, was 5.3. Evotec does not pay a dividend.
- Price (Xetra: EVT): €3.16 (close on Nov. 11, 2026)
- 52-week high: €6.73 (January 2026)
- 52-week low / annual low: €2.406 (October 13, 2026)
- All-time high: €45.83 (September 2021)
- Market capitalization: approx. €0.56 billion (approx. 178 million shares) (November 11, 2026)
- Revenue Q3 2026: €164.9 million (previous year: €163.9 million) (November 5, 2026)
- Adjusted EBITDA for Q3 2026: −€1.6 million (previous year: −€15.0 million) (November 5, 2026)
- Revenue for the first 9 months of 2026: €465.0 million (−13.1%) (November 5, 2026)
- Adjusted EBITDA for the first 9 months of 2026: −€44.3 million (previous year: −€16.9 million) (November 5, 2026)
- Liquidity: €400.9 million (end of June: approximately €465.6 million) (September 30, 2026)
- 2026 Forecast: Revenue €570–610 million, adjusted EBITDA −105 to −70 million (confirmed Nov. 5, 2026)
- 2030 Target: Approximately €1 billion in revenue, EBITDA margin of 20% starting in late 2028 (November 5, 2026)
- Price-to-Sales Ratio: just under 1 (10-year average 5.3) (November 12, 2026)
- Average analyst price target: €4.08 (+29%), range €3.50–5.00 (November 12, 2026)
- Dividend: none (—)
- Next Earnings Report (Full Year 2026): expected in April 2027 (date to be announced) (Evotec IR)
- Index: SDAX (since September 22, 2025; previously MDAX) (—)
- WKN / ISIN / Ticker: 566480 / DE0005664809 / EVT (—)
What news is currently driving Evotec’s stock?
Evotec’s stock is currently being driven primarily by the significantly better third quarter, with an almost break-even adjusted EBITDA—and the question of what the outcome of the strategic review will be.
On earnings release day, November 5, 2026, the stock jumped by a good 7% on Xetra to €3.09. This followed a sharp decline: Following the downward revision of the forecast in July, the stock lost around 24% in a single day; in October, it hit its annual low of €2.406. An additional drag came from the exit of the Abu Dhabi sovereign wealth fund, which, according to a voting rights notification dated October 15, 2026, reduced its voting stake from 5.62% to zero. My analysis of Bayer Aktie.
- November 5, 2026 – Q3 Clearly Better, Forecast Confirmed: Revenue of €164.9 million, adjusted EBITDA of −€1.6 million following −€15.0 million. Full-year forecast confirmed; 2030 revenue target specified at approximately €1 billion. Stock up a solid 7% on Xetra. (Bullish)
- November 5, 2026 – Vertex Order for Just – Evotec Biologics: Vertex Pharmaceuticals selects the subsidiary for the commercial manufacturing of the active ingredient povetacicept at the J.POD Redmond facility. (Bullish)
- November 5–9, 2026 – Analysts remain cautious: RBC reaffirms “Outperform” at €5.00; Berenberg raises its target to €3.75 (“Hold”); Deutsche Bank maintains “Hold” at €3.50. (Neutral)
- October 30, 2026 – RBC cuts price target in half: RBC lowers the price target from €10 to €5 and classifies the stock as speculative, but maintains its “Outperform” rating. (Bearish)
- October 13, 2026 – Annual low at €2.406: After a daily loss of about 11% on Oct. 12, the stock falls to its annual low. Mubadala (Abu Dhabi) completely exits its position. (Bearish)
- July 13, 2026 – Ad hoc: Forecast drastically lowered: 2026 revenue target lowered from €700–780 million to €570–610 million; adjusted EBITDA lowered from 0 to 40 million to −105 to −70 million. Stock down about 24% the following day. (Very bearish)
What does Evotec’s management say about the quarterly results?
CEO Dr. Christian Wojczewski sees encouraging progress: The strategy is increasingly taking hold and is reflected in the figures; the Horizon cost-cutting program is ahead of schedule.
CFO Claire Hinshelwood now wants to translate this momentum into sustainable revenue growth and more cash.
What went well: Adjusted EBITDA improved by 89% to −€1.6 million in the third quarter, primarily due to lower manufacturing costs. The gross margin rose from 4.1% to 12.0%. Net orders in the core drug discovery business increased by 24% over the first nine months. Just – Evotec Biologics grew by 9.4% to €44.8 million in the quarter and, with the Vertex contract, has been selected for commercial manufacturing for the first time. More than 20% of the planned €75 million in annual cost savings by the end of 2027 have already been achieved.
The catch: After nine months, revenue is 13.1% below the prior year, and adjusted EBITDA, at −€44.3 million, is significantly deeper in the red than in the prior year (−€16.9 million). Liquidity has shrunk from around €465.6 million at the end of June to €400.9 million. The medium-term target has been scaled back: Instead of “more than €1 billion,” Evotec is now aiming for “around €1 billion” in revenue for 2030. And for the final quarter, Evotec will have to deliver strong results once again to meet the full-year forecast.
Outlook: For 2026, the guidance remains at €570 to 610 million in revenue and −€105 to −€70 million in adjusted EBITDA. By the end of 2028, the adjusted EBITDA margin is expected to reach 20%, and by the end of 2030, it is expected to exceed that level. Meanwhile, the Group’s strategic review continues. According to the CEO, Evotec is negotiating new partnerships in areas including kidney disease, cancer, women’s health, and obesity—precisely the fields where the pharmaceutical giants are currently fighting their fiercest battles, as my analysis Novo Nordisk Aktie shows.
What does Evotec do, and how does the company make money?
Evotec is a service provider to the pharmaceutical industry: The company researches and develops active ingredients on behalf of partners and, through its subsidiary Just – Evotec Biologics, manufactures antibodies and other biologics.
Headquartered in Hamburg, the group employs around 4,500 people in Europe and the U.S. and, according to its own figures, collaborates with all 20 of the largest pharmaceutical companies and more than 800 biotech firms.
Discovery and Preclinical Development (D&PD): This larger segment conducts research on new active ingredients on behalf of clients through to clinical-stage readiness, supported by AI platforms. In the third quarter, it generated revenue of €120.1 million (−2.3%) with an adjusted EBITDA of −€1.0 million. By 2030, the core business is expected to contribute approximately 40% and strategic partnerships approximately 20% to consolidated revenue.
Just – Evotec Biologics (JEB): The U.S. subsidiary develops and manufactures biologics using continuous manufacturing, for example at the J.POD facility in Redmond. Third-quarter revenue: €44.8 million (+9.4%), adjusted EBITDA: −€0.6 million. By 2030, JEB is expected to account for approximately 40% of consolidated revenue.
How Evotec Makes Money: Through research contracts and services, upfront and milestone payments from partnerships, licensing agreements, and, in the future, royalties on drugs resulting from these collaborations. It is precisely these milestones that cause revenue to fluctuate: A large part of the downward revision to the forecast in July was due to delayed payments. Anyone who wants to understand how heavily a biotech stock depends on individual pipeline successes can find a counterexample in my analysis of BioNTech Aktie.
Evotec Stock Fundamental Analysis: How Much Is Evotec Really Worth?
Fundamentally, Evotec is a turnaround story: Based on revenue, the stock is cheaper than it has been in years; however, as long as the company continues to post losses, the valuation remains a bet on its turnaround.
There is no P/E ratio due to a lack of profit.
Valuation: With a market capitalization of around €0.56 billion and expected revenue of €570 million to €610 million, the price-to-revenue ratio is just under 1. According to Aktienfinder, investors have paid an average of 5.3 times revenue over the past ten years. Based on this historical revenue multiple, Aktienfinder calculates a fair value of approximately €17.81 per share as of the end of 2026. This figure should be viewed with caution: It stems from the boom years of the biotech industry, when Evotec was still growing profitably, and says nothing about today’s losses.
Margins: The gross margin rose from 4.1% to 12.0% in the third quarter, but after nine months it stands at only 3.6% (previous year: 10.7%). Operating income for the nine-month period was −€254.8 million, weighed down by €91.9 million in restructuring costs. The adjusted EBITDA margin is not expected to reach 20% until the end of 2028.
Liquidity and Debt: As of the end of September, Evotec had €400.9 million in cash and cash equivalents, with net debt. Since the end of June, approximately €65 million has been drawn down. In 2026, Evotec also issued a convertible bond worth €116.1 million. While there are no signs of an immediate cash crunch, the company’s financial flexibility is shrinking as long as its operating business continues to burn through cash.
Costs: The Horizon program is expected to save approximately €75 million annually by the end of 2027. About half of the planned job cuts have been implemented, and three of the four site closures are expected to be completed by the end of the year. Research expenses fell to €29.7 million over nine months (6.4% of revenue).
Context: My analysis of Plug Power Aktie —there, cash flow determines every price fluctuation.
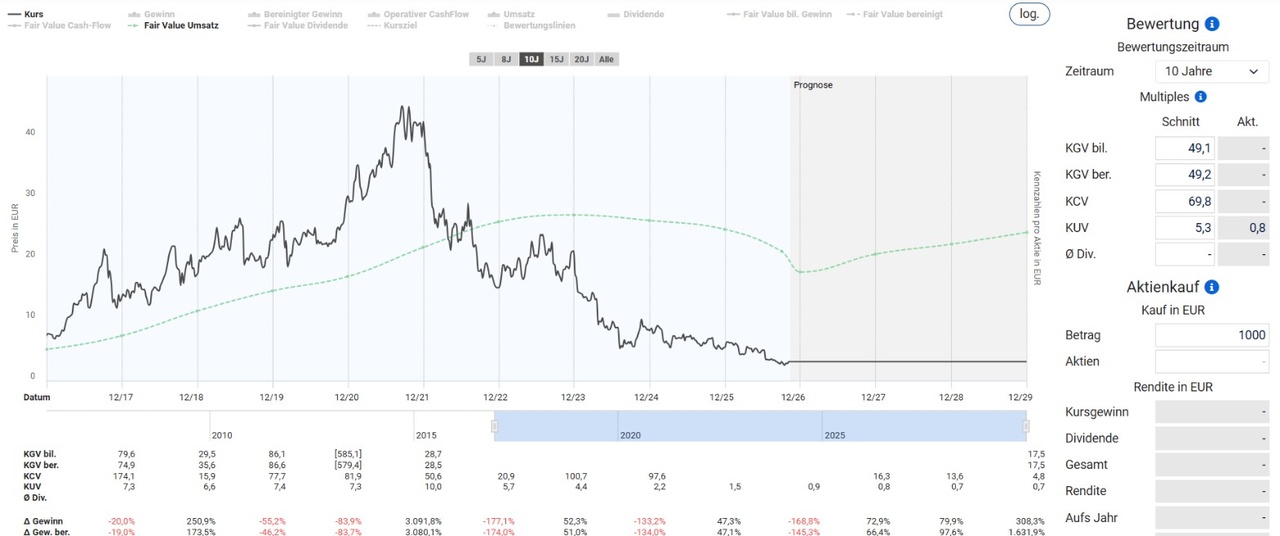
Fair Value Valuation of Evotec Stock (EVT) 2027 (as of Nov. 12, 2026) – Source: Aktienfinder / Christian Lill
Evotec Stock Price Targets and Forecast for 2027
Analysts see an average price target of €4.08 for the Evotec stock, representing about 29% upside potential—from a technical analysis perspective, the stock could test resistance near €4, but strong buy signals won’t emerge until the price moves well above €5.10.
Below the annual low of €2.406, however, the next sell-off looms.
Key price levels:
- 52-week high: €6.73 (January 2026)
- Current price: €3.16 (Xetra close on Nov. 11, 2026)
- First resistance level: €4.04 (red zone)
- Second resistance level: €5.108 (red line; strong buy signals only appear well above this level)
- Upper target in the bullish scenario: €11.325 (gray zone)
- Support: €2.865 (yellow zone)
- Critical downside level: €2.406 (annual low, sell trigger)
Analysts’ price targets:
- Average price target: €4.08 (three firms, range €3.50 to €5.00, as of Nov. 12, 2026)
- RBC Capital Markets: Outperform, €5.00 (November 5, 2026)
- Berenberg: Hold, €3.75 (November 6, 2026)
- Deutsche Bank: Hold, €3.50 (November 9, 2026)
Chart Analysis:
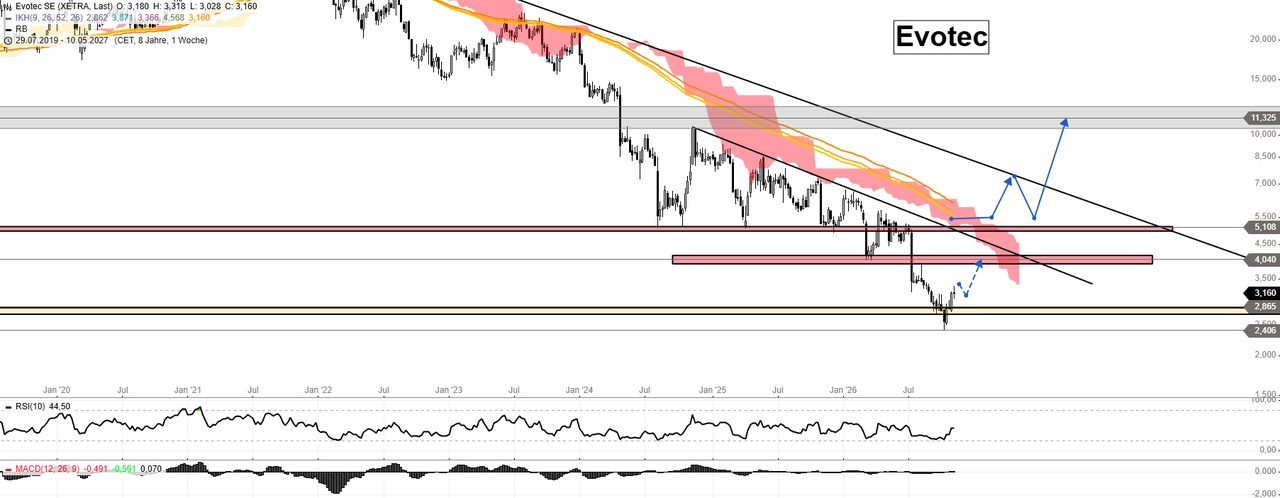
Evotec Stock (EVT) Chart Analysis and Price Targets for 2027 (as of November 12, 2026) – Source: Stock3 / Christian Lill
On the weekly chart, the Evotec stock has been trading below two descending trend lines for years, with the red Ichimoku cloud acting as an additional ceiling above them. Following the crash in July and the annual low of €2.406 in October, the stock appears to be stabilizing somewhat around the €2.85 level. That is precisely where the yellow support zone at €2.865 lies, from which the stock recently rebounded to €3.16.
The more likely scenario (blue arrow): I consider it possible that the stock will test the resistance level just below €4. The red resistance zone lies at €4.04—a level where the stock has struggled repeatedly in the spring of 2026—and this is also where the lower downtrend line and the cloud converge. From the current price, the path to that level would represent about 28% upside potential, but that does not yet constitute a buy signal.
Things only get interesting once the price moves above that level: Major buy signals only emerge when prices are well above €5.10. The next red resistance line is at €5.108, which has served as a support level for years and would now be tested from below. Only a clear breakout above this level would open up the larger bullish scenario on the chart—with pullbacks along the way and the upper target in the gray zone at €11.325.
The counter-scenario: The downtrend remains intact. If the news story fails to boost stock prices now, the outlook could look really bleak in the medium term. The current annual low of €2.406 serves as a sell trigger and is likely to trigger further price volatility on the downside.
Indicators: The RSI(10) stands at 44.5 in the neutral range, while the MACD, at −0.491 to −0.561, remains well below the zero line. The indicators thus do not yet provide confirmation of an upward trend.
Conclusion: Evotec Stock—Comeback Candidate or Value Trap?
Evotec finally delivered in the third quarter, but the stock remains firmly entrenched in a downtrend—the key question now is whether the news will propel the price above the resistance levels.
On the positive side are nearly break-even adjusted EBITDA in the third quarter, the Vertex contract for Just – Evotec Biologics, a cost-cutting program ahead of schedule, and a valuation of just under one year’s revenue. Added to this is the strategic review with Morgan Stanley and Moelis, which, in the best-case scenario, could lead to a takeover bid—though nothing has been confirmed yet.
On the downside are a 13.1% decline in revenue after nine months, a shrinking cash cushion of €400.9 million, a subdued target for 2030, and a consensus among analysts that largely advises holding the stock. From a technical analysis perspective, I consider it possible for the stock to test the resistance level of just under €4, but strong buy signals won’t emerge until the price moves significantly above €5.10. If the stock falls below the annual low of €2.406, it could trigger further downward price volatility. My analysis of Siemens Energy Aktie — Evotec is still a long way from that.
✅ Opportunities
- Q3 2026: adjusted EBITDA of −€1.6 million, compared to −€15.0 million in the prior year
- Vertex contract: first commercial manufacturing for Just – Evotec Biologics
- Horizon cost-cutting program ahead of schedule, €75 million in annual savings by the end of 2027
- Valuation at just under one year’s revenue; 10-year average of 5.3
- Strategic review could lead to an acquisition or spin-off
- Chart target of €4.04 possible; average price target €4.08; RBC sees €5.00
⚠️ Risks
- Revenue after nine months 13.1% below prior year; July forecast halved
- Liquidity has fallen from around €465.6 million to €400.9 million since June
- Dependence on fluctuating milestone payments from partners
- 2030 revenue target of around €1 billion has been scaled back
- Two out of three analysts recommend only holding the stock; RBC classifies it as speculative
- Downward trend intact; another sell-off looms below €2.406
Sources
- Evotec: Third-Quarter and Nine-Month Results for 2026 (Nov. 5, 2026)
- Evotec: Ad-hoc Preliminary Half-Year Results and New 2026 Forecast (July 13, 2026)
- Evotec: First-Quarter 2026 Results and Strategic Review (May 6, 2026)
- Evotec Investor Relations: Financial Calendar
- APA (November 5, 2026): Evotec Lowers and Postpones Mid-Term Targets; dpa-AFX via finanzen.net and kapitalmarktexperten.de: Analyst Reports from RBC, Berenberg, and Deutsche Bank (Oct. 30–Nov. 9, 2026)
- Voting rights announcement by Mubadala/Abu Dhabi (October 15, 2026) according to finanztrends.de; MDAX delisting according to finanztrends.de (September 13, 2025) and MarketScreener (September 19, 2025); DER AKTIONÄR (April 7–8, 2026): Halozyme, fiscal year 2025
- Xetra prices: Alpha Vantage (daily and weekly data through November 11, 2026), finanzen.net (November 12, 2026)
- Stock3: Weekly chart for Evotec SE (Xetra, EUR), as of Nov. 12, 2026
- Aktienfinder: Fair value calculation (revenue) and valuation metrics for Evotec, as of Nov. 12, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What are your current thoughts on $EVT (-4.27%)?