A small purchase and a new addition to the portfolio this month. Next month, $WINC (-0.09%) . I’ve been involved in crypto since 2021, but I’ve also been investing in stocks—primarily dividend-paying stocks.
- Markets
- ETFs
- JPM NASDAQ Eqt Prem Actv ETF D
- Forum Discussion
JPM NASDAQ Eqt Prem Actv ETF D
Price
Discussion about JEPQ
Posts
86August performance
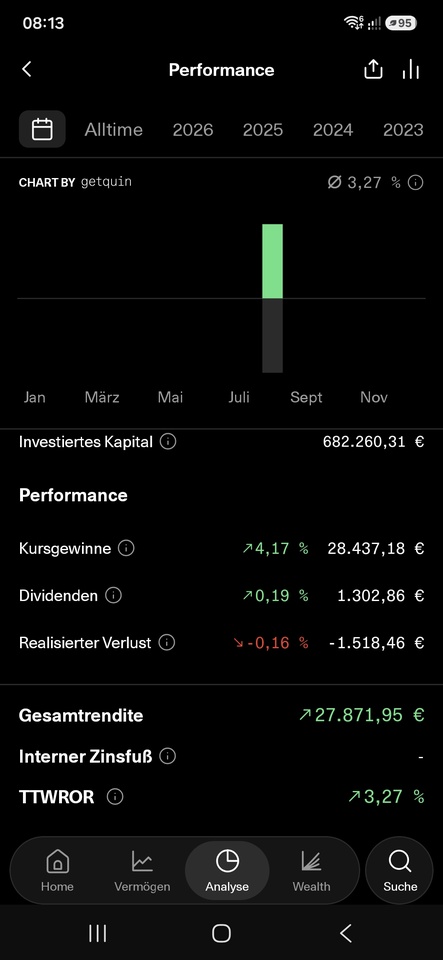
I think I'm satisfied with how the past month went. There were a few major unforeseen personal expenses that I had to cover. That's why I want to start by building up my cash reserve, which I'll fund with my salary and dividends.
I sold $YYYY (-0.2%) and invested the freed-up capital in $WINC (-0.09%) (50%) as well as $JEPQ (+0.25%) and $ASWM (-0.32%) (25% each).
I also bought a few more shares of Pepsi, Pfizer, and American Tower.
Another CC ETF Purchase
It might be a better alternative to your two pure CCs and the U.S. portion that overlaps with your $QYLE...
...it also performs significantly better in correction mode and, in addition to CCs, offers short-term bonds and U.S. Treasuries, with similarly high dividends.
Update on my "Bausparer" portfolio
With all-time highs currently skyrocketing, I figured I’d share some positive news for a change
Less max yield—more growth
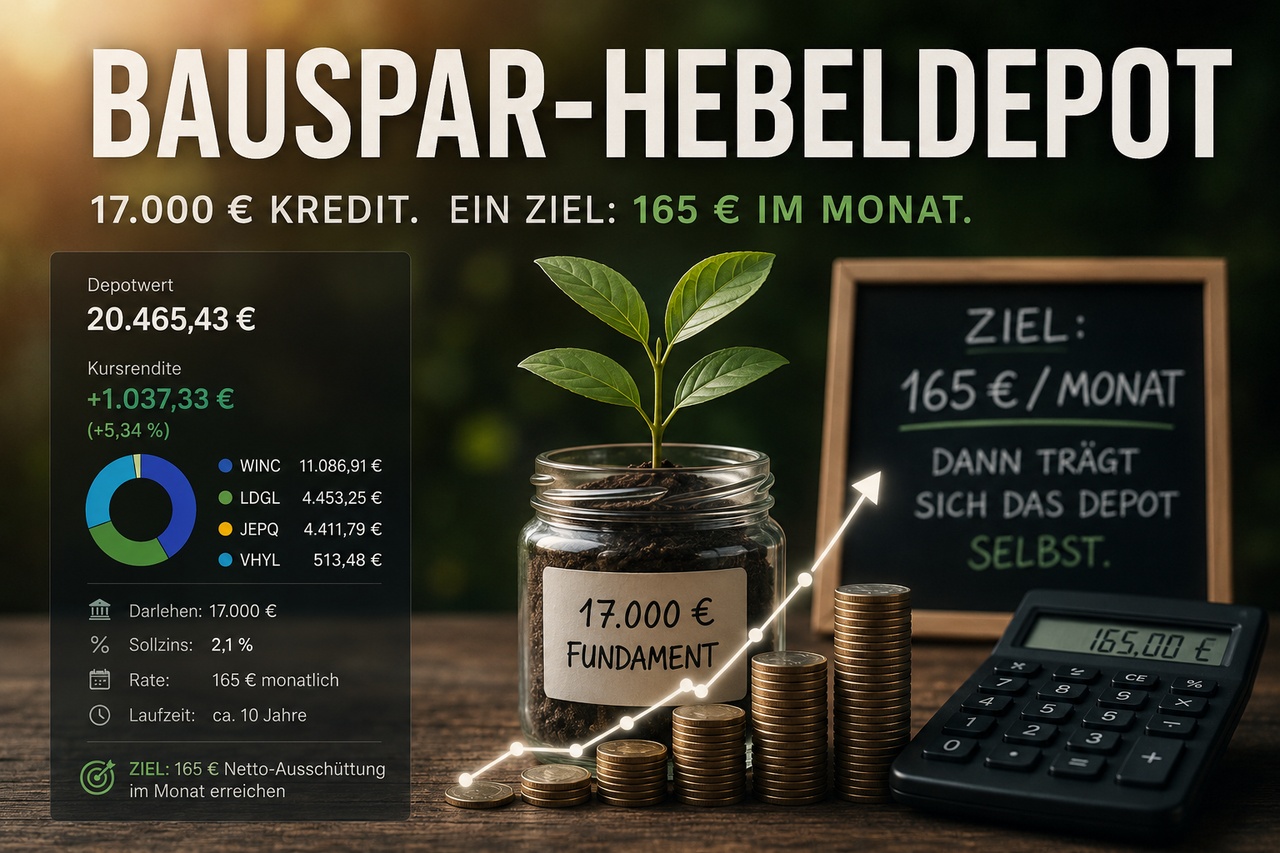
At the end of February, I started a separate portfolio that was originally funded by a home equity loan.
**Starting point:**
* Loan: €17,000
* Interest rate: 2.1%
* Monthly payment: €165
* Term: approx. 10 years
The basic idea is simple:
Build a portfolio that generates enough dividends over the long term to cover its own financing.
---
My status today
After just under four months, the portfolio currently looks like this:
💰 Portfolio value: **€20,465**
📈 Performance: **+€1,037 (+5.34%)**
Positions:
$WINC (-0.09%) : €11,087
$LDGL (-0.28%) : €4,453
$JEPQ (+0.25%) : €4,412 (covers the loan interest perfectly)
$VHYL (-0.35%) : €513
In addition, two savings plans are currently active:
* €250 monthly in WINC
* €250 monthly in VHYL
All dividends are reinvested.
---
## What has changed
The original portfolio consisted of:
* WINC
* JEPQ
* JEGP
After a few months, I sold the entire JEGP position and replaced it with the L&G Global Quality Dividends ETF.
Not because I think JEGP is a bad ETF.
On the contrary.
JEGP does exactly what it’s supposed to: deliver high ongoing dividends. But as many of us have noticed, unlike its counterpart on the Nasdaq, its price isn’t recovering at all.
However, it became clear to me relatively quickly that my goal isn’t to maximize dividends in the current year.
My goal is a portfolio that will still be growing in 10, 15, or 20 years, generating rising dividends.
That is why the portfolio today deliberately consists of a mix of:
* Cash Flow (JEPQ) to cover interest expenses
* High Income (WINC) to cover principal payments
* Quality dividends (LDGL) to build wealth
* Global dividend growth (VHYL) to build wealth
The actual idea behind the project
The original €17,000 forms the foundation for me.
This foundation is expanded month after month through:
* Savings plans
* Special payments
* Reinvested dividends
I do not measure success by a specific portfolio size.
The decisive milestone is:
➡️ €165 in net dividends per month.
Once the portfolio consistently generates this amount on its own, it will cover its own loan payments.
From that point on, it will be exciting to see how the system evolves under its own steam.
---
I’d be interested to know:
If your goal were not the maximum dividend today, but a long-term sustainable cash flow portfolio:
Would you have kept JEGP or also made the move toward quality dividends and dividend growth?
That’s how you beat interest rates and outperform them entirely through growth alone.
Invest the proceeds from the sale?!
Hello, I’ve sold my next property. I’d like to invest the profit as follows:
$TSWE (-0.49%) 36k,
$VHYL (-0.35%) 36K,
$ISPA (-0.17%) 36K,
$JEPQ (+0.25%) 36K,
$TDIV (+0.3%) 36K,
$LDGL (-0.28%) 30k
I'm also considering
$BHP (-1.11%) 20K,
$RIO (-0.66%) 20K, and
$O (-0.25%) 20K
$BRK.B (-0.48%) 30K
or directly in $BRK.B (-0.48%) 90k, since commodity stocks are trading a bit high for me right now! This position is like a high-risk money market account for me, which should be reallocated countercyclically.
My goal is to combine further dividend growth with modest portfolio growth. I no longer need high performers myself. I can still work for another 25 years, health permitting, and perform at a high level myself.
For me personally, individual stocks belong in my portfolio. Like the icing on the cake.
However, I will continue to focus on expanding my ETF positions through future asset reallocations.
In three years, my last major property in Germany will likely be sold. By then, the portfolio should be structured to enable my children to live a free, independent life anywhere on the globe.
What do you think? Would you change anything about the ETF positions? Wait on commodities too? Or put everything into SpaceX?
Thanks for the feedback.
Are you familiar with the mechanics of covered calls, in terms of risk and limited upside?
$BRK.B as a money market account—phew. Ultimately, it’s a stock that, due to its structure, doesn’t correlate very strongly with the market, though it’s still far from having a correlation of 0 or below.
I’ll leave your last two questions about commodities and SpaceX aside. That’s something you have to figure out for yourself. You yourself say, “You don’t need high performers anymore,” but you want to invest in SpaceX (which doesn’t pay dividends). That’s a contradiction in terms, so tell me: emotions are driving your investment strategy. And no amount of facts can counteract emotions.
Compensation for pain and suffering
So now that the portfolio is about 15k in the red, there is at least some compensation. But no real money either, because trade Republic has blocked my account and I can't spend it 🤑
Junior Depot
Hello everyone!
I started building up a small portfolio for my junior about 12 years ago. Not everything went well...but $GOOGL (+1.04%) beat them all: 81 shares, on average for 47€! We sold 15 shares in the fall for 270€, the remaining position is now up almost 20k!
The boy is only 13 - and his mother and sister are envious ;)
For some time now, I've been tormented by the question: should I reallocate or let it run? If I now gradually shift the position towards "income", e.g. into a $K0MR (-0.13%), $JEGP (+0.2%) or $JEPQ (+0.25%) (or a mixture thereof), that would certainly be a good investment in the long term:
20k * 6% = ~100€ per month!
The rest of the portfolio ($AWF , $AM (-0.85%) , $ARCC (-0.41%) , $DLR (+0.16%) , $D (-1.01%) & $RITM (-3.12%)) is also already generating €100 - I think that's a good basis for long-term wealth accumulation with a focus on a 2-ETF strategy!
What do you think?
Excellent etf
$JEPQ (+0.25%) Excellent covered call etf: grow + high dividends, no NAV decay.
-Nassim Nicholas Taleb
Trending Securities
Top creators this week