
The next value is $JEF (+1,85%)
I. The Deep Dive: Intrinsic Value
The valuation of Jefferies is currently a prime example of an undervaluation due to special effects. While the share price stands at approx. 62,20 $ the fundamental models speak a different language.
1st DCF model (discounted cash flow)
Based on the cash flow forecasts for 2026 (growth rate approx. 12.4 % p.a.), two scenarios emerge:
- Base Case: The fair value is approx. 121,84 $.
- Bull case (alpha spread): With an optimistic assumption of the IPO wave, the value will even rise to 131,14 $ .
- Reality check: Even more conservative models (Simply Wall St) see a fair value of at least 70.00 $ to 77.00 $.
2. relative valuation (multiples)
- P/E ratio: At approx. 20,4x Jefferies is well below the industry average for US capital markets (25,6x).
- P/B (price-to-book): Jefferies trades near its book value (approx. 1.2x), while the profitability of the investment banking division would justify a multiple of 1.5x to 1.8x.
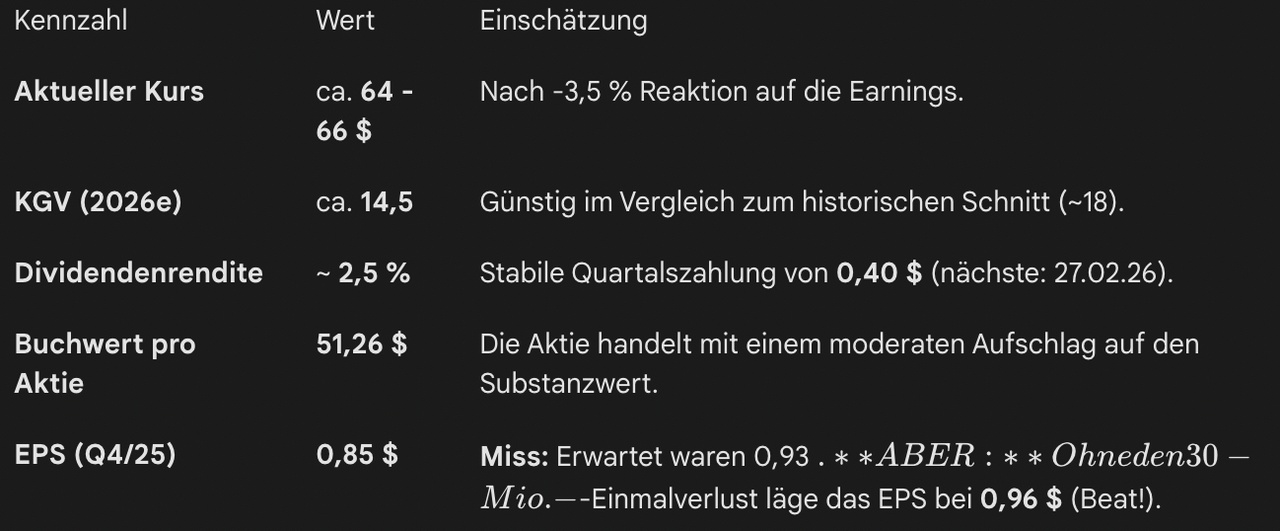
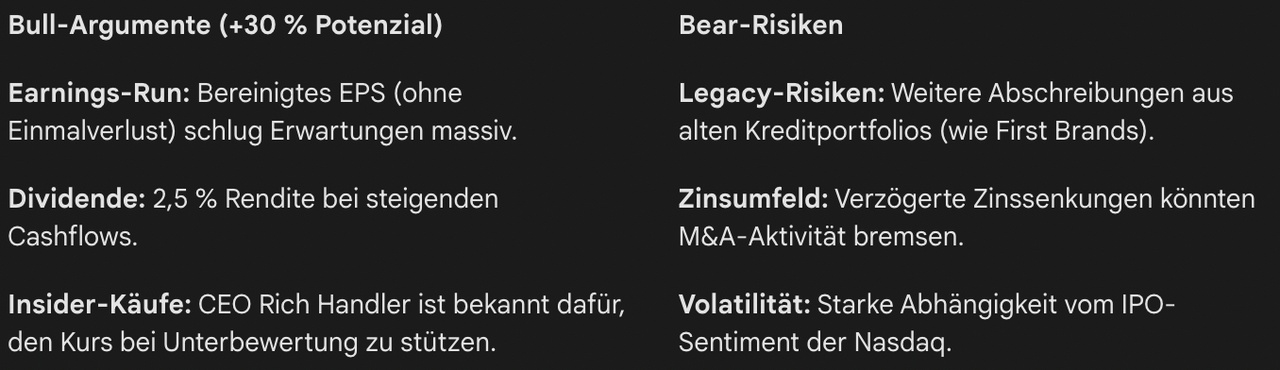
Summary: According to the DCF model, the share is undervalued by almost 50 % undervalued. The market currently pays significantly less for every dollar of profit at Jefferies than at its competitors.
II. project pipeline: The engines for 2026
Jefferies is no mere spectator, but the "architect" behind the biggest deals of the coming quarter.
1. the SMBC megaproject (alliance integration)
This is the most important internal value driver. The strategic alliance with the Japanese Sumitomo Mitsui Banking Corp (SMBC) is now fully operational:
- Capital leverage: Jefferies has access to 2.5 billion $ in credit facilities from SMBC.
- Market share: This allows Jefferies to act as financier on large M&A mandates (multi-billion deals) - an area previously reserved for the "bulge bracket" banks (JP Morgan, Goldman).
2. the "IPO renaissance" (equity underwriting)
Jefferies has positioned itself as the go-to bank for tech and growth companies. The pipeline for the 1st half of 2026 includes
- Fintech & Crypto: Preparation of the IPOs of Circle (USDC) and eToro (successor mandates).
- Healthcare: Over 9.4 billion $ in outstanding transactions in the healthcare sector alone (advisory & IPOs).
- India focus: Jefferies is currently advising on massive capital raisings and IPOs in the Indian market, which is considered to be the fastest growing for 2026.
3. defense & aerospace picks
In line with my holdings ($RDW (-5,24%)
Redwire, $VOYG (-2,74%)
Voyager), Jefferies has just (January 2026) published its top picks:
- Leidos ($LDOS (+4,41%)
) and L3Harris ($LHX (+2,65%)
) are their favorites for 2026. Jefferies holds the leading advisory and analysis mandates here.
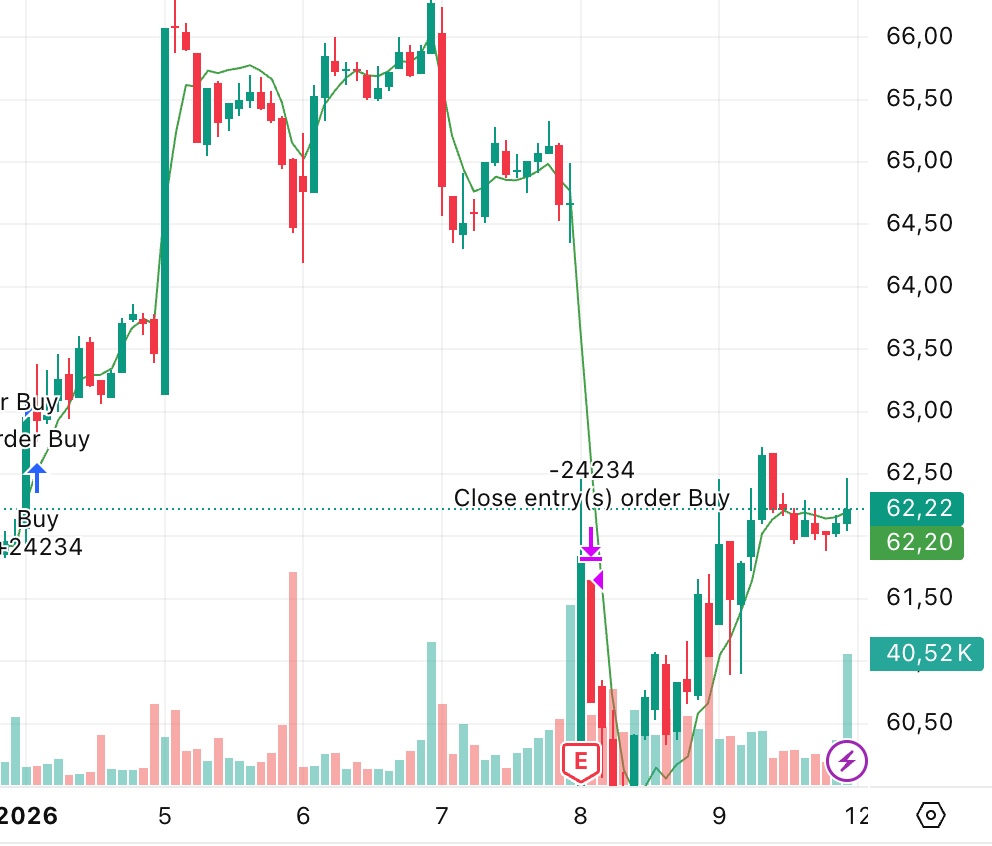
Of course, this is also an initial AI analysis, but I don't have the time for a more detailed one at the moment in addition to my studies. But I will have the courage to do so in the next few weeks :)
I think I'll place a first tranche on the stock on Monday. The IPO wave in particular should be interesting! True to the motto one, two risk!


