

In our series "Stocks with 20% CAGR potential", we are looking at a true "compounder" today: Copart $CPRT (+5,55%)
While many only look at AI hypes, Copart has revolutionized the salvage car market through its online auction platform. Here are the reasons why this stock is on our shortlist for the next five years:
---
Why Copart convinces
Owner mentality:
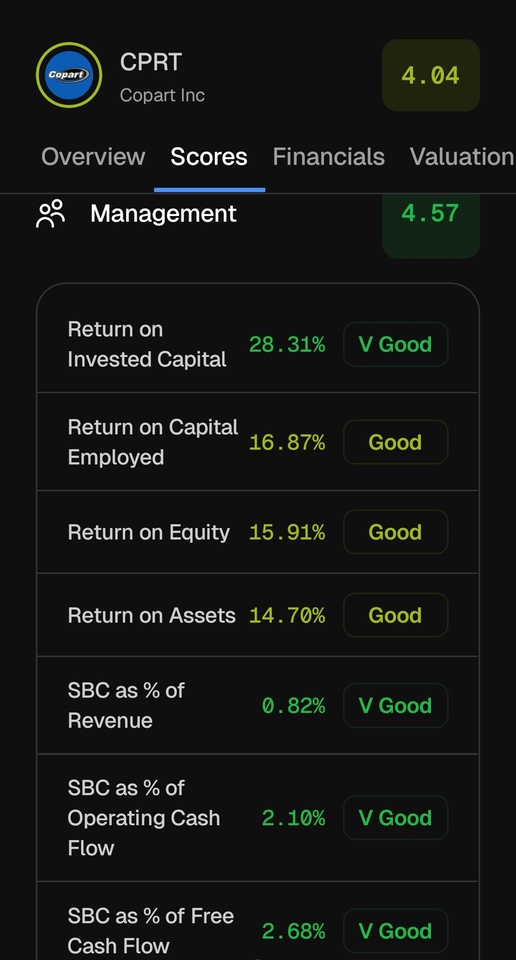
The founder is still on board and the management holds around 6% of the shares. This ensures a long-term perspective instead of short-term quarterly thinking.
Financial fortress:
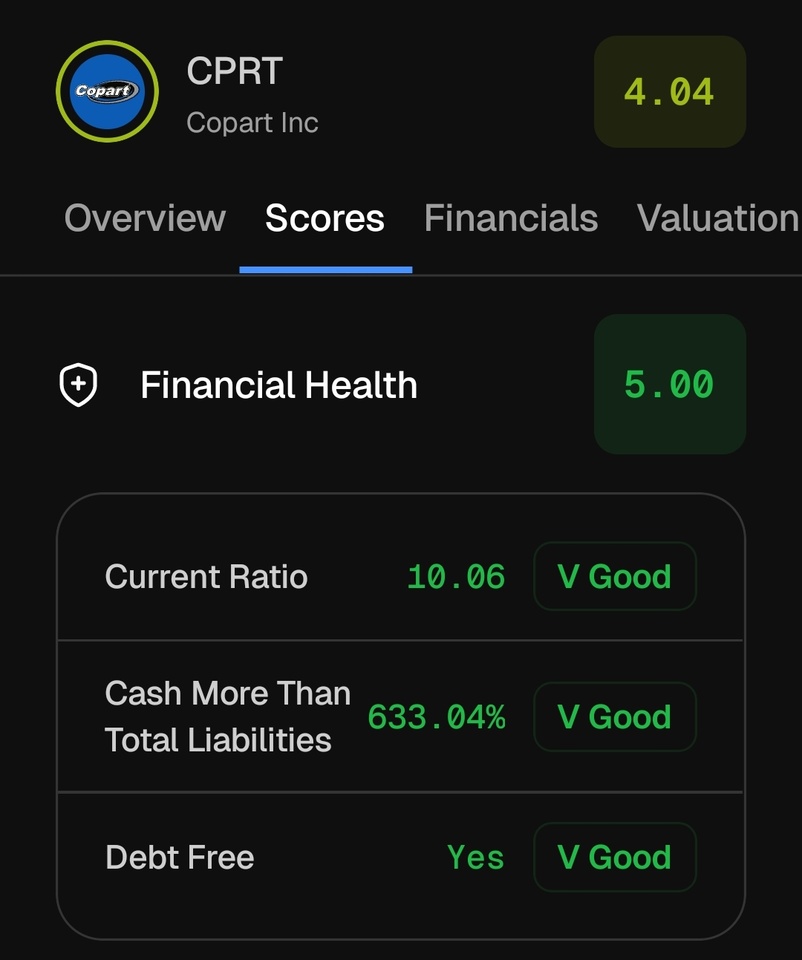
The company is virtually debt-free and has a cash cushion of around 20% of the balance sheet. This gives it enormous flexibility to continue investing even in difficult market phases.
Strong margins:
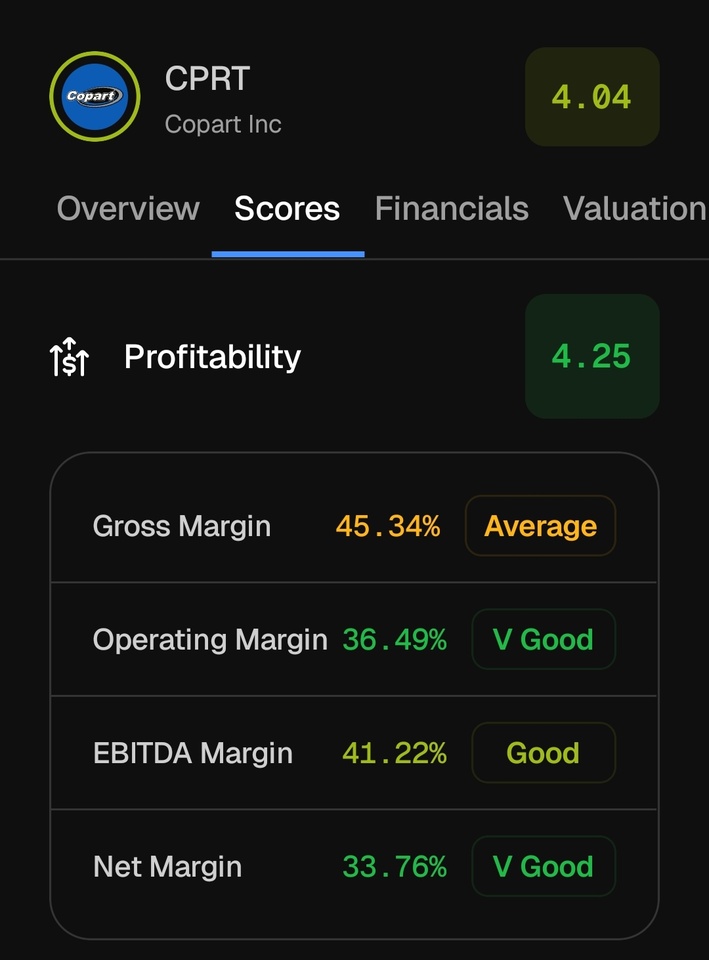
With an operating margin of around 36%, the market leader's pronounced pricing power is evident.
---
Valuation & return outlook
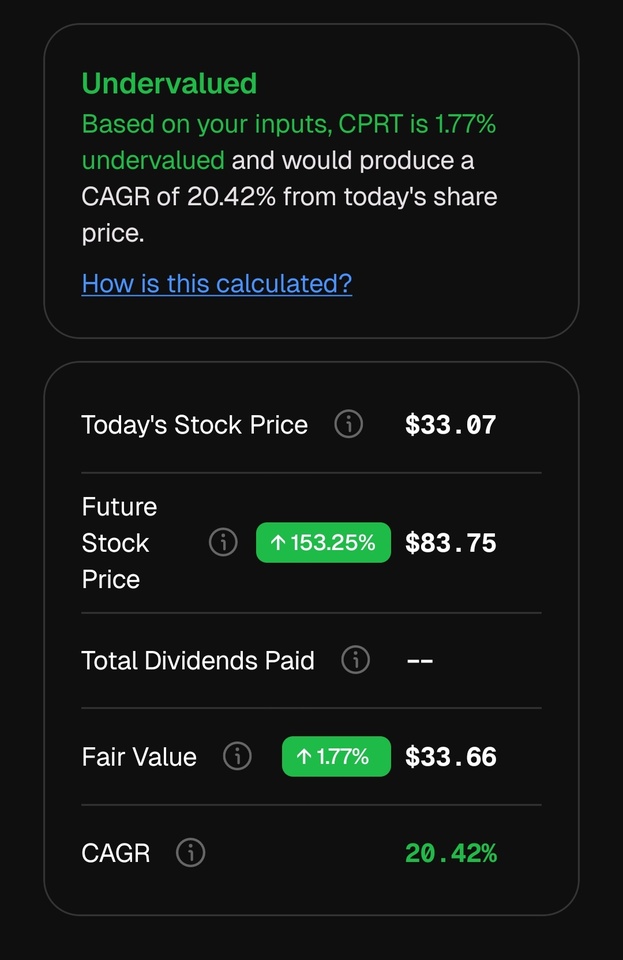
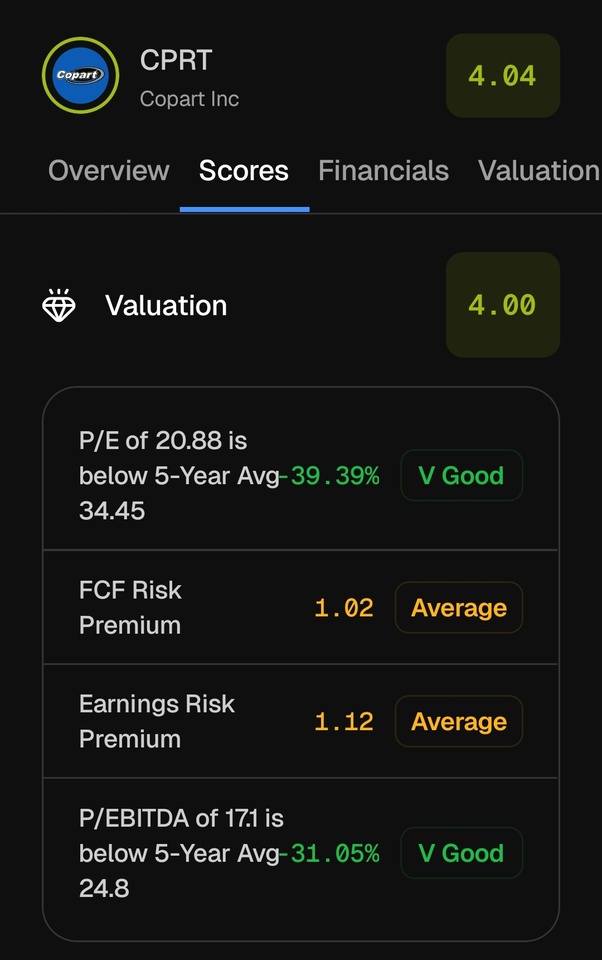
The analysis with StockUnlock indicates that there is still attractive upside potential despite the high quality.
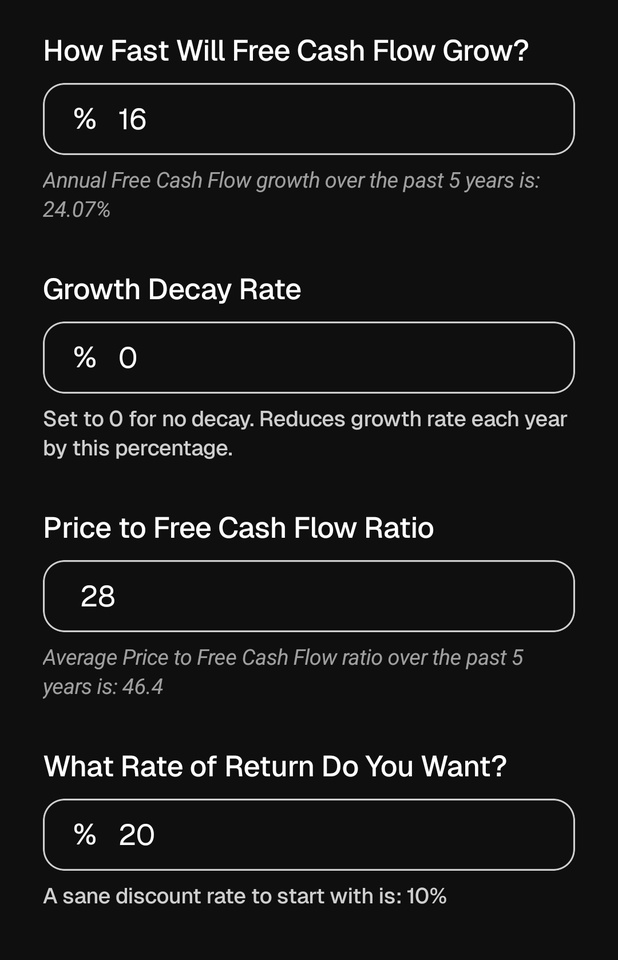
With conservative free cash flow growth of around 16%, this results in an expected performance that can support the target of around 20% CAGR over the next five years.
---
Pros & cons at a glance
Pro :
Dominant market position: Copart has the infrastructure and the auction network that can hardly be replicated by competitors.
Counter-cyclical business: When the economy weakens, the number of accidents often increases or people repair their cars less - this plays into Copart's model (recycling of accident vehicles).
Asset-light model: Once the auction sites are established, any further transaction can be handled with extremely high margins.
Cons :
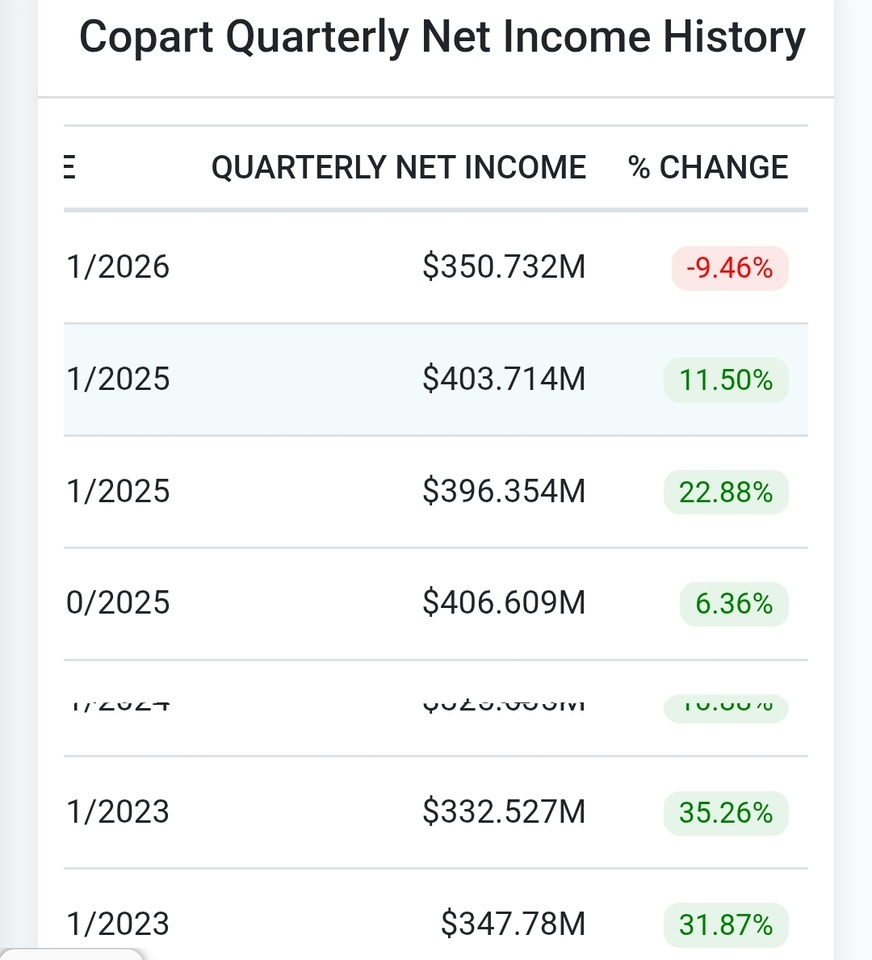
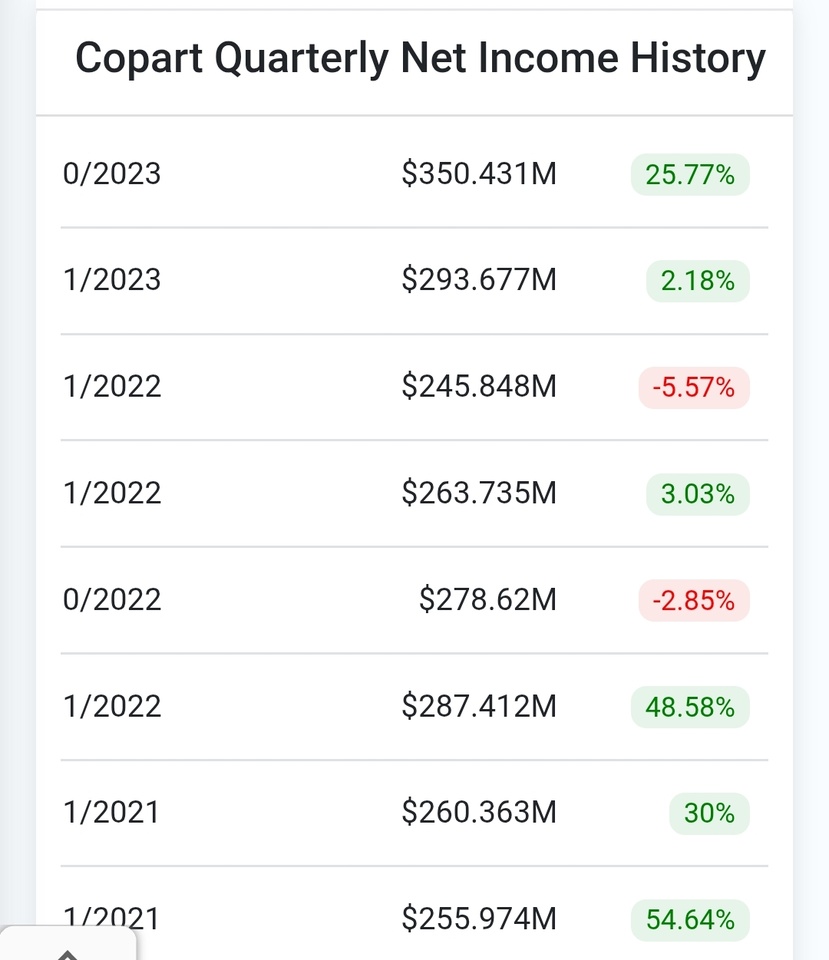
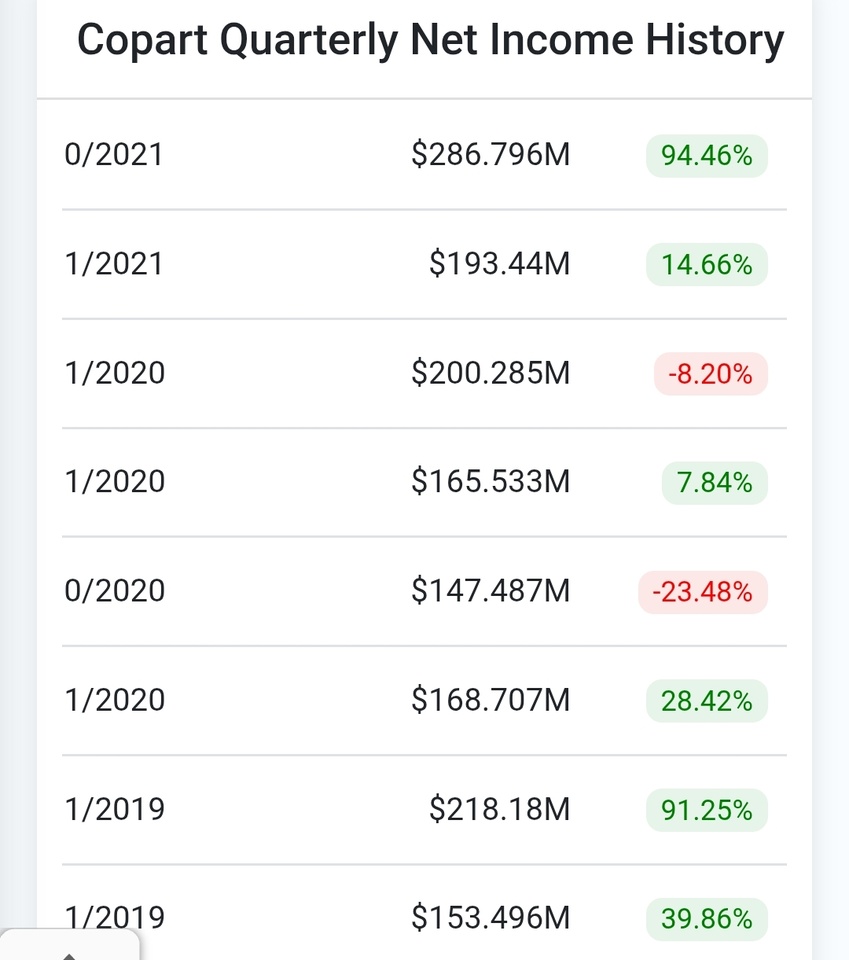
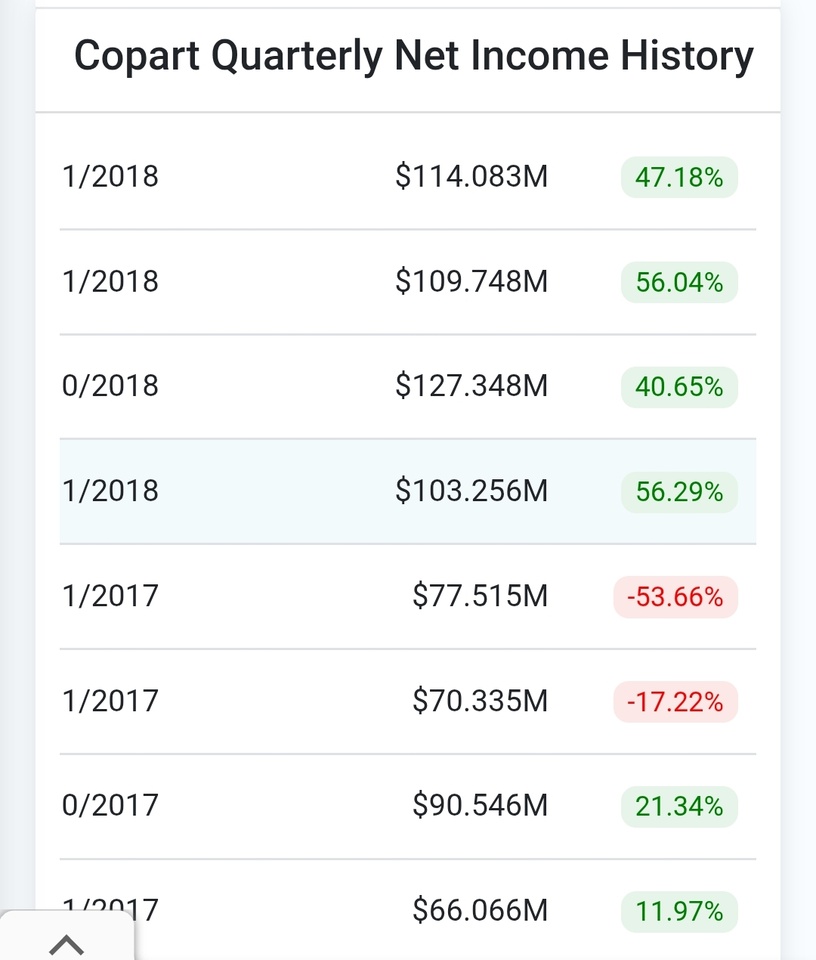
Fluctuating growth: As the quarterly figures show, net profit growth is volatile. This deters short-term investors, but often offers entry opportunities for us as long-term investors.
Dependence on insurance companies: Copart is dependent on insurance companies selling their vehicles through Copart. The balance of power between large insurers and Copart is a critical factor.
---
Conclusion
Copart is not a "get-rich-quick" investment, but a classic quality compounder for long-term investors.
The combination of a dominant market position, a high cash position and a founder's imprint provides a robust basis for sustainable growth.
---
Discussion:
With its almost debt-free model, is Copart a basic investment for you - or are you put off by its uneven growth?
I am invested and own 345 shares
Here is a detailed analysis: