
DraftKings ($DKNG (+4,77%)) is executing a textbook scale-and-monetize strategy across online sports betting, casino iGaming, and digital lotteries. The core investment thesis revolves around its migration to the proprietary SBTech platform. By owning its entire technology stack, the company has structurally improved gross margins, accelerated live-betting features, and lowered customer acquisition costs through multi-product cross-selling.
The financial metrics prove that DraftKings has reached its long-awaited operational inflection point, shifting from a high-growth cash burner into a structurally profitable enterprise.
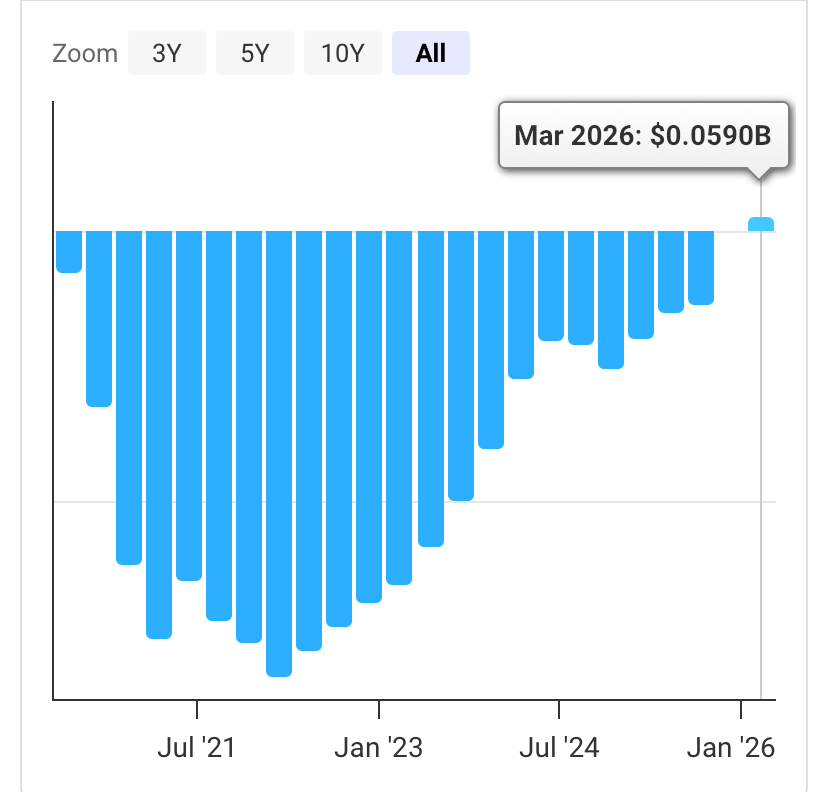
Net Income:
Revenue has compounded aggressively over the years, reaching a record 6.292 billion dollars as of March 2026.
Revenue:
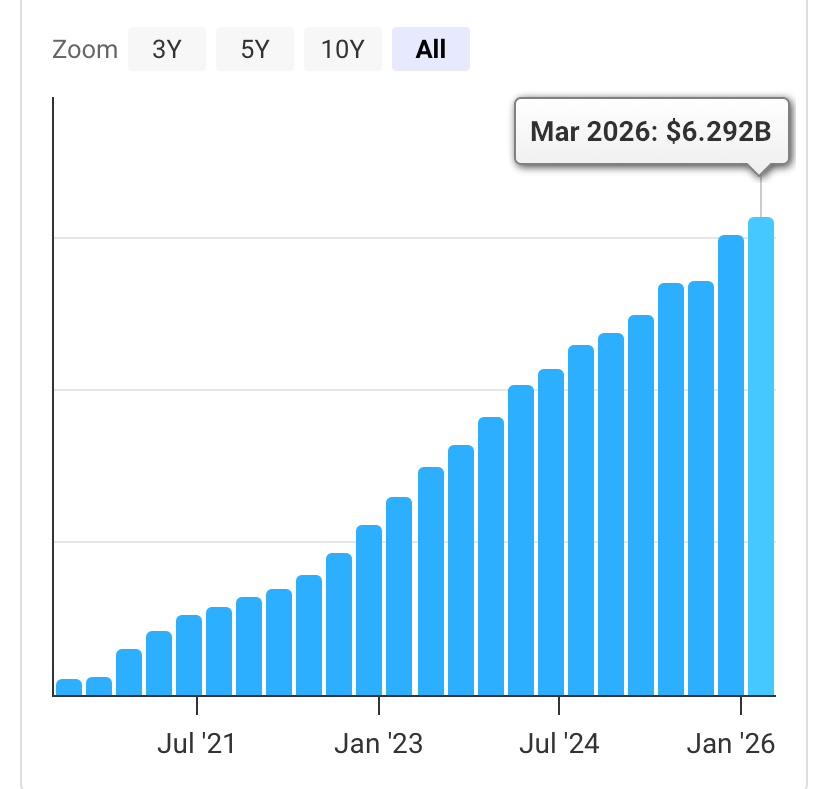
This top-line momentum demonstrates sustained market share gains and excellent user retention.
After enduring steep losses to fund customer acquisition in newly legalized states, net income has finally crossed above the zero-bound line, printing a positive 0.0590 billion dollars for the period ending March 2026. Because core technology and overhead costs are largely fixed, incoming revenue is now flowing directly to the bottom line. This massive operating leverage is set to drive significant earnings per share expansion, giving the stock immense runway as a long-term multibagger.
What do you guys think, should I place $DKNG (+4,77%) 3% of my portfolio?

