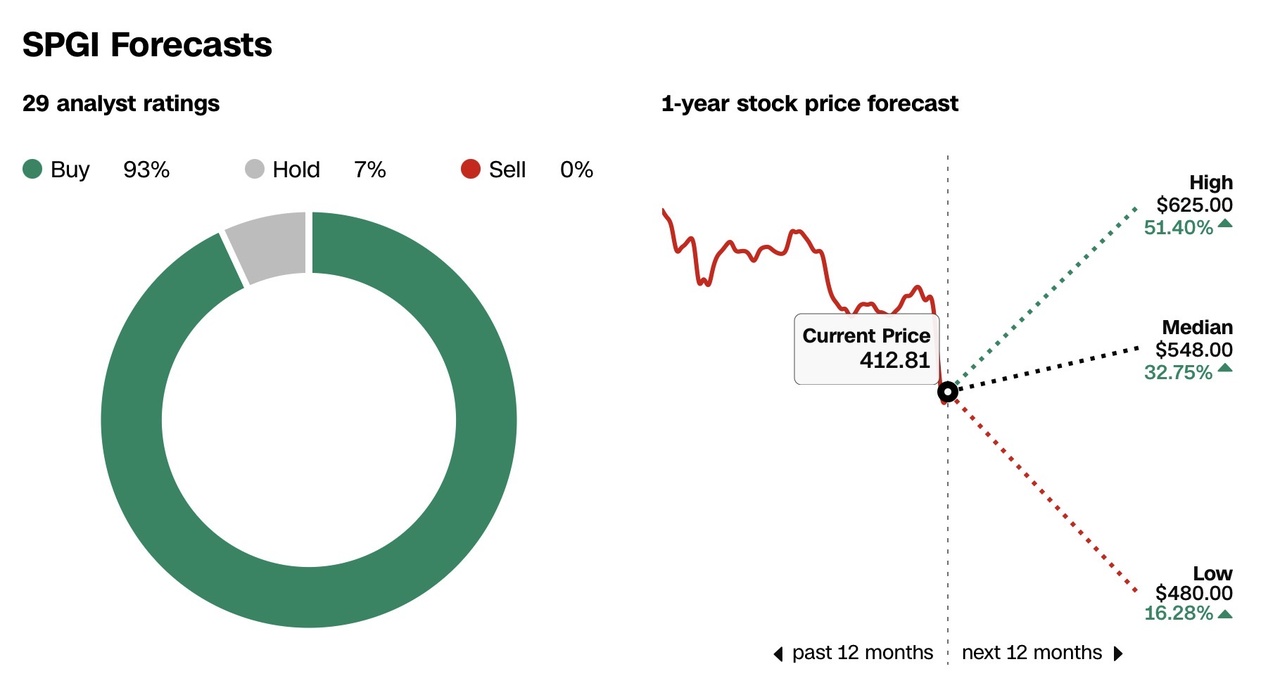
I’m sure Dev Kantesaria and Chris Hohn, two of the most respected investors out there, must have had a rough week. S&P Global dropped 28% in ten days. Moody’s fell 22%. These were supposed to be safe havens. Businesses protected by proprietary data, decades of reputation, regulatory frameworks, and structural moats.
Now that same data advantage suddenly seems to be the perceived weakness. The market appears worried that AI models, especially Anthropic, could replace the legacy credit ratings and data business model. Even earnings that were broadly in line with expectations did nothing to stop the selloff.
Luckily, I sold my S&P Global position just before the major nosedive. That was not genius timing. I simply saw better opportunities in software and cybersecurity and redeployed capital there. But now, at these levels, I am seriously considering reopening the position.
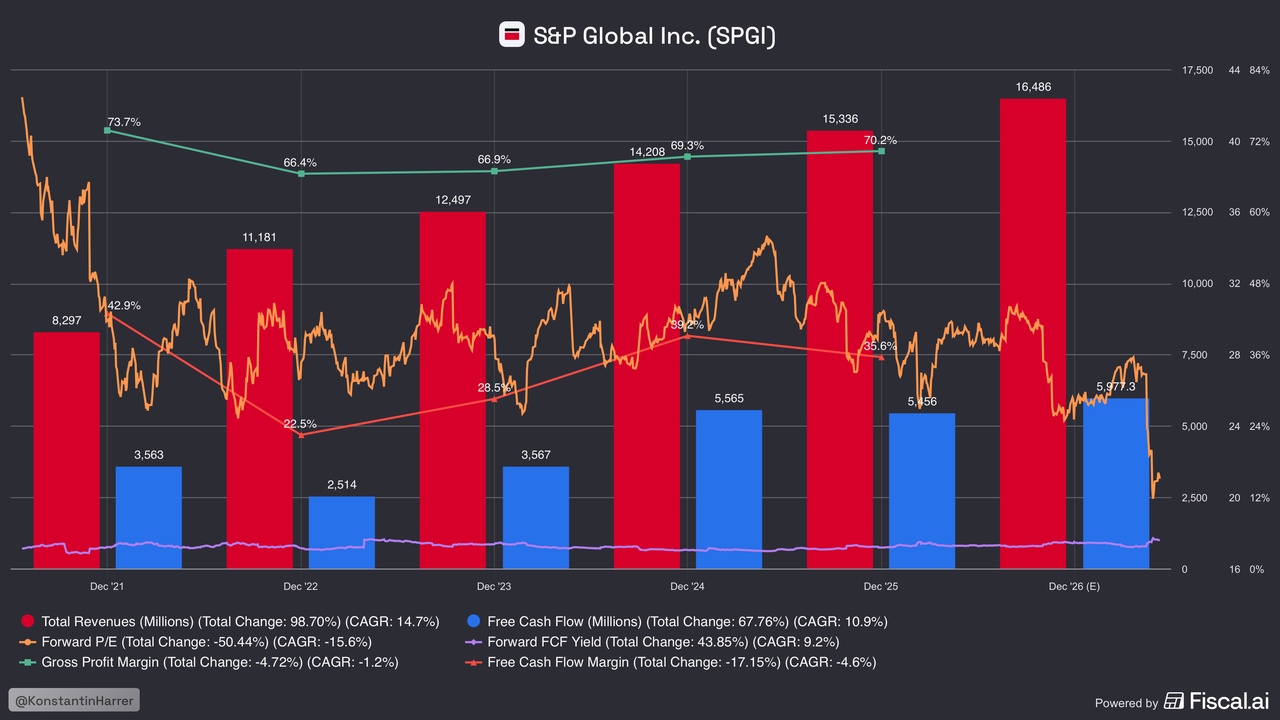
The valuation premium has evaporated. We went from mid-30s P/E multiples to low 20s. That is a significant reset for a business that was long considered untouchable. And the AI disruption narrative feels massively exaggerated.
Most of the core data S&P Global and Moody’s operate with is not publicly accessible. It is deeply embedded in regulatory processes and institutional frameworks. You cannot just “AI” your way into the credit ratings oligopoly. There are legal barriers, compliance hurdles, and decades of trust built into the system. This market is controlled by a handful of entrenched players, and it is not easily penetrated.
What is far more likely, in my view, is that legacy players partner with platforms like Anthropic to improve efficiency rather than being replaced by them. Banks and institutional investors do not want “pretty good.” They require 100% reliability and accountability. AI is powerful, but it is still flawed and probabilistic. In credit markets, that margin of error is unacceptable.
My only real concern with S&P Global is growth. Top-line expansion has slowed and is projected to remain in the high single digits. That makes margin expansion critical. An AI-driven efficiency boost through partnerships could become the key driver of the next leg higher.
With valuation compressed into the low 20s on a forward P/E basis, the stock is becoming very interesting again. I am monitoring closely and seriously considering reopening a position in the mid-$300s.