Sotera $SHC (-2,99%) has reported its numbers and delivered solid results—the thesis remains intact; let’s see if they can keep this up and evolve into a quiet compounder; the foundation looks promising ☢️
Sotera Health (NASDAQ: SHC) – Q2 2026 Earnings Snapshot
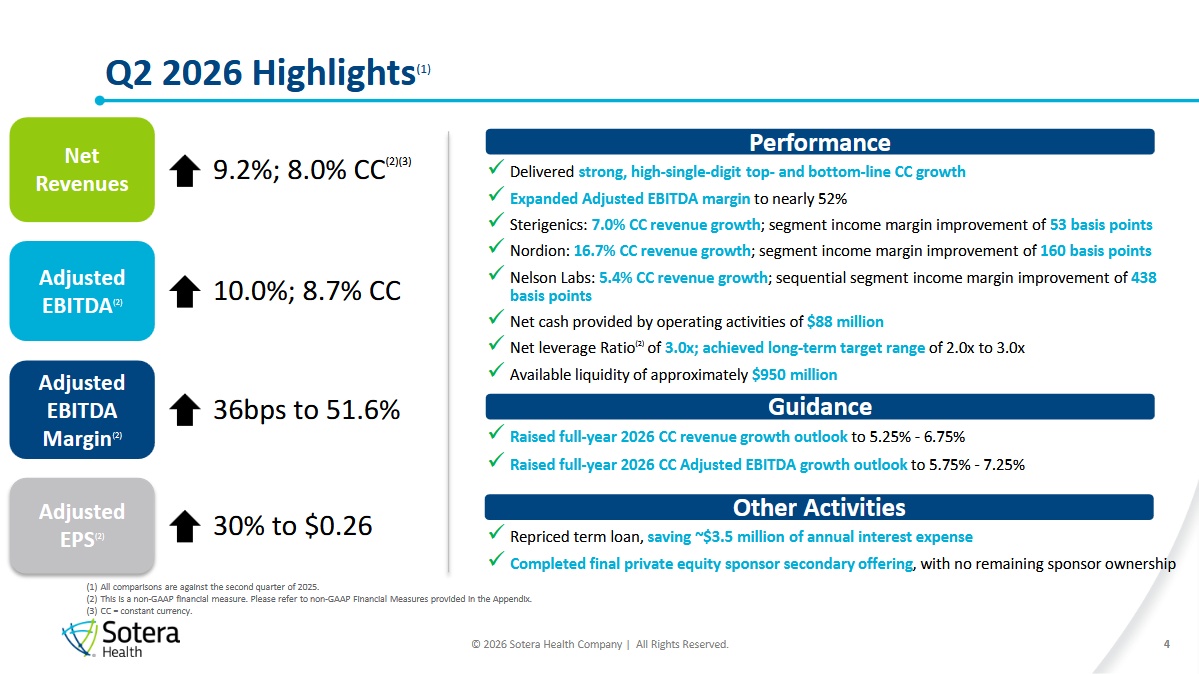
📊 Highlights
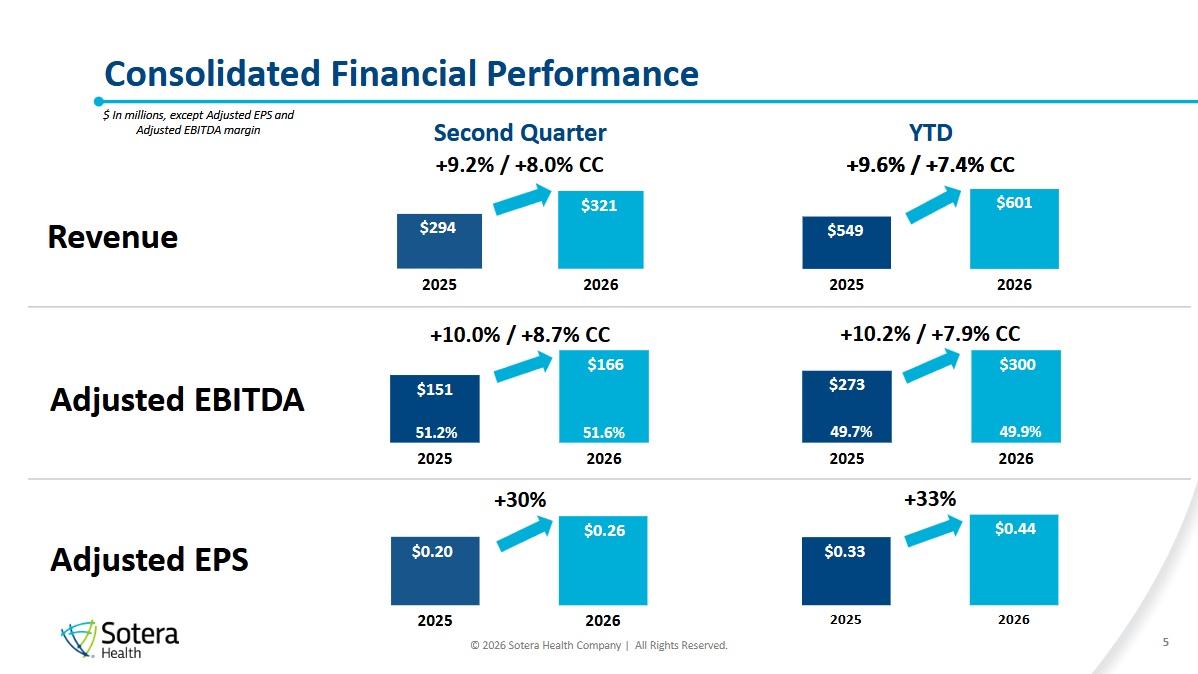
- Revenue:
$321.4M
(Beat vs. $309.7M consensus, +9.2% YoY) - Adjusted EPS:
$0.26
(Beat vs. $0.24 consensus) - Adjusted EBITDA:
+10.0% YoY - Net Income:
$54M
(vs. $8M last year)
📈 Guidance Raised
- Revenue Growth:
5.25–6.75% - Adjusted EBITDA Growth:
5.75–7.25% - Adjusted EPS:
$0.95–1.01
💡 Key Takeaways
- Sterigenics delivered solid volume and pricing growth.
- Nordion posted another outstanding quarter with double-digit growth.
- Net leverage declined to ~3.0x, reaching management’s long-term target range.
- CapEx is expected to decline in 2027, supporting stronger future free cash flow.
- No major negative litigation developments occurred during the quarter
🎯 Investment View
A quarter of high-quality execution that reinforces the long-term thesis. Strong organic growth, raised guidance, continued deleveraging, and improving free cash flow suggest that SHC is increasingly being valued for its operational performance rather than its litigation overhang.
*Thanks, AI—when you don’t have time, at least you get a quick summary 🤣*