And I think that makes it worth explaining why I still believe in it after everything that has happened to the stock.
$ADBE (-0,35%) has been heavily punished over the last few years.
The reason isn't difficult to understand: AI arrived and suddenly the market started questioning whether Photoshop, Illustrator and even the broader Creative Cloud ecosystem could eventually become less relevant.
It's a legitimate concern. And as a shareholder, it's something I've questioned myself.
But then I look at what is actually happening inside the business.
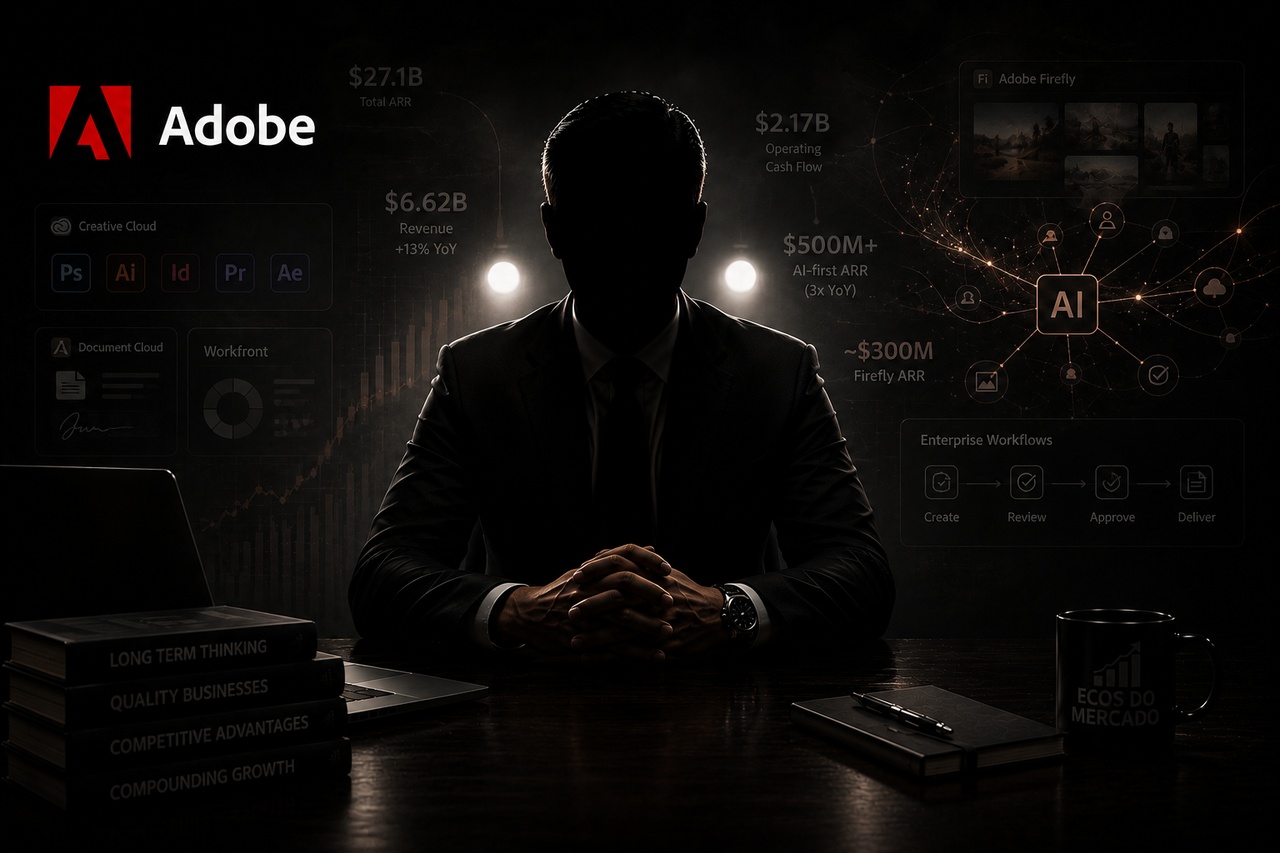
In its latest quarter, Adobe generated $6.62B in revenue, up 13% YoY, subscription revenue grew 14%, operating cash flow reached $2.17B and total ARR reached $27.1B.
More importantly, the part that was supposed to threaten Adobe is starting to become a business for Adobe.
AI-first ARR has more than tripled YoY to over $500M, while Firefly alone is approaching $300M in ARR.
That's what keeps me interested.
I don't think Adobe needs to win the race for the best AI model.
It needs to make AI useful inside the workflows millions of professionals already use every day.
And we're starting to see exactly that.
Firefly is integrating Adobe's own models alongside models from OpenAI, Google, Runway and others.
As someone who actually works with Adobe software, this makes a lot of sense to me.
AI can generate an image in seconds.
But professional creative work doesn't end when the image is generated. It needs to be edited, resized, organized, approved, integrated into other projects and ultimately delivered.
That's the ecosystem $ADBE (-0,35%) has spent decades building.
There are risks, of course. AI is changing this industry incredibly fast.
But after all the headlines about AI potentially killing Adobe, I find it interesting that the actual business keeps growing — and Adobe is already making real money from the technology that was supposed to replace it.
The stock has been punished. The business hasn't.
And that's why Adobe remains my largest position.